
Estimate your new mortgage payment after a rate reset, renewal, or recast and compare it with what you pay now.
Table of contents
How to use our Mortgage Payment Shock Calculator
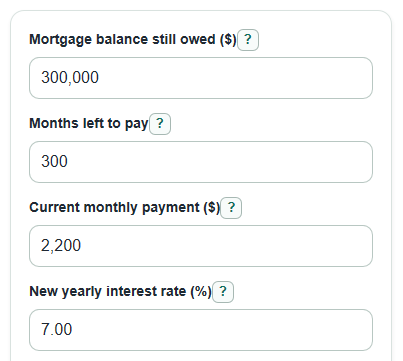
- Enter Mortgage balance still owed ($) from your latest statement, not the original loan amount.
- Enter Months left to pay, Current monthly payment ($), New yearly interest rate (%), and New monthly taxes, insurance, HOA, and PMI ($).
- Open Advanced options if you want New payment share of monthly income or a higher Estimated payment at stress-test rate.
- Click Calculate and compare Estimated new monthly payment with Monthly payment shock and Payment shock as a percent.
- Sanity-check the result: if the new payment looks far too high or low, recheck Months left to pay, the balance, and whether escrow costs were included in both old and new payments.
Definitions
Mortgage balance still owed ($): The unpaid principal balance on the loan today.
Current monthly payment ($): What you pay now each month. Use the total monthly payment if you want a total-payment comparison.
Principal and interest: The loan part of the mortgage payment. Principal pays down the balance, and interest is the lender charge for borrowing.
Total monthly payment: Principal, interest, mortgage insurance when it applies, and escrowed taxes and homeowners insurance; some HOA fees may be paid separately [2].
New monthly taxes, insurance, HOA, and PMI ($): The monthly non-loan costs you want included in the new estimated payment.
Payment shock: The signed change from the current payment to the estimated new payment. Positive means the payment rises. Negative means it falls.
Extra rate to test (percentage points): The added rate used for the stress test. One percentage point changes 7% to 8%, not to 7.07%.
Common mistakes and quick fixes
Mistake: Using the original loan amount for Mortgage balance still owed ($).
Fix: Use the current principal balance from your mortgage statement.
Mistake: Entering years instead of months in Months left to pay.
Fix: Multiply years by 12, so 25 years left is 300 months.
Mistake: Comparing Current monthly payment ($) without escrow to a new payment that includes New monthly taxes, insurance, HOA, and PMI ($).
Fix: Use the same payment style on both sides when possible, or know that the shock includes the added escrow difference.
Mistake: Typing 0.07 in New yearly interest rate (%) when you mean 7%.
Fix: Enter 7 for 7%, or 7.25 for 7.25%.
Mistake: Treating Extra rate to test (percentage points) as a percent multiplier.
Fix: Enter 1 to test one full percentage point higher, such as 7% becoming 8%.
Mistake: Entering annual income in Monthly household income before taxes ($).
Fix: Use one month of income before taxes, such as 8,000 if the household earns $96,000 per year.
Limitations & Key Assumptions / Boundary Conditions
- This is an estimate, not a lender quote. Your servicer may use exact dates, fees, rounding rules, escrow analysis, or rate caps that are not entered here.
- The calculator assumes the Mortgage balance still owed ($) is newly amortized across the entered Months left to pay.
- New monthly taxes, insurance, HOA, and PMI ($) is treated as one monthly amount. It does not forecast future tax bills, insurance premiums, HOA dues, or PMI cancellation.
- Current monthly payment ($) should be comparable with the new payment. If one includes escrow and the other does not, the shock mixes loan-rate change with escrow change.
- The stress test adds Extra rate to test (percentage points) directly to New yearly interest rate (%). It does not apply ARM adjustment caps or lifetime caps.
- Monthly household income before taxes ($) is optional and uses gross monthly income. It does not measure debt-to-income ratio because it ignores other debts and living costs.
- Very short remaining terms can create large payments. Recheck Months left to pay if the result seems extreme.
Methodology
Calculation steps
The calculator first converts the New yearly interest rate (%) to a monthly decimal rate by dividing by 100 and then by 12.
monthly_rate = new_yearly_interest_rate_percent / 100 / 12
It then calculates the amortized loan payment on Mortgage balance still owed ($) over Months left to pay. If the monthly rate is 0, it divides the balance evenly across the remaining months.
new_principal_and_interest_payment = balance * monthly_rate * (1 + monthly_rate)^months_left / ((1 + monthly_rate)^months_left - 1)
if monthly_rate = 0: new_principal_and_interest_payment = balance / months_left
The estimated total payment adds the entered escrow-style monthly costs. CFPB explains that total monthly mortgage payments can include principal, interest, mortgage insurance, escrowed taxes, and insurance [2].
new_monthly_payment = new_principal_and_interest_payment + new_monthly_escrow
Payment shock is the new total payment minus Current monthly payment ($). The sign is kept because a negative shock means the estimated payment is lower than today.
monthly_payment_shock = new_monthly_payment - current_monthly_payment
payment_shock_percent = monthly_payment_shock / current_monthly_payment * 100
The stress-test payment uses the same balance, term, and escrow, but adds Extra rate to test (percentage points) to the new yearly rate. This is useful because adjustable-rate mortgage payments can change over time [1], and regulators use the term payment shock when discussing recasts and higher required payments [3].
stress_test_monthly_payment = payment(balance, (new_interest_rate_percent + stress_extra_rate_percent) / 100 / 12, months_left) + new_monthly_escrow
If Monthly household income before taxes ($) is entered, the calculator divides the new total payment by that income.
income_share_after_reset = new_monthly_payment / monthly_household_income * 100
Mini-example
Suppose the balance is $300,000, 300 months are left, the current payment is $2,200, the new rate is 7%, and new monthly escrow-style costs are $600. The new principal-and-interest payment is about $2,120.34, so the estimated new monthly payment is about $2,720.34. The monthly payment shock is $520.34, which is about 23.65% higher than the current payment. With $8,000 of monthly household income, the new payment uses about 34.00% of income. If the stress-test rate is one point higher, the estimated payment is about $2,915.45.
Sources
- Adjustable-Rate Mortgages: Find out how your payment can change over time | Consumer Financial Protection Bureau - Consumerfinance
- On a mortgage, what's the difference between my principal and interest payment and my total monthly payment? | Consumer Financial Protection Bureau - Consumerfinance
- Interagency Guidance on Nontraditional-Mortgage-Product Risks - Federalreserve