
Estimate your lower principal-and-interest payment after a mortgage recast and compare it with keeping the old payment.
Table of contents
How to use our Mortgage Recast Calculator
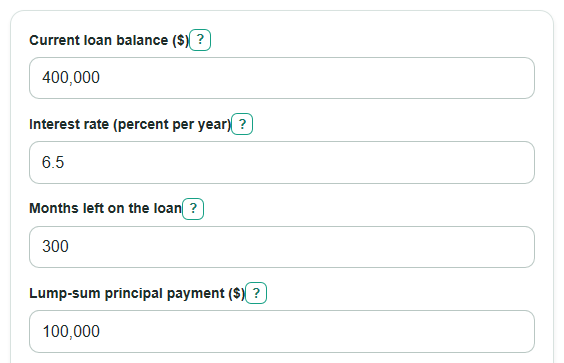
- Enter your Current loan balance, Interest rate, Months left on the loan, and Lump-sum principal payment using today's loan information.
- Open Advanced options if you want to include a Recast fee or test a higher Payment you may make after recast.
- Select Calculate to see the New monthly principal and interest payment, Monthly payment drop, fee payback, and interest comparison.
- Sanity-check the Old estimated monthly principal and interest payment against your mortgage statement; if your statement includes escrow, taxes, or insurance, compare only the principal-and-interest part.
- Use the keep-old-payment results to decide whether you want lower required payments, faster payoff, or a mix of both.
Definitions
Mortgage recast: A lender-approved recalculation of the required payment after a large principal payment, usually keeping the same rate and remaining term [2].
Principal: The loan balance you still owe, before future interest is added. Part of each mortgage payment pays principal and part pays interest [1].
Principal and interest payment: The loan payment part that pays down the balance and interest. It does not include taxes, homeowners insurance, mortgage insurance, or HOA dues.
Lump-sum principal payment: A one-time payment applied directly to the loan balance before the recast calculation.
Recast fee: A servicer charge for processing the recast. The calculator subtracts it from estimated interest savings.
Payment drop: The old estimated principal-and-interest payment minus the new recast payment. A positive number means the required payment goes down.
Common mistakes and quick fixes
Mistake: Entering the full mortgage payment in Current loan balance.
Fix: Use the unpaid principal balance only, not taxes, insurance, escrow, late fees, or interest due.
Mistake: Using APR in Interest rate.
Fix: Enter the loan's note rate if you have it, because a recast normally keeps the same interest rate.
Mistake: Typing years into Months left on the loan.
Fix: Convert years to months first, so 25 years becomes 300 months.
Mistake: Making Lump-sum principal payment equal to or larger than Current loan balance.
Fix: Enter a lump sum below the balance; paying the full balance means payoff, not a recast.
Mistake: Leaving Recast fee at a number that does not match your servicer.
Fix: Enter your actual fee, or enter 0 if your lender does not charge one.
Mistake: Entering a Payment you may make after recast that is below the New monthly principal and interest payment.
Fix: Leave it blank or enter at least the new required payment.
Limitations & Key Assumptions / Boundary Conditions
- This is a principal-and-interest estimate only. It does not include property taxes, homeowners insurance, mortgage insurance, HOA dues, escrow changes, late fees, or lender rounding.
- A mortgage recast usually requires servicer approval. Minimum lump-sum rules, fees, loan-type limits, and timing can differ by lender.
- The estimate assumes a fixed interest rate, the same remaining term, monthly payments, and no new fees except the Recast fee you enter.
- If your loan is adjustable-rate, interest-only, negatively amortizing, in forbearance, modified, or has unusual payment rules, the result may not match your servicer's calculation.
- The keep-old-payment comparison assumes the same lump-sum principal payment is made and then the Old estimated monthly principal and interest payment continues until payoff.
- The optional planned-payment results are shown only when Payment you may make after recast is entered and is at least as high as the new recast payment.
Methodology
How the recast payment is estimated
The calculator converts Interest rate from a percent per year to a monthly decimal rate, then estimates the old payment from Current loan balance and Months left on the loan. It then subtracts Lump-sum principal payment to find the balance used for the recast.
monthly_rate = Interest rate / 100 / 12
balance_after_lump_sum = Current loan balance - Lump-sum principal payment
For a positive monthly rate, the fixed-payment formula is used for both the old payment and the new recast payment.
payment = principal * monthly_rate / (1 - (1 + monthly_rate)^(-months_left))
If the Interest rate is 0, the payment is the principal divided by Months left on the loan.
payment = principal / months_left
Savings calculations
Monthly payment drop is the old estimated principal-and-interest payment minus the new recast payment. Remaining interest is estimated as total scheduled payments minus the starting principal for that scenario.
monthly_payment_drop = old_monthly_payment - new_monthly_payment
remaining_interest = payment * months_left - principal
interest_saved_after_fee = old_remaining_interest - recast_remaining_interest - Recast fee
fee_payback_months = Recast fee / monthly_payment_drop
If Recast fee is 0, fee payback is 0 months. If the payment drop is 0 or negative, fee payback is shown as N/A instead of dividing by zero.
Keep-old-payment comparison
To estimate payoff time when you keep paying the old amount, the calculator uses the balance after the lump sum and applies interest month by month. The last payment can be smaller than the chosen monthly payment.
interest = balance * monthly_rate
payment_this_month = min(chosen_payment, balance + interest)
new_balance = balance + interest - payment_this_month
The same loop is used for Payment you may make after recast when that optional amount is entered. Extra interest saved is the interest from paying only the new recast payment minus the interest from the higher chosen payment.
Mini-example
With a Current loan balance of $400,000, Interest rate of 6.5 percent, Months left on the loan of 300, Lump-sum principal payment of $100,000, and Recast fee of $250, the estimated old payment is $2,700.83 per month. The balance after the lump sum is $300,000, the new recast payment is $2,025.62 per month, and the monthly payment drop is $675.21. The fee is covered by the payment drop in about 0.37 months, and the estimated interest saved after fee is about $102,312.15.