
Estimate your full monthly mortgage cost and see how much goes to the loan, taxes, insurance, PMI, HOA, and extra principal.
Table of contents
How to use our Mortgage Payment Breakdown Calculator
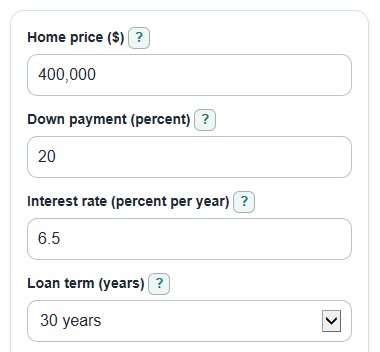
- Enter the Home price ($), Down payment (percent), Interest rate (percent per year), Loan term (years), and Property tax (percent of home price per year).
- Open Advanced options if you want to add Home insurance ($ per year), HOA fee ($ per month), PMI rate (percent of loan per year), When should PMI stop?, or Extra principal ($ per month).
- Click Calculate to see Total to send this month, the PMI stop estimate, the payment after PMI stops, and each monthly cost part.
- Check whether the Total to send this month is higher than the Loan payment: principal and interest. The difference is usually tax, insurance, PMI, HOA, and extra principal.
- If the result looks too high or too low, recheck yearly inputs versus monthly inputs, especially Interest rate (percent per year), Property tax (percent of home price per year), Home insurance ($ per year), and HOA fee ($ per month).
Definitions
Home price ($): The purchase price used to estimate the loan, taxes, and PMI thresholds.
Down payment (percent): The share of the home price you pay up front instead of borrowing.
Loan payment: principal and interest: The fixed loan payment on a fixed-rate mortgage before taxes, insurance, PMI, HOA, or extra principal. CFPB describes principal and interest as only part of the total monthly mortgage payment [1].
Property tax part: The estimated yearly property tax split into 12 monthly pieces.
PMI: Private mortgage insurance, a mortgage insurance cost that may apply when the down payment is smaller. Some PMI can be removed when the borrower and loan meet required rules [2].
PMI stops after payment number: The estimated scheduled payment number after which this calculator stops adding PMI under the selected rule.
Extra principal ($ per month): Money paid above the scheduled loan payment to reduce the loan balance faster.
Estimated total interest: The interest charged over the estimated payoff time, not including tax, insurance, PMI, HOA, closing costs, or future changes.
Common mistakes and quick fixes
Mistake: Entering a dollar down payment in Down payment (percent).
Fix: Use the percent of Home price ($) paid up front, such as 20 for 20 percent.
Mistake: Typing a monthly tax bill into Property tax (percent of home price per year).
Fix: Enter the yearly tax rate as a percent, such as 1.2, and let the calculator show Property tax part.
Mistake: Putting a monthly insurance cost in Home insurance ($ per year).
Fix: Enter the yearly premium, or multiply the monthly premium by 12 first.
Mistake: Leaving PMI rate (percent of loan per year) above 0 while choosing No PMI in When should PMI stop?.
Fix: Use No PMI when you want Monthly PMI part now to be $0, or choose Auto stop estimate if PMI should start and later stop.
Mistake: Treating HOA fee part as part of the lender's mortgage bill.
Fix: Keep HOA fee ($ per month) in the estimate, but remember HOA fees are often paid separately from the mortgage payment.
Mistake: Assuming Interest saved by extra principal is guaranteed from Extra principal ($ per month).
Fix: Use it as an estimate and confirm that your loan allows extra principal payments without a prepayment penalty.
Limitations & Key Assumptions / Boundary Conditions
- This calculator estimates a fixed-rate mortgage. It does not handle adjustable-rate loans, interest-only periods, balloon payments, buydowns, or refinance costs.
- Property tax part and Home insurance part are simple monthly averages. Real bills can change by year, location, assessment, escrow shortage, coverage, deductible, and insurer pricing.
- The PMI stop estimate is simplified for conventional PMI. Actual PMI cancellation can depend on loan program, servicer rules, payment history, property value, junior liens, and whether you request cancellation in writing.
- The Auto stop estimate uses the first scheduled payment where the balance reaches 78 percent of the original home price, with a midpoint cap based on 50 percent of the original loan term. It does not use future home value growth.
- Extra principal ($ per month) is treated as a steady monthly amount. Missed extra payments, one-time extra payments, payment timing, or lender posting rules can change Estimated payoff time and Estimated total interest.
- HOA fee part is included in Total to send this month for budgeting, but many borrowers pay HOA fees outside the mortgage bill.
- Closing costs, lender fees, points, escrow setup deposits, maintenance, utilities, and income taxes are not included.
Methodology
Loan amount and scheduled loan payment
The calculator first turns the Home price ($) and Down payment (percent) into the amount borrowed.
loan_amount = home_price - (home_price * down_payment_percent / 100)
It then calculates the fixed monthly principal and interest payment. The number of payments is the Loan term (years) times 12.
monthly_rate = interest_rate_percent / 100 / 12
number_of_payments = loan_term_years * 12
if monthly_rate = 0: monthly_principal_interest = loan_amount / number_of_payments
if monthly_rate > 0: monthly_principal_interest = loan_amount * monthly_rate * (1 + monthly_rate)^number_of_payments / ((1 + monthly_rate)^number_of_payments - 1)
Monthly cost parts
Total monthly mortgage cost can include principal, interest, mortgage insurance, taxes, insurance, and other fees such as HOA dues [1]. This calculator converts yearly tax, insurance, and PMI inputs into monthly amounts.
monthly_tax = home_price * property_tax_percent / 100 / 12
monthly_insurance = annual_home_insurance / 12
monthly_pmi = loan_amount * pmi_rate_percent / 100 / 12 when PMI is active
total_monthly_payment = monthly_principal_interest + monthly_tax + monthly_insurance + monthly_pmi + monthly_hoa + extra_principal_payment
PMI stop estimate
For Auto stop estimate, the calculator checks the scheduled loan balance after each scheduled payment. It finds the first payment where the remaining balance is at or below 78 percent of the original home price, then applies the midpoint cap if that is earlier. CFPB explains that PMI cancellation and termination depend on specific criteria, including payment history and loan status [1].
if monthly_rate = 0: balance_m = loan_amount - monthly_principal_interest * m
if monthly_rate > 0: balance_m = loan_amount * (1 + monthly_rate)^m - monthly_principal_interest * (((1 + monthly_rate)^m - 1) / monthly_rate)
monthly_after_pmi = total_monthly_payment - monthly_pmi
Extra principal and total interest
To estimate payoff time and total interest with Extra principal ($ per month), the calculator runs month by month. Interest is added first, then the payment is applied. The final payment can be smaller than the normal monthly amount.
interest = balance * monthly_rate
payment_sent = min(monthly_principal_interest + extra_principal_payment, balance + interest)
new_balance = balance + interest - payment_sent
total_interest = sum(all monthly interest charges until payoff)
interest_saved_by_extra = scheduled_interest_without_extra - total_interest_with_extra
Mini example
For a $350,000 home with 10 percent down, a 30-year loan at 6 percent interest, 1 percent yearly property tax, $1,400 yearly home insurance, no HOA fee, and a 0.5 percent PMI rate, the loan amount is $315,000. The scheduled Loan payment: principal and interest is about $1,888.58 per month. The Property tax part is about $291.67, Home insurance part is about $116.67, and PMI part now is $131.25. Total to send this month is about $2,428.17. With Auto stop estimate, PMI stops after payment number 103, so the Estimated monthly payment after PMI stops is about $2,296.92.
Sources
- On a mortgage, what's the difference between my principal and interest payment and my total monthly payment? | Consumer Financial Protection Bureau - Consumerfinance
- When can I remove private mortgage insurance (PMI) from my loan? | Consumer Financial Protection Bureau - Consumerfinance
- Components of a mortgage payment | Wells Fargo - Wellsfargo