
Estimate the highest used-car sticker price that fits your monthly budget after loan costs, taxes, fees, trade-in details, and running costs.
Advanced options
Table of contents
How to use our Used Car Affordability Calculator
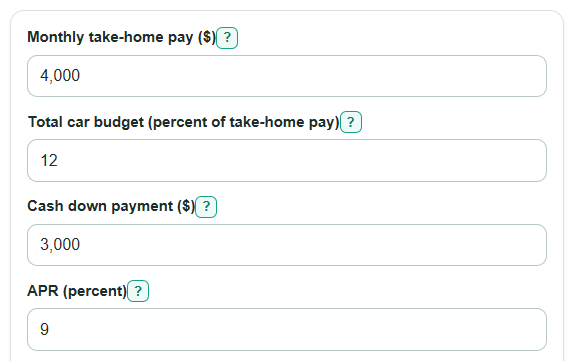
- Enter Monthly take-home pay, then choose the Total car budget percent you want to use for all car costs.
- Enter Cash down payment, APR, and Loan term so the calculator can find the loan size that matches your payment budget.
- Open Advanced options if you want a tighter estimate, then add Insurance, gas, and repairs, Sales tax rate, Title, registration, and dealer fees, Trade-in value, and Amount still owed on trade-in.
- Click Calculate and read Max used-car sticker price first, then compare Loan payment that fits with the monthly payment a lender or dealer quotes.
- Sanity-check the result by changing APR, Loan term, and Insurance, gas, and repairs; if a small change breaks the budget, shop below the Max used-car sticker price.
Definitions
Monthly take-home pay: The money you receive in a normal month after taxes and paycheck deductions.
Total car budget: The percent of take-home pay you want to spend on the loan payment plus regular car costs.
APR: Annual percentage rate, or the yearly cost of borrowing stated as a percent. It is one number to compare when looking at auto loan offers [1].
Loan term: The number of months used to pay back the auto loan.
Insurance, gas, and repairs: Your monthly estimate for ownership costs outside the loan payment.
Loan amount you can afford: The largest amount the loan can cover at the entered APR, term, and payment budget.
Trade-in equity: Trade-in value minus Amount still owed on trade-in. A negative value means old debt is being rolled into the next deal.
Max used-car sticker price: The highest vehicle listing price that fits the budget and deal details entered.
Common mistakes and quick fixes
Mistake: Entering gross salary in Monthly take-home pay.
Fix: Use the amount you actually receive each month after taxes, health insurance, retirement deductions, and other paycheck deductions.
Mistake: Treating Total car budget as the loan payment only.
Fix: Remember that Total car budget is for the loan plus Insurance, gas, and repairs.
Mistake: Leaving Amount still owed on trade-in at $0 when the old car still has a loan.
Fix: Enter the payoff amount so Trade-in equity can show whether the trade helps or hurts the deal.
Mistake: Comparing Max used-car sticker price with an out-the-door price that already includes taxes and fees.
Fix: Use Max used-car sticker price as the vehicle listing price before Sales tax rate and Title, registration, and dealer fees.
Mistake: Using a guessed APR when you already have a preapproval quote.
Fix: Put the quoted APR into APR so Loan amount you can afford is based on your actual borrowing cost.
Limitations & Key Assumptions / Boundary Conditions
- This result is a shopping limit, not a loan approval. A lender can approve less or charge a different APR based on credit, income, debt, vehicle age, mileage, and loan rules.
- The calculator assumes Sales tax rate applies to the vehicle sticker price before fixed Title, registration, and dealer fees. Some states tax after trade-in credit or handle fees differently.
- Insurance, gas, and repairs is only as good as your estimate. Used-car repair needs can vary a lot by vehicle age, mileage, condition, and warranty coverage.
- Dealer add-ons, extended warranties, gap coverage, documentation fees, and lender fees only affect the result if you include them in Title, registration, and dealer fees.
- Monthly payments are modeled as fixed payments made on schedule for the full Loan term. Extra payments, late fees, prepayment, or refinancing will change the final interest cost.
- If Loan payment that fits is $0 or less, the entered running costs use the whole Total car budget before any loan payment can be made.
Methodology
Calculation steps
The calculator starts with a full monthly car budget, then subtracts non-loan costs before solving for the loan. This matters because focusing only on the monthly loan payment can miss other costs that affect the total cost of owning the car [2].
total_monthly_car_budget = monthly_take_home * car_budget_percent / 100
monthly_loan_budget = total_monthly_car_budget - monthly_running_costs
The loan amount is the present value of a fixed monthly payment. APR is converted to a monthly rate by dividing by 100 and then by 12.
monthly_rate = apr / 100 / 12
if monthly_rate = 0: max_amount_financed = monthly_loan_budget * loan_term_months
otherwise: max_amount_financed = monthly_loan_budget * (1 - (1 + monthly_rate)^(-loan_term_months)) / monthly_rate
Trade-in equity is kept signed, because negative equity reduces the affordable vehicle price.
trade_equity = trade_in_value - trade_owed
The maximum sticker price is backed out after the loan amount, cash down payment, trade-in details, fixed fees, and sales tax.
max_vehicle_price = (max_amount_financed + down_payment + trade_in_value - trade_owed - title_registration_dealer_fees) / (1 + sales_tax_percent / 100)
Estimated interest is the total scheduled loan payments minus the affordable loan amount.
estimated_total_interest = monthly_loan_budget * loan_term_months - max_amount_financed
The down payment share is shown only when the maximum sticker price is greater than $0.
down_payment_share = down_payment / max_vehicle_price * 100
Worked example
With $4,000 Monthly take-home pay, a 12% Total car budget, and $250 for Insurance, gas, and repairs, the Total monthly car budget is $480 and the Loan payment that fits is $230 per month. At 9% APR for 60 months, that payment supports about $11,080 in loan amount. With a $3,000 Cash down payment, 7% Sales tax rate, $600 in Title, registration, and dealer fees, and no trade-in, the Max used-car sticker price is about $12,598. Estimated interest if paid on schedule is about $2,720, and the down payment is about 23.8% of the car price.