
Compare a personal loan and balance transfer using the same debt, budget, fees, rates, and payoff assumptions.
Table of contents
How to use our Personal Loan vs Balance Transfer Calculator
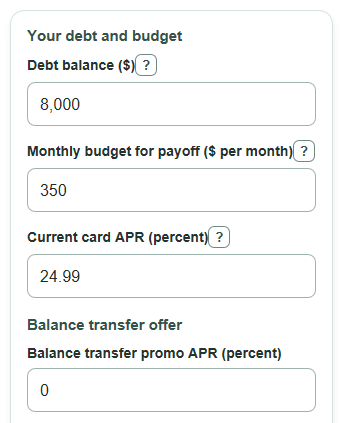
- Enter the Debt balance, Monthly budget for payoff, and Current card APR so the calculator can compare both offers against your current card.
- Enter the balance transfer offer details: Balance transfer promo APR, Balance transfer promo length, Balance transfer fee, and APR after promo ends.
- Enter the personal loan offer details: Personal loan annual interest rate, Personal loan term, and Personal loan origination fee.
- Choose Calculate to see the cheaper option first, then review Balance transfer total paid and Personal loan total paid after fee.
- Sanity-check the answer by comparing Personal loan monthly payment with your Monthly budget for payoff and checking Balance left when promo ends.
Definitions
Card APR is the annual rate used for the card-interest estimate [1]. For "Personal loan annual interest rate", enter the contract rate used to charge interest, not a fee-inclusive APR. The origination fee is counted separately.
Balance transfer promo APR: The special yearly rate used during the promo months on the transferred balance.
Balance transfer promo length: The number of months the special balance transfer rate lasts before the regular APR starts.
Balance transfer fee: A fee charged as a percent of the debt moved. This calculator adds it to the starting transfer balance.
Personal loan term: The number of monthly payments in the loan offer.
Personal loan origination fee: A lender fee charged as a percent of the debt balance. This calculator counts it as an extra cost, not added loan principal.
Balance transfer cost minus personal loan cost: A signed cost gap. Positive means the balance transfer costs more. Negative means the balance transfer costs less.
Common mistakes and quick fixes
Mistake: Entering only the amount you hope to transfer instead of the full Debt balance.
Fix: Use the full Debt balance you want to move or refinance, including all card balances covered by the offer.
Mistake: Using a minimum payment as the Monthly budget for payoff when you plan to pay extra.
Fix: Enter the real Monthly budget for payoff you can send every month, because it drives the balance transfer payoff time.
Mistake: Typing 0 for APR after promo ends because the Balance transfer promo APR is 0.
Fix: Enter the real APR after promo ends from the offer terms, unless the balance will be fully paid before the promo ends.
Mistake: Comparing Balance transfer total paid with Personal loan monthly payment.
Fix: Compare Balance transfer total paid with Personal loan total paid after fee for the cost decision, then use Personal loan monthly payment for budget fit.
Mistake: Leaving Personal loan origination fee as 0 when the lender charges a fee.
Fix: Enter the Personal loan origination fee percent from the loan quote so Personal loan total paid after fee includes it.
Mistake: Ignoring a positive Personal loan payment compared with your budget.
Fix: If Personal loan payment compared with your budget is positive, the loan payment is above your Monthly budget for payoff.
Limitations & Key Assumptions / Boundary Conditions
- The comparison uses one Debt balance and one Monthly budget for payoff for both offer types.
- The balance transfer fee is modeled as added to the transferred balance. A card issuer may charge or collect fees differently.
- The personal loan origination fee is counted as an extra cost outside the loan principal. Some lenders subtract the fee from the amount you receive or add it to the financed amount.
- The balance transfer and current-card payoff use monthly compounding with a fixed payment amount. Real credit card billing can vary because of daily interest, statement timing, minimum payments, and new purchases.
- The personal loan payment assumes a fixed-rate installment loan with equal monthly payments.
- The calculator does not include late fees, annual fees, credit score effects, taxes, rewards, hardship plans, or offer approval rules.
- If the payoff simulation reaches 1,200 months or the payment cannot reduce the balance, the calculator shows an error or warning instead of treating the estimate as reliable.
Methodology
How the comparison is calculated
The calculator compares a balance transfer, a personal loan, and keeping the current card. Card APRs and the personal loan contract interest rate are divided by 100 and 12 for monthly interest. Transfer and origination fees are counted separately under the assumptions below.
monthly_rate = apr_percent / 100 / 12
Personal loan path
The personal loan uses the Debt balance as the loan principal. The fixed monthly payment comes from the standard amortizing loan formula.
if monthly_rate = 0: payment = debt_balance / personal_loan_term_months
otherwise: payment = debt_balance * monthly_rate / (1 - (1 + monthly_rate)^(-personal_loan_term_months))
The origination fee is then added as a separate cost.
personal_loan_total_cost = payment * personal_loan_term_months + debt_balance * personal_loan_origination_fee_percent / 100
budget_fit_amount = personal_loan_monthly_payment - monthly_budget
Balance transfer path
The balance transfer starts with the Debt balance plus the transfer fee. Each month, interest is added first, then the Monthly budget for payoff is applied. The promo APR is used through the Balance transfer promo length. After that, APR after promo ends is used on any remaining balance.
bt_start_balance = debt_balance * (1 + balance_transfer_fee_percent / 100)
interest = balance * monthly_rate_for_that_month
payment_used = min(monthly_budget, balance + interest)
new_balance = balance + interest - payment_used
The final month can be smaller than the normal monthly budget. Balance left when promo ends is saved after the last promo-rate month, or set to $0 if the debt is already paid off.
Cost gap and savings
The main comparison uses total paid, not just interest, because both offer types can include fees.
cost_gap_bt_minus_loan = balance_transfer_total_cost - personal_loan_total_cost
lower_cost_savings = abs(cost_gap_bt_minus_loan)
If Balance transfer cost minus personal loan cost is positive, the personal loan costs less. If it is negative, the balance transfer costs less. If it rounds to $0.00, the estimated costs are tied.
Mini-example
Suppose the Debt balance is $12,000, the Monthly budget for payoff is $1,000, the balance transfer has a 0% promo APR for 12 months, a 0% APR after the promo, and a 3% fee, and the personal loan has a 0% contract annual interest rate for 12 months with no origination fee. The balance transfer starts at $12,360 because of the $360 fee. After 12 payments of $1,000, $360 remains, so it takes 13 months and the Balance transfer total paid is $12,360. The personal loan payment is $1,000 for 12 months, so Personal loan total paid after fee is $12,000. The cost gap is $360, so Estimated savings from the cheaper option is $360.