
See if your car loan is upside down and estimate how a trade-in could change your next auto loan.
Table of contents
How to use our Upside Down Car Loan Calculator
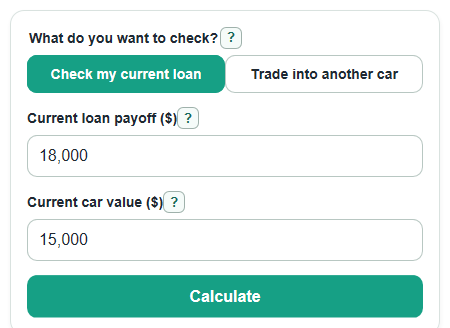
- Choose What do you want to check?: Check my current loan for a quick equity check, or Trade into another car for a new loan estimate.
- Enter Current loan payoff ($) and Current car value ($). Use a lender payoff quote and a realistic trade-in or sale value when you can.
- If you choose trade-in mode, enter New car price ($), Down payment on new car ($), New loan APR (percent), and New loan term (months).
- Open Advanced options if you want to add Cash paid toward old loan gap ($), Sales tax rate (percent), Dealer, title, and registration fees ($), or change How to estimate sales tax.
- Sanity-check the result: if New loan-to-value is over 100 percent or Old-loan gap rolled into new loan is high, compare paying more cash, lowering the new car price, or waiting before trading.
Definitions
Current loan payoff: The amount needed to fully pay off your current car loan today or by the payoff date.
Current car value: What the car is expected to bring as a trade-in or sale amount.
Upside down: A loan is upside down when the payoff is bigger than the car value, which is also called negative equity [1].
Negative equity: The dollar gap between the payoff and the car value when the payoff is higher.
Cash paid toward old loan gap: Cash used to reduce negative equity before any remaining gap is rolled into the new loan.
APR: Annual percentage rate, the yearly borrowing cost used in the payment estimate.
Loan term: The number of months used to repay the new loan.
Amount financed: The estimated starting balance of the new loan after price, tax, fees, down payment, trade equity, and rolled-in gap are applied.
Loan-to-value: The new loan amount compared with the new car price, shown as a percent.
Common mistakes and quick fixes
Mistake: Using the online balance instead of a payoff quote for Current loan payoff ($).
Fix: Ask the lender for the payoff amount if possible, because it may include interest through a payoff date.
Mistake: Entering an optimistic retail price for Current car value ($) when you plan to trade the car.
Fix: Use a realistic trade-in offer or dealer estimate so Upside-down amount is not understated.
Mistake: Putting Cash paid toward old loan gap ($) in Down payment on new car ($).
Fix: Use Cash paid toward old loan gap ($) only for cash that reduces the old negative equity, and use Down payment on new car ($) for cash toward the new purchase.
Mistake: Leaving New loan APR (percent) blank in trade mode or typing a percent sign that makes the entry invalid.
Fix: Enter a number such as 7.5, and use 0 only if the new loan truly has no interest.
Mistake: Choosing the wrong How to estimate sales tax setting for your deal.
Fix: Match your buyer's order or quote: tax the full price, tax price after trade-in value, or do not add sales tax.
Mistake: Comparing only Estimated new monthly payment and ignoring Extra paid over the new loan from rolled-in gap.
Fix: Check both the monthly change and the total extra cost before deciding to roll old debt into the new loan.
Limitations & Key Assumptions / Boundary Conditions
- The payment is an estimate for a fixed-rate loan with equal monthly payments. A lender's final contract can differ because of exact dates, add-ons, rules, or rounding.
- Sales tax is simplified. The calculator uses the How to estimate sales tax choice, but state rules and dealer paperwork may use a different taxable amount.
- Current car value is only as good as the estimate you enter. A real trade-in offer, private sale price, or damaged-vehicle adjustment can change the equity.
- Current loan payoff can change with interest, late fees, or payoff timing. Use a fresh payoff quote when making a real trade-in decision.
- Estimated new amount financed is floored at $0 because a loan cannot be negative. If your cash and trade equity more than cover the purchase, the extra is not modeled as cash back.
- The calculator does not include insurance, maintenance, warranties, early payoff fees, gap coverage, or future depreciation.
- New loan-to-value uses New car price ($) as the comparison base, so financed tax, fees, and old debt can push it above 100 percent.
Methodology
How the current loan check works
The calculator first compares Current car value ($) with Current loan payoff ($). It keeps the sign on Your current car equity because a negative number is the useful warning sign.
current_equity = current_car_value - current_loan_payoff
upside_down_amount = max(0, current_loan_payoff - current_car_value)
cash_to_break_even = upside_down_amount
If the payoff is $18,000 and the car value is $15,000, equity is $15,000 - $18,000 = -$3,000. The Upside-down amount and Cash needed to break even are both $3,000.
How the trade-in estimate works
In trade mode, positive trade equity reduces the new loan, while remaining negative equity increases it. If you enter Cash paid toward old loan gap ($), that cash reduces the old-loan gap before the rest is rolled into the new loan.
positive_trade_equity = max(0, current_car_value - current_loan_payoff)
remaining_gap_rolled_in = max(0, upside_down_amount - cash_paid_toward_gap)
Sales tax is estimated from the selected tax method. Full price uses the new car price. After trade-in uses the new car price minus the current car value, floored at $0. Do not add sales tax sets taxable price to $0.
sales_tax = taxable_price * sales_tax_rate / 100
amount_financed = max(0, new_car_price + sales_tax + dealer_and_title_fees - down_payment - positive_trade_equity + remaining_gap_rolled_in)
How the payment is estimated
The calculator converts New loan APR (percent) to a monthly rate by dividing by 100 and then by 12. Comparing amount financed, APR, term, and monthly payment gives a fuller loan picture than monthly payment alone [2].
monthly_rate = annual_apr / 100 / 12
if monthly_rate = 0, payment = amount_financed / loan_term_months
otherwise, payment = amount_financed * monthly_rate / (1 - (1 + monthly_rate)^(-loan_term_months))
For a trade-in example with a $30,000 new car, $2,000 down payment, a $3,000 old-loan gap, 7.5% APR, and 60 months, the estimated amount financed is $31,000 and the estimated payment is about $621.18 per month.
How the rolled-in gap cost is isolated
To show the cost of bringing old debt into the new loan, the calculator also estimates the payment without the remaining old-loan gap and subtracts that from the full payment.
base_amount = max(0, new_car_price + sales_tax + dealer_and_title_fees - down_payment - positive_trade_equity)
extra_monthly_from_gap = payment(amount_financed) - payment(base_amount)
extra_total_from_gap = extra_monthly_from_gap * loan_term_months
new_loan_to_value = amount_financed / new_car_price * 100
Using the same example, the $3,000 rolled-in gap adds about $60.11 per month and about $3,606.83 over 60 months. The New loan-to-value is about 103.33%, so the new loan starts higher than the new car price.
Sources
- Auto loans key terms | Consumer Financial Protection Bureau - Consumerfinance
- How do I compare auto loan offers? | Consumer Financial Protection Bureau - Consumerfinance
- FINRED (DoD) - Car Buying 101: When Your Trade-In Has Negative Equity (PDF) - Usalearning
- Is Your Car Loan Upside-Down? How to Handle Negative Equity - Nerdwallet