
Estimate your remaining car loan principal and see how payoff interest or fees can change the amount you may need to send.
Advanced options
Table of contents
How to use our Car Loan Balance Calculator
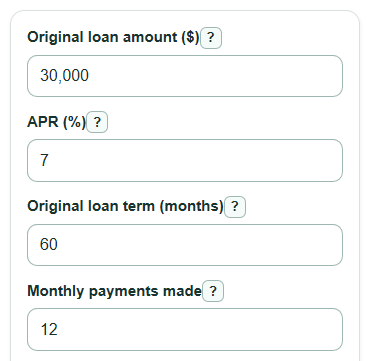
- Enter the Original loan amount ($), APR (%), Original loan term (months), and Monthly payments made from your loan paperwork or statement.
- Open Advanced options only if you need to match your statement with Use this monthly payment instead ($), include Extra principal already paid ($), or estimate payoff interest and a fee.
- Use Days of payoff interest for the number of days between your last payment and the payoff date, then choose Days in lender interest year only if your lender tells you to use 360 days instead of 365.
- Select Calculate, then compare Estimated principal balance with Estimated payoff amount; the payoff amount can be higher because it may include daily interest and a payoff fee.
- Sanity-check the result by comparing Calculated monthly payment with your statement payment and checking that Monthly payments made does not count skipped, late, or future payments.
Definitions
Original loan amount ($): The amount financed at the start of the auto loan, also called the original principal.
APR (%): Annual percentage rate. It is the yearly cost of borrowing shown as a percent, and it can include more than the simple interest rate [2].
Principal: The part of the loan amount you still owe, not counting future interest.
Estimated principal balance: The estimated unpaid principal right after the counted monthly payment is applied.
Estimated payoff amount: The estimated amount to pay off the loan on a payoff date, including principal, daily payoff interest, and any payoff fee you entered.
Calculated monthly payment: The payment from the fixed-rate loan formula unless you enter Use this monthly payment instead ($).
Extra principal already paid ($): Extra money already applied to reduce principal, separate from regular monthly payments.
Days in lender interest year: The day-count basis used for the daily interest estimate, either 365 or 360 days.
Common mistakes and quick fixes
Mistake: Using the car sticker price for Original loan amount ($) .
Fix: Enter the amount financed from the loan contract, after down payment, trade-in credit, taxes, and financed fees are handled.
Mistake: Leaving APR (%) blank because the loan has a 0% rate.
Fix: Enter 0 for a true 0% loan; a blank APR is not the same as zero.
Mistake: Putting years into Original loan term (months) .
Fix: Convert years to months, such as 5 years = 60 months.
Mistake: Counting planned future payments in Monthly payments made .
Fix: Count only regular monthly payments that have already posted to the loan.
Mistake: Using Extra principal already paid ($) for every regular payment you made.
Fix: Enter only extra principal payments above the regular monthly payment.
Mistake: Treating Estimated payoff amount as the lender's final payoff quote.
Fix: Use it as an estimate and request an official payoff quote when you are ready to pay the loan off.
Limitations & Key Assumptions / Boundary Conditions
- The calculator assumes a fixed-rate amortizing car loan with regular monthly payments.
- It does not know your lender's exact rounding rules, late fees, skipped payments, payment posting dates, or any add-on products that may change the real balance.
- Estimated principal balance is based on the number of regular payments made. If payments were missed, deferred, or paid on unusual dates, the real lender balance can differ.
- Estimated payoff amount is not an official payoff quote. Lenders can calculate payoff interest to a specific good-through date and may include fees or credits not entered here.
- Daily payoff interest is calculated only on a positive principal balance. If the balance is zero or negative, the daily interest part is treated as $0.
- If a custom payment is too small to cover monthly interest on a positive balance, the calculator should not estimate payoff months or future interest because the balance would not go down.
- A negative principal balance means the entered payments and extra principal imply the loan would have been paid off earlier or overpaid. It is a signal to check the inputs and your loan statement.
Methodology
How the balance is estimated
The calculator first converts APR to a monthly rate, then finds the normal fixed monthly payment unless you entered Use this monthly payment instead ($). In an amortizing auto loan, each monthly payment is split between interest and principal [2].
monthly_rate = APR (%) / 100 / 12
if monthly_rate = 0: calculated_monthly_payment = Original loan amount ($) / Original loan term (months)
otherwise: calculated_monthly_payment = loan_amount * monthly_rate * (1 + monthly_rate)^term_months / ((1 + monthly_rate)^term_months - 1)
The payment used is the calculated payment unless the optional custom payment is entered. The calculator then estimates the loan balance after the number of regular monthly payments made.
if monthly_rate = 0: balance_before_extra = loan_amount - payment_used * payments_made
otherwise: balance_before_extra = loan_amount * (1 + monthly_rate)^payments_made - payment_used * (((1 + monthly_rate)^payments_made - 1) / monthly_rate)
Estimated principal balance = balance_before_extra - Extra principal already paid ($)
How payoff amount is estimated
Payoff interest is estimated with simple daily interest from the positive principal balance only. Then any payoff fee is added.
daily_interest = max(Estimated principal balance, 0) * APR (%) / 100 / Days in lender interest year * Days of payoff interest
Estimated payoff amount = Estimated principal balance + daily_interest + Payoff fee ($)
Other outputs
The paid-off percent compares the estimated current principal balance with the original loan amount. It can be above 100% if the entries imply overpayment.
Loan paid off (%) = (Original loan amount ($) - Estimated principal balance) / Original loan amount ($) * 100
Past interest is estimated from regular payments only, so extra principal does not count as interest paid.
regular_principal_paid = Original loan amount ($) - balance_before_extra
Estimated interest paid so far = payment_used * Monthly payments made - regular_principal_paid
For Months left at this payment and Estimated interest left, the calculator steps forward one month at a time. Each month it adds interest, subtracts the payment, and stops when the balance is within half a cent of zero.
interest = current_balance * monthly_rate
payment_this_month = min(payment_used, current_balance + interest)
new_balance = current_balance + interest - payment_this_month
Mini-example
For a $30,000 loan at 7% APR over 60 months with 12 payments made and no extra principal, the calculated monthly payment is about $594.04. The estimated principal balance is about $24,807.06. With 10 days of payoff interest on a 365-day basis and no fee, the estimated payoff amount is about $24,854.64.