
Estimate a home improvement loan payment, total interest, fees, and the cash left for your renovation.
Table of contents
How to use our Home Improvement Loan Calculator
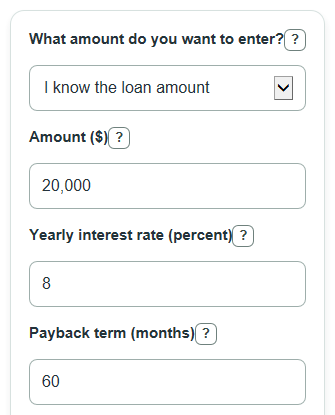
- Choose What amount do you want to enter?: pick I know the loan amount if you already know what you plan to borrow, or I need this much for the project if you want enough cash left after deducted fees.
- Enter Amount, Yearly interest rate, and Payback term. Use months for the term, such as 60 for a 5-year loan.
- Open Advanced options if the loan has a Loan fee, Fixed loan fees, or a fee timing choice under How are fees paid?.
- Select Calculate, then compare Estimated monthly payment with your budget and Cash available for the project after fees with your renovation cost.
- Sanity-check the output: if fees are taken from the loan, Estimated loan fees should reduce project cash or make the Estimated loan amount to request higher in project cash mode.
Definitions
Estimated loan amount to request: The principal used for payment math. Principal is the borrowed amount that the payment is based on.
Estimated monthly payment: The fixed principal-and-interest payment estimated for each month. It does not include insurance, taxes, or other non-loan bills.
Cash available for the project after fees: The loan cash left for the renovation after fees that are taken from the loan.
Loan fee: A percent-based charge, often called an origination fee, calculated from the loan amount.
Fixed loan fees: One-time dollar fees that do not change when the percent fee changes.
Yearly interest rate: The annual rate used to calculate interest on the loan balance. APR can include some fees, so it may differ from the interest rate [1].
Common mistakes and quick fixes
Mistake: Entering the contractor quote in Amount while What amount do you want to enter? is set to I know the loan amount.
Fix: If you need that much cash after deducted fees, change What amount do you want to enter? to I need this much for the project.
Mistake: Typing an APR with fees included into Yearly interest rate and also entering the same fees under Loan fee or Fixed loan fees.
Fix: For a planning estimate, use the loan's interest rate in Yearly interest rate and enter fees once in Loan fee or Fixed loan fees.
Mistake: Entering years in Payback term instead of months.
Fix: Convert years to months before using Payback term, such as 5 years as 60 months.
Mistake: Choosing Paid separately at closing in How are fees paid? when the lender deducts fees from the loan proceeds.
Fix: Set How are fees paid? to Taken from the loan so Cash available for the project after fees reflects the deduction.
Mistake: Reading Total paid over loan plus upfront fees as the amount available for the renovation.
Fix: Use Cash available for the project after fees for renovation cash, and use Total paid over loan plus upfront fees for the broad loan cost.
Limitations & Key Assumptions / Boundary Conditions
- This is a planning estimate for a fixed-rate installment loan with equal monthly payments.
- The calculator does not model HELOC draw periods, variable rates, skipped payments, late fees, prepayment penalties, or changing payment dates.
- Fees are treated as either taken from the loan or paid separately at closing. A real lender may use different fee rules.
- The payment estimate uses the entered Yearly interest rate. If you enter APR and also enter the same fees, the loan cost can be overstated.
- Cash available for the project after fees can be negative when fees taken from the loan are larger than the loan amount. The calculator shows that instead of forcing it to $0.
- Taxes, permits, contractor change orders, and project overruns are not included unless you add them to Amount.
Methodology
Core loan payment math
The calculator treats the home improvement loan as a fixed-payment loan. A fixed-payment loan can be calculated with the same present-value annuity relationship used for loans with equal payments over time. The principal-and-interest payment is separate from other possible costs, such as fees paid outside the loan [2].
monthly_rate = Yearly interest rate / 100 / 12
Estimated monthly payment = principal * monthly_rate / (1 - (1 + monthly_rate)^(-Payback term))
If the Yearly interest rate is 0, the payment is simple division.
Estimated monthly payment = principal / Payback term
How fees change project cash
If What amount do you want to enter? is I know the loan amount, the principal is the Amount you entered.
principal = Amount
If What amount do you want to enter? is I need this much for the project and How are fees paid? is Taken from the loan, the calculator raises the requested loan amount so the cash left after fees matches the project cash goal.
Estimated loan amount to request = (Amount + Fixed loan fees) / (1 - Loan fee / 100)
Estimated loan fees are calculated from the loan amount used for payment math, plus any fixed dollar fees.
Estimated loan fees = principal * (Loan fee / 100) + Fixed loan fees
Cash available depends on how fees are paid.
Cash available for the project after fees = principal - Estimated loan fees when fees are taken from the loan
Cash available for the project after fees = principal when fees are paid separately at closing
Total cost math
Total interest is the sum of all monthly payments minus the principal. Total paid over loan plus upfront fees adds fees only when they are paid separately at closing.
Total interest paid = Estimated monthly payment * Payback term - principal
Total paid over loan plus upfront fees = Estimated monthly payment * Payback term + upfront fees
Mini-example
Suppose you need $20,000 for the project, the Yearly interest rate is 8%, the Payback term is 60 months, the Loan fee is 5%, Fixed loan fees are $300, and fees are Taken from the loan. The request is grossed up to about $21,368.42. Estimated loan fees are about $1,368.42, leaving $20,000 for the project. The estimated monthly payment is about $433.27, total interest is about $4,628.04, and total paid over the loan is about $25,996.46.