
Enter your original loan details and payments made to estimate the principal balance you still owe.
Table of contents
How to use our Loan Balance Calculator
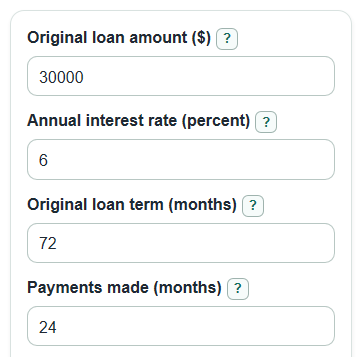
- Enter the Original loan amount ($), which is the amount first borrowed, not your current balance.
- Enter the Annual interest rate (percent), Original loan term (months), and Payments made (months) from your loan records.
- If your statement shows a steady payment that differs from the formula payment, enter it in Actual monthly payment ($, optional); otherwise leave that field blank.
- Click Calculate and read Remaining balance first, then compare Calculated scheduled payment with Monthly payment used.
- Sanity-check the result: Principal paid so far plus Remaining balance should equal the original loan amount, except for rounding by cents.
Definitions
Remaining balance: The estimated principal still owed right after the completed payments.
Principal: The borrowed amount that has not been paid back yet, before any future interest.
Annual interest rate (percent): The yearly loan rate entered as a percent, such as 6 for 6 percent.
Monthly rate: The annual interest rate divided by 12 months and converted to a decimal for monthly loan math.
Calculated scheduled payment: The fixed monthly principal-and-interest payment based on the original amount, rate, and term.
Monthly payment used: The payment used in the balance calculation. It is the actual monthly payment if entered, otherwise the calculated scheduled payment.
Payments left at this payment: The estimated number of additional monthly payments needed if the same payment continues and the rate does not change.
Common mistakes and quick fixes
Mistake: Entering the current balance in Original loan amount ($) .
Fix: Use the amount borrowed at the start of the loan so Remaining balance is calculated from the full amortization path.
Mistake: Typing 0.06 in Annual interest rate (percent) for a 6 percent loan.
Fix: Enter 6, because the label asks for a percent, not a decimal rate.
Mistake: Entering years in Original loan term (months) .
Fix: Convert years to months first; for example, a 5-year loan is 60 months.
Mistake: Counting future or planned payments in Payments made (months) .
Fix: Count only completed monthly payments; the Remaining balance is right after that many payments.
Mistake: Filling Actual monthly payment ($, optional) with a one-time extra payment or an irregular amount.
Fix: Use this field only for a steady monthly payment; leave it blank if you want the Calculated scheduled payment used.
Mistake: Reading Interest paid so far as money that reduced the loan.
Fix: Use Principal paid so far to see the part that lowered the balance; interest is the borrowing cost.
Limitations & Key Assumptions / Boundary Conditions
- This calculator assumes a fixed-rate loan with monthly payments and a steady payment amount.
- It does not include variable rates, skipped payments, late fees, escrow, insurance, taxes, refinance charges, or one-time extra payments.
- Actual monthly payment ($, optional) is treated as the same payment every month. If your payment changed over time, the estimate may not match your lender statement.
- The displayed Remaining balance is floored at $0 because a loan cannot have negative principal after payoff.
- Real payoff quotes can differ because lenders may use daily interest, statement cutoff dates, payoff fees, or exact cents rounding.
- If Payments made (months) is greater than the original term, the calculator can still compute a result, but a warning means the loan would normally be finished unless payments were missed or changed.
Methodology
How the balance is calculated
The calculator first converts the yearly rate to a monthly rate because the loan is paid monthly.
r = annual_interest_rate / 100 / 12
It then calculates the standard fixed monthly payment for the original loan amount, interest rate, and term. This is the payment shown as Calculated scheduled payment. The same fixed-payment structure is commonly used for installment loan balance formulas [1].
A_scheduled = P * r * (1 + r)^n / ((1 + r)^n - 1)
If r = 0, A_scheduled = P / n
If Actual monthly payment ($, optional) is filled in, that value becomes the payment used. If it is blank, the scheduled payment is used.
A = actual_monthly_payment if entered; otherwise A = A_scheduled
The balance is then stepped forward one month at a time. Each month adds interest to the current balance, then subtracts the payment. This loop is used instead of only a closed-form shortcut so early payoff can be handled when the actual payment is higher.
interest = balance * r
new_balance = balance + interest - payment
If the payment pays off the loan during the counted months, the final displayed balance is $0 and only the needed final payment is counted for interest-paid math. The standard remaining-balance formula also describes outstanding principal after a set number of monthly payments on an amortizing loan [2].
Other outputs
Principal paid is the original loan amount minus the remaining balance. Interest paid so far is the total payment amount actually applied minus the principal paid.
principal_paid = P - remaining_balance
interest_paid_to_date = payments_applied - principal_paid
The next payment split estimates how much of the next payment would go to interest first, then principal.
next_payment_interest = remaining_balance * r
next_payment_principal = min(A - next_payment_interest, remaining_balance)
If the payment is large enough to pay down principal, payments left is computed from the fixed-payment payoff formula. If the payment does not cover monthly interest, payoff cannot be reached with that payment.
If r = 0, payments_left = ceil(remaining_balance / A)
If r > 0, payments_left = ceil(-ln(1 - r * remaining_balance / A) / ln(1 + r))
Loan paid off is the paid principal divided by the original loan amount, displayed from 0 percent to 100 percent.
loan_paid_percent = clamp((principal_paid / P) * 100, 0, 100)
Mini example
For a $30,000 loan at 6 percent for 72 months with 24 payments made and no actual payment entered, the scheduled payment is about $497.19. After 24 payments, the estimated remaining balance is about $21,170.36, principal paid is about $8,829.64, and interest paid so far is about $3,102.84. The next payment would include about $105.85 of interest and about $391.33 of principal.