
Estimate your current HELOC interest-only payment and the later payment when repayment starts.
Advanced options
Table of contents
How to use our HELOC Interest-Only Payment Calculator
- Enter your Current HELOC balance ($), which is the amount borrowed, not the full credit line unless you used it all.
- Enter the Draw-period APR (%), Months left in draw period, Repayment APR (%), and Repayment term (years).
- Open Advanced options only if you plan to add Extra principal paid each month during draw ($) or a One-time paydown before repayment ($).
- Click Calculate and compare Interest-only payment this month with Estimated repayment payment later and Monthly payment change.
- Sanity-check the result: if the future payment looks too low, make sure Repayment term (years) is not too long and Current HELOC balance ($) is not your credit limit by mistake.
Definitions
HELOC: A home equity line of credit. It lets a homeowner borrow against home equity up to a credit limit.
Current HELOC balance ($): The amount you have already borrowed and still owe.
Draw period: The time when you can borrow from the line of credit. Some HELOCs require interest-only payments during this time.
Repayment period: The time after the draw period when new borrowing stops and the balance is paid back, often with principal plus interest payments [1].
APR: Annual percentage rate. This calculator divides the yearly APR by 12 to estimate a monthly rate.
Principal: The borrowed balance, not including interest.
Amortizing payment: A payment that includes interest and enough principal to pay the balance to $0 by the end of the repayment term.
Common mistakes and quick fixes
Mistake: Entering the full line of credit in Current HELOC balance ($) when you have borrowed less.
Fix: Enter only the amount currently borrowed.
Mistake: Leaving Draw-period APR (%) or Repayment APR (%) blank because the rate is unknown.
Fix: Enter your best rate estimate, or enter 0 only if the rate is truly 0%.
Mistake: Using years in Months left in draw period.
Fix: Convert the time left to months, such as 10 years = 120 months.
Mistake: Putting the draw period length in Repayment term (years).
Fix: Enter the number of years used to repay the balance after the draw period ends.
Mistake: Adding normal interest-only payments to Extra principal paid each month during draw ($).
Fix: Enter only the extra principal amount paid above the interest-only payment.
Mistake: Reading Monthly payment change percent as an interest rate.
Fix: Treat it as the percent change from Interest-only payment this month to Estimated repayment payment later.
Limitations & Key Assumptions / Boundary Conditions
- The estimate uses the APR values you enter. Many HELOCs have variable rates, so real payments can change if rates change.
- The calculator assumes no future draws, no new fees, no late charges, and no changes to the payment schedule.
- Interest during the draw period is estimated monthly. Actual lenders may use daily interest or a different billing cycle.
- Extra principal paid each month during draw ($) is applied after that month's interest is estimated.
- One-time paydown before repayment ($) is applied after the remaining draw period projection and is capped at the remaining balance.
- If the balance is paid off before repayment starts, the Estimated repayment payment later is $0.
- This is a planning estimate, not a payoff quote or a lender-approved payment schedule.
Methodology
How the calculator works
The calculator first estimates the current interest-only payment from the Current HELOC balance ($) and Draw-period APR (%). Then it projects the balance through the remaining draw period. After the draw period, many HELOCs move from interest-only payments to repayment of principal plus interest, which can cause a higher monthly payment [1].
interest_only_payment = current_balance * (draw_apr / 100 / 12)
For each remaining draw month, interest is added to the draw-period interest total, then any extra monthly principal paydown reduces the balance.
monthly_interest = balance * (draw_apr / 100 / 12)
draw_period_interest = draw_period_interest + monthly_interest
principal_paid = min(extra_principal_monthly, balance)
balance = balance - principal_paid
After the last draw month, the one-time paydown is applied, but not below $0.
balance_at_repayment_start = max(0, balance - one_time_paydown_before_repayment)
The repayment payment uses the standard fixed-payment loan formula when the Repayment APR (%) is greater than 0.
repayment_monthly_payment = balance_at_repayment_start * repayment_monthly_rate / (1 - (1 + repayment_monthly_rate)^(-repayment_months))
repayment_monthly_rate = repayment_apr / 100 / 12
repayment_months = repayment_term_years * 12
If the Repayment APR (%) is 0, the calculator uses straight-line principal repayment.
repayment_monthly_payment = balance_at_repayment_start / repayment_months
Repayment interest and total estimated interest are then calculated from the projected repayment payment.
repayment_interest = repayment_monthly_payment * repayment_months - balance_at_repayment_start
payment_increase_amount = repayment_monthly_payment - interest_only_payment
payment_increase_percent = payment_increase_amount / interest_only_payment * 100
total_estimated_interest = draw_period_interest + repayment_interest
Mini-example
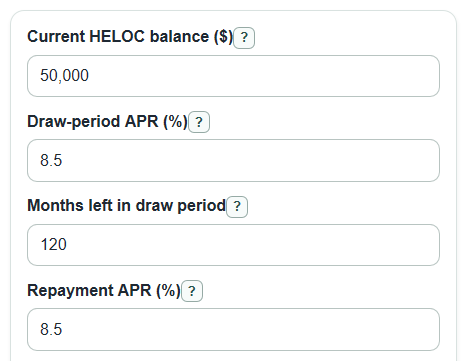
With a $50,000 Current HELOC balance ($), 8.5% Draw-period APR (%), 120 Months left in draw period, 8.5% Repayment APR (%), and a 20-year Repayment term (years), the interest-only payment is about $354.17 per month. With no extra paydown, the estimated later repayment payment is about $433.91 per month. The monthly payment change is about $79.74, or 22.52%, and total estimated interest from now is about $96,638.79.