
Estimate your HELOC payoff time, interest cost, goal payment, and possible payment jump after the draw period ends.
Table of contents
How to use our HELOC Payoff Calculator
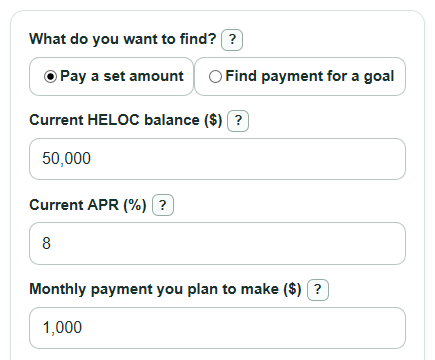
- Choose What do you want to find?: use Pay a set amount if you know your monthly payment, or Find payment for a goal if you want a target payoff plan.
- Enter Current HELOC balance, Current APR, and Months left before repayment starts from your latest statement or loan documents.
- Enter Monthly payment you plan to make or Payoff goal, depending on the mode you chose.
- Open Advanced options if you need to change Repayment period, APR after draw period, Monthly account charges, or Annual fee.
- Click Calculate, then sanity-check Estimated payoff time and Balance when repayment starts; if they look far from your statement, recheck APR, months, and whether your payment is total monthly payment or extra payment.
Definitions
HELOC: A home equity line of credit, which is a revolving loan secured by your home.
Current HELOC balance: The amount you owe right now, not the total line of credit.
Current APR: The annual percentage rate used to estimate monthly interest before repayment starts.
Draw period: The first phase of many HELOCs, when borrowing may still be allowed and payments may be interest-only.
Repayment period: The later phase when the remaining balance is usually paid back with principal and interest payments.
Minimum-payment path: The comparison path that pays interest only during the remaining draw period, then pays the estimated required repayment amount over the full Repayment period.
Interest cut versus minimum path: Estimated interest avoided compared with the minimum-payment path. A positive number means your plan costs less interest.
Common mistakes and quick fixes
Mistake: Entering the full credit limit in Current HELOC balance.
Fix: Use only the amount you owe now in Current HELOC balance.
Mistake: Leaving Current APR blank because the rate might change later.
Fix: Enter the current statement rate in Current APR, and use APR after draw period only if you want to test a different later rate.
Mistake: Putting only the extra amount in Monthly payment you plan to make.
Fix: Enter the full monthly HELOC payment you plan to send, including any regular principal payment.
Mistake: Using the original draw-period length for Months left before repayment starts.
Fix: Enter the number of months still remaining before repayment starts, not the number from the day the HELOC opened.
Mistake: Setting Repayment period to 0 when a balance could remain after the draw period.
Fix: Enter the lender's repayment length in Repayment period, such as 120, 180, or 240 months.
Mistake: Treating Fees and account charges as principal payments.
Fix: Put fees in Monthly account charges or Annual fee; the calculator shows Fees and account charges separately because they do not lower the loan balance.
Limitations & Key Assumptions / Boundary Conditions
- The calculator uses monthly compounding. Some HELOCs calculate interest daily, so real statement interest can differ.
- APR is treated as fixed within each phase. A variable-rate HELOC can change after the date you calculate.
- The model does not include new draws, missed payments, late fees, rate caps, promotional rates, escrow, taxes, or insurance.
- Monthly account charges and Annual fee are counted as out-of-pocket costs, but they do not reduce Current HELOC balance.
- The estimated repayment payment is based on a standard fixed-payment formula. Your lender's required payment can use different rounding, timing, or contract rules.
- If your planned payment is below interest due or below the estimated repayment minimum, the calculator raises the payment to a feasible minimum instead of letting the balance grow forever.
- Results are estimates for planning. Use your HELOC agreement or lender statement for the payment you are legally required to make.
Methodology
Monthly rate and interest
The calculator converts each APR to a monthly rate by dividing by 12. It uses Current APR during the remaining draw period. If APR after draw period is entered, that rate is used after repayment starts; otherwise the Current APR continues.
monthly_rate = apr_percent / 100 / 12
interest = balance_start_of_month * monthly_rate
Balance update
Each simulated month starts with the current balance, adds the month's interest for payoff math, and applies the feasible loan payment. Optional fees are not counted as loan payments.
principal_paid = min(balance_start, max(0, loan_payment - interest))
balance_end = balance_start - principal_paid
If the final regular payment would be larger than the remaining balance plus interest, the payoff month still counts, but the final loan payment is only the amount needed to finish.
Draw period and repayment period
During the draw period, the feasible minimum is the interest due for that month. If a balance remains when repayment starts, the calculator carries that balance into the repayment phase instead of forcing payoff by the draw-period end.
At repayment start, it estimates the required principal-and-interest payment over Repayment period.
if monthly_rate = 0, payment = balance / months
otherwise, payment = balance * monthly_rate / (1 - (1 + monthly_rate)^(-months))
In Pay a set amount mode, the actual loan payment is the larger of your planned payment and the phase minimum.
during_draw: actual_payment = max(planned_payment, interest_due)
during_repayment: actual_payment = max(planned_payment, required_repayment_payment)
Goal mode and comparison path
In Find payment for a goal mode, the calculator searches for the smallest planned monthly payment that pays the balance off by Payoff goal. It uses the same draw-period and repayment-period rules as set-payment mode.
monthly_payment_for_goal = smallest planned_payment where payoff_months <= target_months
The minimum-payment comparison pays interest only during the remaining draw period, then pays the amortizing repayment payment over Repayment period. Interest savings is the comparison interest minus the plan interest.
interest_cut_vs_minimum = minimum_path_interest - plan_interest
Fees and charges
Monthly account charges and Annual fee are estimated through the payoff month and shown separately from interest.
total_fees_and_charges = payoff_months * monthly_account_charges + payoff_months * annual_fee / 12
Worked mini-example
For a $50,000 Current HELOC balance, 8% Current APR, $1,000 Monthly payment you plan to make, 60 Months left before repayment starts, and a 240-month Repayment period, the estimate is about 62 months to pay off. Interest is about $11,022.35. The balance at the start of repayment is about $1,015.43, so the estimated required repayment payment at that point is only about $8.49 per month, and the $1,000 planned payment finishes the HELOC shortly after the draw period.