
Enter one loan amount and both quoted rates to compare the monthly principal-and-interest payment and total interest for 15-year and 30-year mortgages.
Required principal and interest only. Taxes, insurance, mortgage insurance, and HOA charges are not included.
This is the scheduled principal-and-interest payment for the 30-year loan.
This is a voluntary extra-payment plan, not the required 30-year payment.
Each month's interest is rounded to cents, and the last payment is reduced when needed.
Calculation details
Table of contents
How to use our 15 vs 30 Year Mortgage Calculator
- Enter the amount you will borrow in "Loan amount ($)." Use the loan balance, not the home's purchase price.
- Copy the annual note interest rate from each lender quote into "15-year interest rate (annual %)" and "30-year interest rate (annual %)." Do not use APR.
- Select "Calculate" to see how much more or less the 15-year loan requires each month for principal and interest.
- Compare each loan's scheduled interest, then review the 30-year payoff time if you voluntarily pay the calculated 15-year payment.
- Sanity-check that both results use the same loan amount and that the payment you prefer still leaves room for taxes, insurance, repairs, and other monthly costs.
Definitions
Loan amount: The principal, meaning the original amount borrowed. It is not the home's purchase price.
Annual note interest rate: The yearly rate charged on the unpaid loan balance. The calculator converts it to a monthly rate for payment math.
APR: Annual percentage rate. For a mortgage, APR includes the interest rate and certain loan costs, so it can differ from the note rate used in the payment calculation. [1]
Principal and interest (P&I): The part of a mortgage payment that repays the borrowed balance and interest. It does not include taxes, insurance, or other possible housing charges. [2]
Amortization: The process of paying off a loan with scheduled payments over time. Earlier payments usually put more toward interest, while later payments put more toward principal.
Total scheduled interest: All scheduled principal-and-interest payments minus the original loan amount, assuming the loan is paid for its full term.
Common mistakes and quick fixes
Mistake: Entering the home's purchase price as the loan amount.
Fix: Enter the amount borrowed after your down payment. Check a lender quote, preapproval, or Loan Estimate.
Mistake: Entering APR instead of the annual note interest rate.
Fix: Copy the interest rate for each loan. APR can include certain loan costs and does not directly produce the scheduled payment used here.
Mistake: Assuming both loan terms have the same rate.
Fix: Enter each lender quote separately. A 15-year and 30-year mortgage can have different annual interest rates.
Mistake: Treating principal and interest as your complete housing payment.
Fix: Budget separately for property taxes, homeowners insurance, mortgage insurance, HOA charges, and maintenance when they apply.
Mistake: Thinking the 15-year payment is required after choosing a 30-year loan.
Fix: The 30-year loan has its own required payment. Paying the 15-year amount is a voluntary extra-payment plan.
Limitations & Key Assumptions / Boundary Conditions
- Results estimate fixed monthly principal-and-interest payments for 180 payments on the 15-year loan and 360 payments on the 30-year loan.
- The calculator excludes property taxes, homeowners insurance, mortgage insurance, HOA charges, lender fees, points, closing costs, and escrow deposits.
- It assumes each entered annual interest rate remains fixed for the whole loan term and that payments are made on time.
- The faster 30-year plan assumes you voluntarily pay the calculated 15-year principal-and-interest amount every month; your servicer's extra-payment process can affect a real payoff schedule.
- The faster-payoff schedule rounds monthly interest to cents, so its interest total can differ slightly from a lender's amortization schedule.
- Results compare loan payment mechanics only. They do not determine approval, affordability, taxes, refinancing results, or future home value.
Methodology
Payment calculation
The calculator uses the same loan amount for both choices and a separate annual note interest rate for each lender quote. It divides each annual percentage rate by 1,200 to get the monthly decimal rate.
monthly rate = annual interest rate / 1,200
For a rate above 0%, the scheduled payment follows the fixed-payment amortization equation. The 15-year loan uses 180 monthly payments, and the 30-year loan uses 360.
payment = loan amount * monthly rate / (1 - (1 + monthly rate)^(-number of payments))
For a 0% rate, payment equals the loan amount divided by the number of payments. Total scheduled interest equals all scheduled payments minus the original loan amount.
total scheduled interest = payment * number of payments - loan amount
The first result is the 15-year payment minus the 30-year payment. A positive result means the 15-year loan requires more principal and interest each month.
extra monthly P&I = 15-year payment - 30-year payment
Faster 30-year plan
For the voluntary faster-payoff plan, the calculator starts with the 30-year loan balance and applies the calculated 15-year payment each month. It rounds each month's interest to cents and reduces the final payment when needed so the balance does not go below zero. The plan is unavailable if the payment cannot cover the first month's interest.
monthly interest = round to cents(balance * 30-year monthly rate)
new balance = balance + monthly interest - payment
Worked mini-example
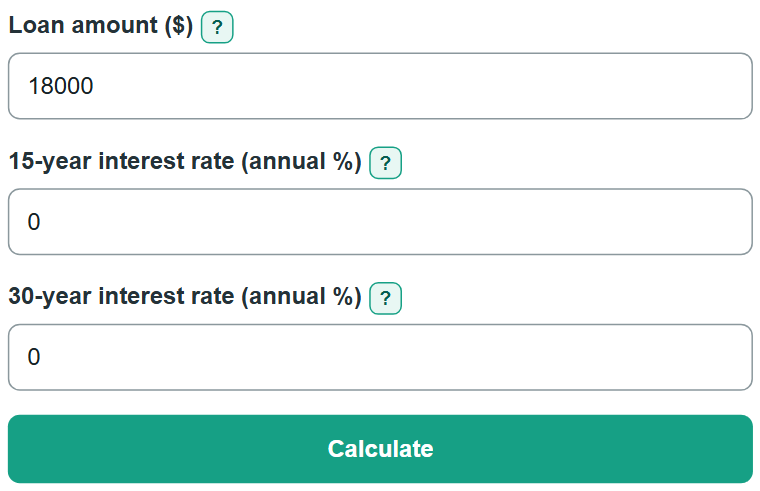
For an $18,000 loan at 0% for both terms, the 15-year payment is $100 per month and the 30-year payment is $50 per month. The 15-year loan requires $50 more each month, both loans have $0 scheduled interest, and paying $100 per month on the 30-year balance pays it off in 180 months.
Calculation limits
The payment formula estimates principal and interest only. Real monthly housing costs can also include taxes, insurance, mortgage insurance, HOA charges, and other costs. Lender schedules can differ slightly because of payment dates and rounding methods.