
Estimate a mortgage prepayment penalty using your loan balance, planned prepayment, clause method, trigger rule, and any no-fee amount.
Advanced options
Table of contents
How to use our Mortgage Prepayment Penalty Calculator
- Enter your Current mortgage balance and Amount you plan to prepay from your payoff quote, statement, or loan papers.
- Choose the Penalty method in your loan papers, then fill in Penalty percent or Mortgage interest rate and Months of interest charged as needed.
- Open Advanced options if your clause has a trigger rule, an allowed no-fee prepayment, or a penalty window that may have ended.
- Click Calculate and compare Estimated prepayment penalty, Does the trigger match?, and Method used with the exact wording in your Note, Addendum, or payoff quote.
- Sanity-check the result: if you are selling but the rule says refinance only, or if Months left in penalty window is 0, the penalty should show as $0.
Definitions
Prepayment penalty: A fee a lender may charge when a borrower pays down or pays off a mortgage early, if the mortgage contract allows it [2].
Current mortgage balance: The unpaid principal still owed on the mortgage. It is not the original loan amount and does not include escrow or future interest.
Amount you plan to prepay: The early principal payment you plan to make. For a full payoff, this is usually the current principal balance.
Penalty method in your loan papers: The rule your note or rider uses to calculate the fee, such as a percent of the prepaid amount, a percent of the current balance, or a set number of months of interest.
Penalty percent: The fee rate written in the penalty clause. Enter 2 for 2 percent.
Months of interest charged: The number of monthly interest charges used as the fee, such as 3 months or 6 months of interest.
When the penalty applies: The trigger rule in the clause. A hard-style rule can apply to sale, refinance, or large extra payment. A refinance-only rule is narrower.
Allowed no-fee prepayment: The part of the planned prepayment that your loan lets you make without a penalty.
Months left in penalty window: The time still left before the prepayment penalty period ends. If this is 0, this calculator treats the penalty as expired.
Common mistakes and quick fixes
Mistake: Using the original loan amount for Current mortgage balance.
Fix: Use the unpaid principal balance from your latest statement or payoff quote.
Mistake: Entering a full payoff in Amount you plan to prepay that is higher than Current mortgage balance.
Fix: Enter the best payoff principal amount you have; the calculator caps the prepayment at Current mortgage balance for the estimate.
Mistake: Choosing Percent of current balance for Penalty method in your loan papers when the clause says the fee applies only to the prepaid amount.
Fix: Choose Percent of prepaid amount unless your loan papers clearly say the fee is based on Current mortgage balance.
Mistake: Putting your Mortgage interest rate in Penalty percent.
Fix: Use Penalty percent only for a percent-fee clause, and use Mortgage interest rate with Months of interest charged for a months-of-interest clause.
Mistake: Ignoring When the penalty applies when your clause is refinance only.
Fix: Set When the penalty applies and What you are doing so Does the trigger match? can show whether the fee appears to apply.
Mistake: Leaving Allowed no-fee prepayment at $0 when your note lets you prepay part of the loan without a fee.
Fix: Enter the allowed dollar amount so Amount the fee is based on is reduced before the fee is calculated.
Limitations & Key Assumptions / Boundary Conditions
- The estimate depends on the wording you enter from your loan papers. Your lender's payoff quote controls the final payoff amount.
- The calculator does not decide whether a prepayment penalty is legal, enforceable, capped by law, or allowed for your loan type.
- Cash needed includes the capped principal prepayment plus the estimated penalty only. It excludes regular interest due, escrow changes, recording fees, release fees, payoff quote fees, and other lender adjustments.
- For Percent of current balance, the calculator uses Current mortgage balance as the penalty base and does not subtract Allowed no-fee prepayment. Verify this matches your clause.
- For Percent of prepaid amount and Months of interest charged, Allowed no-fee prepayment is subtracted from the capped prepayment before the fee is calculated.
- If Amount you plan to prepay is higher than Current mortgage balance, the calculator uses Current mortgage balance as the maximum principal prepayment.
- If the clause has minimum fees, maximum caps, step-down percentages, partial-year rules, or special sale exceptions, those details are not modeled here.
Methodology
How the estimate is built
The calculator first caps the planned prepayment at the unpaid balance, because a principal prepayment cannot be larger than the current principal balance.
prepay_capped = min(prepayment_amount, current_balance)
Next it checks whether the penalty appears to apply. The trigger applies only when the penalty window still has time left and the selected action matches the rule.
trigger_applies = months_left_in_penalty_window > 0 and (trigger_rule = any_action or action_type = refinance)
If the trigger does not apply, Estimated prepayment penalty is $0 and Amount the fee is based on is $0. If the trigger applies, the calculator chooses the base amount from the selected penalty method.
penalty_base = max(0, prepay_capped - free_prepay_amount)
This base is used for Percent of prepaid amount and Months of interest charged. For Percent of current balance, the base is the full Current mortgage balance.
penalty_base = current_balance
For a percent-fee clause, the penalty is the base amount multiplied by Penalty percent.
estimated_penalty = penalty_base * (penalty_percent / 100)
For a months-of-interest clause, the annual Mortgage interest rate is divided by 12 to get a monthly rate, then multiplied by Months of interest charged.
estimated_penalty = penalty_base * (annual_interest_rate / 100) / 12 * months_of_interest
Prepayment plus penalty is the capped principal prepayment plus the estimated fee.
cash_needed = prepay_capped + estimated_penalty
Mini example
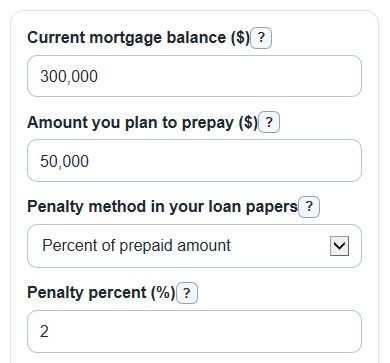
Suppose Current mortgage balance is $300,000, Amount you plan to prepay is $50,000, Penalty method in your loan papers is Percent of prepaid amount, Penalty percent is 2%, and Allowed no-fee prepayment is $10,000. The capped prepayment is $50,000. The penalty base is $50,000 - $10,000 = $40,000. The Estimated prepayment penalty is $40,000 * 0.02 = $800. Prepayment plus penalty is $50,000 + $800 = $50,800.
How to read the result
Estimated prepayment penalty is the main fee estimate. Amount the fee is based on shows the dollar amount used in the formula after the trigger and no-fee checks. Does the trigger match? explains why the fee is charged or why it is $0. Method used gives a plain-language formula summary so you can compare it with your loan papers.