
Estimate the fee, interest, total cost, and payoff timing impact for a credit card cash advance.
Advanced options
Table of contents
How to use our Credit Card Cash Advance Calculator
- Enter the Cash advance amount ($), which is only the cash you plan to take out.
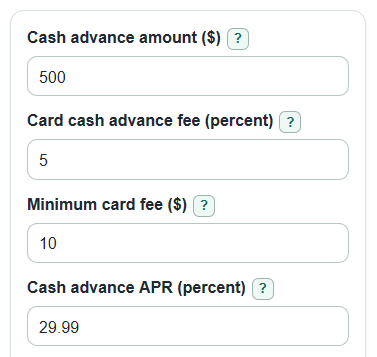
- Enter the Card cash advance fee (percent), Minimum card fee ($), Cash advance APR (percent), and Days until you pay it back from your card terms.
- Open Advanced options only if you have an Extra ATM or bank fee ($) or need to change What balance should earn interest?
- Click Calculate and read Total cost of the cash advance first, then Total amount to repay and the 7-day timing check.
- Sanity-check the output: if Card cash advance fee equals the Minimum card fee ($), your percent fee was lower than the flat minimum; if Interest through payoff day seems high, recheck Cash advance APR (percent) and Days until you pay it back.
Definitions
Cash advance amount ($): The cash you receive from the credit card cash advance, before card fees, ATM fees, and interest.
Card cash advance fee (percent): The issuer fee rate charged as a percent of the cash advance amount.
Minimum card fee ($): The smallest issuer fee the card can charge for the cash advance, even when the percent fee is lower.
Cash advance APR (percent): The annual percentage rate used for cash advance interest, not the purchase APR.
Interest balance: The dollar amount used to calculate daily interest. Depending on your card terms, it may be cash only, cash plus the card fee, or cash plus all listed fees.
Short-term cost as a yearly rate: The total cash advance cost converted to a yearly rate for comparison. It is not the same as your card APR because it includes upfront fees.
Common mistakes and quick fixes
Mistake: Entering the payoff amount in Cash advance amount ($) instead of the cash received.
Fix: Use only the cash you take out, then read Total amount to repay for the estimated payoff amount.
Mistake: Using the purchase APR in Cash advance APR (percent).
Fix: Use the cash advance APR from your card terms, because it is often listed separately.
Mistake: Leaving Card cash advance fee (percent) blank because the Minimum card fee ($) is known.
Fix: Enter both fields; the calculator uses the larger fee and shows Card cash advance fee.
Mistake: Counting Days until you pay it back only to the day you send payment.
Fix: Count to the day the payment is expected to post, because Interest through payoff day depends on the number of days.
Mistake: Adding Extra ATM or bank fee ($) when it does not apply.
Fix: Leave Extra ATM or bank fee ($) at 0 unless that extra charge is caused by the cash advance.
Mistake: Assuming Cost cut if paid 7 days sooner is always a full week of savings.
Fix: If Days until you pay it back is under 7, the savings is capped at the interest for the days you entered.
Limitations & Key Assumptions / Boundary Conditions
- The calculator uses simple daily interest with 365 days per year. It does not simulate statement-cycle compounding, average daily balance rules, or payment allocation.
- Cash advances often start interest on the transaction date rather than after a purchase grace period, but exact timing depends on your card agreement and payment posting date.
- The fee estimate uses the larger of Card cash advance fee (percent) and Minimum card fee ($). Your issuer may also have separate ATM, bank, or network fees.
- What balance should earn interest? is an assumption. Choose the option that matches your card terms if the agreement says fees are added to the interest balance.
- Same-day payoff is allowed, so Interest through payoff day can be $0, but Short-term cost as a yearly rate is shown as N/A because a yearly rate cannot divide by 0 days.
- The 7-day timing check uses the same interest balance and daily rate. It does not predict late fees, credit limit effects, or changes in APR.
Methodology
Calculation steps
The calculator first finds the card issuer fee as the larger of the percent fee and the flat minimum fee.
issuer_fee = max(advance_amount * fee_percent / 100, minimum_fee)
It converts the cash advance APR to a simple daily rate using 365 days per year.
daily_rate = cash_advance_apr / 100 / 365
The interest balance comes from What balance should earn interest? Cash only uses the cash advance amount. Cash plus card fee adds the issuer fee. Cash plus card fee and extra fee also adds Extra ATM or bank fee ($).
interest_balance = advance_amount, advance_amount + issuer_fee, or advance_amount + issuer_fee + atm_fee
Interest is estimated from the selected interest balance, the daily rate, and Days until you pay it back. This matches the idea that cash advance interest generally starts on the transaction date rather than after a purchase grace period [2].
interest_charged = interest_balance * daily_rate * days_until_paid
Total cost is the amount paid above the cash received.
total_cost = issuer_fee + atm_fee + interest_charged
Total amount to repay adds the cash received back to the total cost.
total_to_repay = advance_amount + total_cost
The 7-day timing check uses the same daily interest math. Savings is capped when the entered payoff time is under 7 days.
seven_day_extra_cost = interest_balance * daily_rate * 7
seven_day_savings = interest_balance * daily_rate * min(7, days_until_paid)
The short-term yearly rate annualizes the full cost over the entered number of days. It is shown as N/A when Days until you pay it back is 0.
effective_apr = (total_cost / advance_amount) * (365 / days_until_paid) * 100
Mini-example
For a $500 cash advance, a 5% card fee, a $10 minimum fee, a 29.99% cash advance APR, 30 days until payoff, no extra ATM fee, and Cash only interest, the issuer fee is max($25, $10), or $25. The daily rate is 29.99% / 365, so interest is about $12.32. Total cost is $25 + $0 + $12.32 = $37.32, and total amount to repay is about $537.32. Paying 7 days sooner cuts about $2.88 of interest, while waiting 7 more days adds about $2.88.
Sources
- Can I withdraw money from my credit card at an ATM? | Consumer Financial Protection Bureau - Consumerfinance
- What is a grace period for a credit card? | Consumer Financial Protection Bureau - Consumerfinance
- How does my credit card company calculate the amount of interest I owe? | Consumer Financial Protection Bureau - Consumerfinance
- CFPB - Consumer Credit Card Market Report (cash advances: fee, separate APR, typically no grace period) - Consumerfinance