
Enter your starting balance, billing cycle days, APR, and posted transactions to check your credit card average daily balance.
Table of contents
How to use our Credit Card Average Daily Balance Calculator
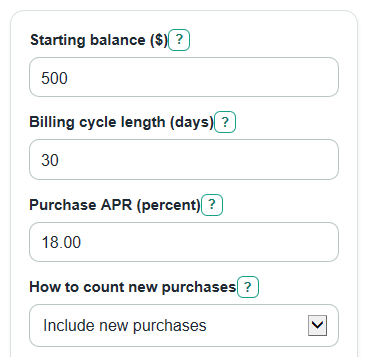
- Enter the Starting balance ($) from the start of day 1 of the billing cycle.
- Enter the exact Billing cycle length (days) and your Purchase APR (percent).
- Choose How to count new purchases so it matches your statement wording.
- Type Transactions (posted day, type, amount) using purchase, payment, credit, or fee, with positive dollar amounts.
- Click Calculate, then scan Balance stretches used to make sure each balance changed on the correct posted day.
Definitions
Starting balance ($): The balance at the start of day 1 of the billing cycle, before day 1 transactions are applied.
Billing cycle length (days): The number of days in the statement period used for the average.
Purchase APR (percent): APR means annual percentage rate. Credit card interest is based on an annual rate but is commonly accrued daily [2].
Posted day: The day number in the billing cycle when a transaction is posted to the account.
Average daily balance: The total of each day's balance divided by the number of days in the billing cycle.
Balance stretches used: Groups of consecutive days that had the same balance, such as days 1 to 10 at $500.
Daily rate used: The APR divided by 365, shown as a percent per day for this estimate.
Total of all daily balances: The daily balances added together before dividing by the billing cycle length. Its unit is dollar-days.
Common mistakes and quick fixes
Mistake: Using the closing statement balance as the Starting balance ($) .
Fix: Use the balance at the start of day 1, usually the prior statement balance after earlier charges were posted.
Mistake: Guessing 30 for Billing cycle length (days) when the statement cycle has 28, 31, or another number of days.
Fix: Count the exact days in the billing cycle shown on your statement.
Mistake: Typing negative amounts in Transactions (posted day, type, amount) for payments or credits.
Fix: Enter amounts as positive numbers and use payment or credit as the type.
Mistake: Using the transaction date instead of the posted day in Transactions (posted day, type, amount) .
Fix: Use the day the transaction posted within the billing cycle, because that is when it starts changing the daily balance.
Mistake: Leaving How to count new purchases on the wrong setting when checking a real statement.
Fix: Match the setting to the balance computation wording on your statement or card agreement.
Mistake: Entering a monthly rate in Purchase APR (percent) instead of the annual percentage rate.
Fix: Enter the APR as an annual percent, such as 18.00 for 18% APR.
Limitations & Key Assumptions / Boundary Conditions
- This is an educational estimate for one balance category. Real statements can separate purchases, cash advances, balance transfers, fees, or promotional rates.
- The calculator uses APR divided by 365 for Daily rate used. Your issuer may disclose a daily periodic rate or another exact method.
- Transactions (posted day, type, amount) uses posted day numbers, not calendar dates or purchase dates.
- How to count new purchases only controls purchase rows. Payment, credit, and fee rows are still counted when posted.
- Negative daily balances are kept in Average daily balance, but Estimated interest for this cycle is floored at $0 when the average is negative.
- The calculator does not apply grace periods, minimum interest charges, compounding, refunds after the cycle, or issuer-specific rounding rules.
- Billing cycle length (days) must be a whole number from 1 to 62, so it is not meant for long payoff projections.
Methodology
How the daily balances are built
The calculator starts with Starting balance ($) for day 1. Each row in Transactions (posted day, type, amount) is read as a posted day, a type, and a positive dollar amount. Purchase and fee rows add to the balance. Payment and credit rows subtract from the balance.
signed_amount = amount for purchase or fee; signed_amount = -amount for payment or credit
If How to count new purchases is set to include new purchases, purchase rows count starting on their posted day.
daily_balance[d] = starting_balance + sum(signed_amount for transactions with posted_day <= d)
If How to count new purchases is set to do not count new purchases, purchase rows are ignored for the average and interest calculation. Payment, credit, and fee rows still count.
daily_balance[d] = starting_balance + sum(signed_amount for non-purchase transactions with posted_day <= d)
How the average and interest are found
The calculator adds every daily balance, then divides by Billing cycle length (days).
balance_day_total = sum(daily_balance[d] for d = 1 to cycle_days)
average_daily_balance = balance_day_total / cycle_days
For the interest estimate, the calculator divides Purchase APR (percent) by 100 and then by 365 to get the decimal daily rate. Credit card interest calculations commonly use APR, average daily balance, and the number of days in the billing period [2].
daily_periodic_rate = (apr_percent / 100) / 365
estimated_interest_charge = max(0, average_daily_balance) * daily_periodic_rate * cycle_days
Money outputs are rounded to the nearest cent for display. Internal math keeps more precision until the final display step.
Balance stretches
Balance stretches used groups consecutive days with the same daily balance. Each row shows the day range, number of days, balance, and contribution to Total of all daily balances.
contribution = number_of_days * balance
Worked mini-example
With a $500 starting balance, 30 billing days, 18% APR, and rows 11, purchase, 100; 16, purchase, 300; 26, payment, 700, the include-new-purchases method gives these stretches: days 1 to 10 at $500, days 11 to 15 at $600, days 16 to 25 at $900, and days 26 to 30 at $200. The total is $18,000-days, so the average daily balance is $18,000 / 30 = $600. The daily rate is 18% / 365 = 0.049315% per day, and the estimated interest is $600 * 0.18 / 365 * 30 = $8.88.