
Estimate your car payment, interest, payoff time, and how extra principal could shorten your auto loan.
Table of contents
How to use our Car Loan Amortization Calculator
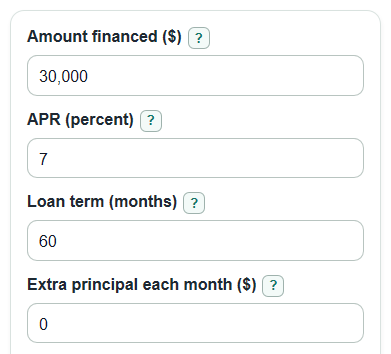
- Enter Amount financed ($), Annual interest rate (%), and Loan term (months) from your loan offer or statement.
- Enter Extra principal each month ($) if you plan to pay more than the required payment, or leave it at 0.
- Choose the First payment date so the Amortization schedule uses month labels that match your plan.
- Open Advanced options only if you want to add a One-time extra principal ($) amount after a specific payment number.
- Click Calculate, then sanity-check the results: Regular monthly payment should match the loan terms, an interest rate of 0 should show $0 interest, and the last balance in the schedule should reach $0.
Definitions
Amount financed ($): The starting loan balance. It should include taxes, fees, or add-ons only if they are included in the loan.
Annual interest rate (%): The yearly contract interest rate used to calculate monthly interest. APR may include fees and can differ from this rate; use the interest rate on your loan agreement.
Principal: The part of the loan balance that you still owe before interest is added for the month.
Interest: The cost charged for borrowing money during a payment period.
Regular monthly payment: The fixed required payment that pays off the loan on schedule before optional extra principal.
Extra principal: Extra money paid directly toward the loan balance. It saves interest only when the lender applies it to principal.
Amortization schedule: A month-by-month table showing payment, interest, principal, extra principal, and ending balance.
Final payment: The last payment needed to bring the balance to $0. It may be smaller than the regular payment.
Common mistakes and quick fixes
Mistake: Using the car sticker price for Amount financed ($) even though the loan also includes financed taxes, fees, or a trade-in payoff.
Fix: Enter the starting loan balance for Amount financed ($), including only costs that are rolled into the loan.
Mistake: Entering 0.07 for Annual interest rate (%) when the loan rate is 7 percent.
Fix: Enter 7 for Annual interest rate (%), not 0.07.
Mistake: Entering years in Loan term (months), such as 5 for a 5-year loan.
Fix: Convert years to months, such as 60 for a 5-year loan.
Mistake: Putting the full payment amount in Extra principal each month ($).
Fix: Enter only the extra amount above the Regular monthly payment, such as 100 if you plan to pay $100 extra.
Mistake: Setting One-time extra after payment number outside the loan term.
Fix: Use a whole payment number from 1 through Loan term (months), such as 12 for an extra payment with the 12th bill.
Mistake: Expecting First payment date to change the interest math.
Fix: Use First payment date only for schedule labels; this calculator uses monthly interest periods.
Limitations & Key Assumptions / Boundary Conditions
- The model assumes one payment per month and a constant annual contract interest rate. It does not derive an interest rate from APR or separate fees. It does not calculate daily simple interest between exact calendar dates.
- Amount financed ($) should already include any financed taxes, fees, add-ons, or trade-in payoff. Upfront cash costs are not included.
- Extra principal each month ($) and One-time extra principal ($) reduce interest only if the lender applies the money to principal. If the lender only moves your next due date, the savings may be lower.
- The results do not include late fees, skipped payments, deferments, refinancing, prepayment penalties, changing interest rates, insurance, repairs, fuel, or registration costs.
- First payment date is used to label the Amortization schedule. It does not change the interest calculation.
- Displayed money is rounded to the nearest cent, but the payoff loop keeps more precision internally to reduce rounding drift.
Methodology
Monthly payment
APR can include lender fees as well as interest. This calculator uses the contract interest rate for the payment schedule. See the CFPB explanation of interest rate and APR.
The calculator first changes Annual interest rate (%) into a monthly rate by dividing by 100 and then by 12. It then uses the standard fixed-payment loan formula for a loan with level monthly payments and a constant rate.
monthly_rate = (apr_percent / 100) / 12
if monthly_rate = 0, regular_payment = amount_financed / term_months
if monthly_rate > 0, regular_payment = amount_financed * monthly_rate * (1 + monthly_rate)^term_months / ((1 + monthly_rate)^term_months - 1)
Payment-by-payment loop
Each month starts with the current balance. Interest is added for that month, the regular payment is applied, and then any extra principal is applied without overpaying the remaining balance.
interest = balance * monthly_rate
scheduled_due = balance + interest
scheduled_payment = min(regular_payment, scheduled_due)
scheduled_principal = scheduled_payment - interest
balance_after_regular = balance - scheduled_principal
planned_extra = extra_monthly + one_time_extra_if_this_month
extra_applied = min(planned_extra, balance_after_regular)
ending_balance = balance_after_regular - extra_applied
total_paid_this_month = scheduled_payment + extra_applied
Totals and comparison
The baseline loan is the same loan with no Extra principal each month ($) and no One-time extra principal ($). The plan loan uses your extra-payment entries. The calculator compares the two payoff paths.
total_interest = sum(monthly interest)
total_paid = sum(total_paid_this_month)
interest_saved = baseline_total_interest - plan_total_interest
months_saved = baseline_payoff_months - plan_payoff_months
The loop stops when the ending balance reaches zero. If the last regular payment would be too large, the Final payment is reduced to the amount needed to pay off the balance.
Mini-example
For Amount financed ($) of $30,000, Annual interest rate (%) of 7, and Loan term (months) of 60, the Regular monthly payment is about $594.04. The first month interest is $175.00. With no extra principal, total interest is about $5,642.16 over 60 months. If Extra principal each month ($) is $100, the same loan pays off in about 50 months, total interest is about $4,669.83, Interest saved by extras is about $972.33, and Time saved by extras is 10 months.