
Estimate an SBA 7(a) or 504 loan payment, upfront fee, spendable cash, and borrower cash needed.
Table of contents
How to use our SBA Loan Calculator
- Choose the Loan program: 7(a) term loan for one SBA-backed loan, or 504 project loan for a bank, CDC, and borrower cash split.
- Enter the visible dollar amount, rate, and Loan term. For 7(a), use 7(a) loan amount and 7(a) annual rate. For 504, use Total 504 project cost, 504 bank loan annual rate, and 504 CDC loan annual rate.
- Open Advanced options if you need to change How the 7(a) upfront fee is paid, Manufacturer fee relief, Other 7(a) loans approved in last 90 days, or the 504 split and fee assumptions.
- Click Calculate and read Estimated monthly payment first, then check the SBA fee, spendable cash, total interest, and 504 split outputs that apply to your selected program.
- Sanity-check the result by comparing the term to the payment size: a longer Loan term should usually lower the monthly payment but raise Total interest over the term.
Definitions
SBA 7(a) loan: A common SBA-backed business loan handled as one loan from a lender to the borrower.
SBA 504 loan: A project financing structure that usually has a private lender loan, a CDC loan, and borrower cash.
CDC loan: The Certified Development Company part of a 504 project. In this calculator, the CDC amount can include estimated financed 504 fees.
Upfront SBA fee: A fee based on the SBA-guarantied portion of a 7(a) loan. The calculator shows how it changes spendable 7(a) cash when taken from proceeds.
Guarantied portion: The part of the 7(a) loan amount used to estimate the SBA upfront fee, found by multiplying the gross loan amount by the guaranty rate.
Loan term: The number of monthly payments used in the payment formula.
Total interest over the term: The scheduled interest paid if the rate and payment schedule stay the same for the whole term.
Common mistakes and quick fixes
Mistake: Using Loan program set to 7(a) term loan when you are comparing a 504 project.
Fix: Change Loan program to 504 project loan so Estimated monthly payment includes both the bank and CDC parts.
Mistake: Entering the cash you want to receive as 7(a) loan amount when the SBA fee will be taken from proceeds.
Fix: Use the gross approved 7(a) loan amount, then check Estimated spendable 7(a) cash.
Mistake: Leaving 7(a) annual rate, 504 bank loan annual rate, or 504 CDC loan annual rate blank because the quote is not final.
Fix: Enter a reasonable estimate in the rate field for the selected Loan program, then update it when the lender gives a quote.
Mistake: Setting 504 bank share and 504 borrower cash share so high that there is no CDC part left.
Fix: Keep 504 bank share plus 504 borrower cash share below 100%, then review 504 CDC loan amount with estimated financed fees.
Mistake: Ignoring Other 7(a) loans approved in last 90 days when you have recent related approvals.
Fix: Enter that amount so Estimated 7(a) upfront SBA fee uses an incremental fee estimate.
Mistake: Treating Total of scheduled payments as the full project cost.
Fix: Add taxes, insurance, closing costs, and any lender fees outside this calculator before making a cash plan.
Limitations & Key Assumptions / Boundary Conditions
- This is an estimate, not an approval, commitment, or final lender disclosure.
- The 7(a) fee estimate uses the calculator's FY2026 fee logic and simplified common guaranty rates. Special loan types, lender rules, SBA notices, or eligibility decisions can change the actual fee.
- The Manufacturer fee relief choice does not decide eligibility. It only applies the fee-relief assumption when the selected facts fit the calculator rule.
- If Other 7(a) loans approved in last 90 days is more than $0, the fee is an incremental estimate. The actual treatment depends on the exact approvals and lender processing.
- The 504 split uses your 504 bank share, 504 borrower cash share, and Estimated 504 fees financed into CDC loan. Real 504 deals can require a different borrower contribution or fee amount.
- Payments assume a fixed annual rate, equal monthly payments, and no prepayments, late fees, balloon payments, refinancing, taxes, insurance, or closing costs.
- The calculator warns about common SBA size thresholds, but it does not test every SBA maximum, affiliation rule, collateral rule, use-of-proceeds rule, or program exception.
Methodology
Payment math
The calculator uses the standard fixed-rate loan payment formula for each note. The annual rate is divided by 100 and then by 12 to get the monthly rate. If the monthly rate is 0, the payment is the principal divided by the number of months.
monthly_rate = annual_rate_percent / 100 / 12
payment = principal * (monthly_rate * (1 + monthly_rate)^months) / ((1 + monthly_rate)^months - 1)
if monthly_rate = 0, payment = principal / months
Total interest is the total of scheduled payments minus the financed principal. For a 504 loan, the calculator adds the bank note interest and CDC note interest.
total_interest = payment * months - principal
7(a) fee and cash method
For 7(a) mode, the principal used for the payment is the gross 7(a) loan amount. The calculator estimates the SBA upfront fee from the guarantied portion.
guaranty_rate = 0.85 if gross_loan_amount <= 150000 else 0.75
guarantied_portion = gross_loan_amount * guaranty_rate
if term_months <= 12: fee = 0.0025 * guarantied_portion
else if manufacturer_fee_relief = yes and gross_loan_amount <= 950000: fee = 0
else if gross_loan_amount <= 150000: fee = 0.02 * guarantied_portion
else if gross_loan_amount <= 700000: fee = 0.03 * guarantied_portion
else: fee = 0.035 * min(guarantied_portion, 1000000) + 0.0375 * max(guarantied_portion - 1000000, 0)
If Other 7(a) loans approved in last 90 days is greater than $0, the calculator estimates the current loan's incremental fee as the combined-loan fee minus the previous-loan fee, floored at $0.
incremental_fee = max(fee(previous_loan_amount + current_loan_amount) - fee(previous_loan_amount), 0)
Spendable 7(a) cash depends on How the 7(a) upfront fee is paid.
net_cash_to_borrower = gross_loan_amount - upfront_fee if upfront_fee_method = from_proceeds else gross_loan_amount
504 split method
For 504 mode, the calculator splits Total 504 project cost into the bank loan, borrower cash, and CDC base loan. It then adds estimated financed 504 fees to the CDC amount.
bank_loan = project_cost * bank_share_percent / 100
borrower_cash = project_cost * borrower_share_percent / 100
cdc_base = project_cost - bank_loan - borrower_cash
cdc_loan = cdc_base * (1 + estimated_504_fee_percent / 100)
The 504 Estimated monthly payment is the bank payment plus the CDC payment. The bank loan uses 504 bank loan annual rate. The CDC loan uses 504 CDC loan annual rate.
Mini-example
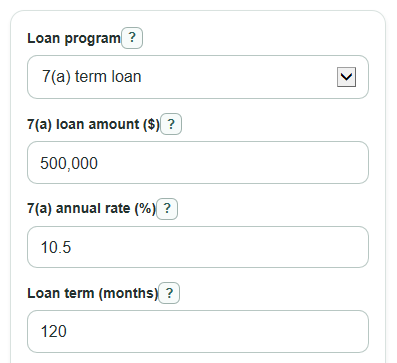
For a $500,000 7(a) loan at 10.5% for 120 months, the monthly rate is 0.105 / 12. The payment formula gives about $6,746.75 per month. Because the loan is above $150,000 and not above $700,000, the simplified guaranty rate is 75% and the fee rate is 3% of the guarantied portion, so the estimated upfront fee is $500,000 * 0.75 * 0.03 = $11,250. If that fee is taken from proceeds, the estimated spendable 7(a) cash is $488,750.