
Estimate how long a mortgage refinance takes to pay back and whether it still helps by your planned move or refinance date.
Table of contents
How to use our Mortgage Refinance Break-Even Calculator
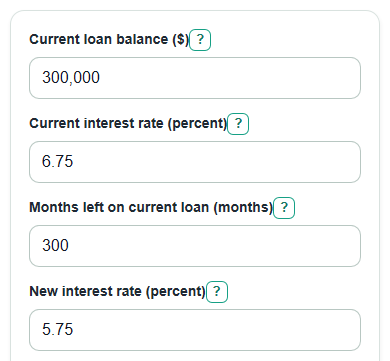
- Enter your Current loan balance ($), Current interest rate (percent), and Months left on current loan (months) from your latest mortgage statement.
- Enter the New interest rate (percent), New loan term (years), and Costs paid to refinance ($) from your quote or estimate.
- Open Advanced options if you want to change How costs are paid, Planned time to keep this loan (months), Current mortgage insurance ($ per month), or New mortgage insurance ($ per month).
- Select Calculate and read Payment break-even time first, then compare Overall gain at planned time with Extra loan balance at planned time.
- Sanity-check the Current monthly payment used and New monthly payment used against your real principal-and-interest numbers; large differences usually mean escrow, insurance, taxes, or the wrong loan balance got included.
Definitions
Current loan balance ($): The unpaid principal you still owe on the current mortgage, not the original amount borrowed.
Interest rate: The note rate used to calculate monthly interest. It is different from APR, which can include some loan costs.
Loan term: The full length of the loan or the time left on the current loan, measured in years or months.
Refinance costs: Fees and charges paid to get the new loan, such as lender fees, title charges, appraisal fees, recording fees, and points. One point is 1 percent of the mortgage loan amount [3].
Mortgage insurance: A monthly charge such as PMI or FHA mortgage insurance that may apply when the lender requires it.
Amortization: Paying a loan down over time with regular payments that cover interest and principal. Most home loans amortize [1].
Payment break-even time: The number of months it takes for monthly payment savings to cover refinance costs.
Extra loan balance at planned time: The new loan balance minus the current-loan balance at the planned time. Positive means the refinance path leaves more debt.
Common mistakes and quick fixes
Mistake: Entering the original mortgage amount in Current loan balance ($).
Fix: Use the unpaid principal balance from your current statement.
Mistake: Using APR in Current interest rate (percent) or New interest rate (percent).
Fix: Use the note rate for each loan, because the payment formula uses the interest rate charged on the balance.
Mistake: Leaving Costs paid to refinance ($) out because the lender says the refinance has no upfront cost.
Fix: Include costs if they are Added to new loan, paid through points, or built into the loan offer in a way you want to compare.
Mistake: Setting New loan term (years) to 30 without checking Extra loan balance at planned time.
Fix: Compare the balance change, because a longer term can lower the payment while slowing payoff.
Mistake: Ignoring Planned time to keep this loan (months).
Fix: Enter the months until you may sell, refinance again, or pay off the loan, then use Overall gain at planned time for the decision.
Mistake: Putting property taxes or homeowners insurance in Current mortgage insurance ($ per month) or New mortgage insurance ($ per month).
Fix: Enter only PMI, FHA mortgage insurance, or similar mortgage insurance, not escrow items that may continue either way.
Limitations & Key Assumptions / Boundary Conditions
- The calculator estimates fixed-rate principal-and-interest payments plus any mortgage insurance you enter. It does not include property taxes, homeowners insurance, HOA dues, escrow changes, late fees, or servicing fees.
- Use note rates, not APR, because the payment formula applies the interest rate directly to the loan balance.
- The break-even result is a simple payment-savings payback measure. It does not price investment returns, tax effects, inflation, or the value of keeping cash available.
- If refinance costs are Added to new loan, the calculator adds those costs to the new loan amount and reflects them through the payment and remaining balance.
- If Planned time to keep this loan (months) is longer than a loan lasts, that loan's remaining balance is treated as $0 after payoff.
- Actual lender disclosures may differ because of prepaid interest, escrow setup, rate locks, points, credits, adjustable-rate terms, or cash-out amounts not entered here.
Methodology
Payment calculation
The calculator first estimates the current and new monthly principal-and-interest payments using the standard fixed-payment loan formula. Mortgage insurance is added after that principal-and-interest payment.
monthly_rate = annual_rate_percent / 100 / 12
payment = principal * monthly_rate * (1 + monthly_rate)^months / ((1 + monthly_rate)^months - 1)
if monthly_rate = 0, payment = principal / months
current_monthly_payment = payment(current_balance, current_rate_percent, current_months_left) + current_monthly_mi
new_loan_amount = current_balance + rolled_costs
new_monthly_payment = payment(new_loan_amount, new_rate_percent, new_term_years * 12) + new_monthly_mi
Savings and break-even
Monthly savings is the current monthly payment used minus the new monthly payment used. A positive number means the refinance lowers the monthly payment. A negative number means the refinance raises it.
monthly_savings = current_monthly_payment - new_monthly_payment
The payment break-even time divides refinance costs by monthly savings when monthly savings is positive. This is the common refinance break-even check described by the Federal Reserve as a way to compare refinance costs with expected monthly savings [3].
break_even_months = refinance_costs / monthly_savings
if refinance_costs = 0 and monthly_savings > 0, break_even_months = 0
if monthly_savings <= 0, there is no payment break-even
Planned-stay comparison
The calculator also estimates each loan balance at your planned time. This keeps a lower-payment refinance from looking better than it is when the new loan term is much longer or refinance costs are rolled into the new balance.
remaining_balance = principal * (1 + monthly_rate)^k - payment * (((1 + monthly_rate)^k - 1) / monthly_rate)
if monthly_rate = 0, remaining_balance = principal - payment * k
k = min(planned_stay_months, loan_months)
cash_position_at_planned_stay = monthly_savings * planned_stay_months - cash_cost_paid_at_closing
new_minus_current_balance_at_planned_stay = new_remaining_balance - current_remaining_balance
overall_gain_at_planned_stay = cash_position_at_planned_stay - new_minus_current_balance_at_planned_stay
Mini-example
Suppose the current balance is $300,000, the current rate is 6.75 percent, and 300 months are left. A new 30-year loan at 5.75 percent with $6,000 paid at closing gives an estimated current monthly payment of $2,072.73 and a new monthly payment of $1,750.72. Monthly savings is $322.02, so the payment break-even time is about 18.63 months. After 60 months, cash saved is about $13,320.96, but the new loan balance is about $5,688.89 higher than the current-loan path. The overall gain at planned time is about $7,632.07.