
Estimate if your cash-out refinance fits a loan-to-value limit and how much cash you may receive after closing costs.
Table of contents
How to use our Cash-Out Refinance Calculator
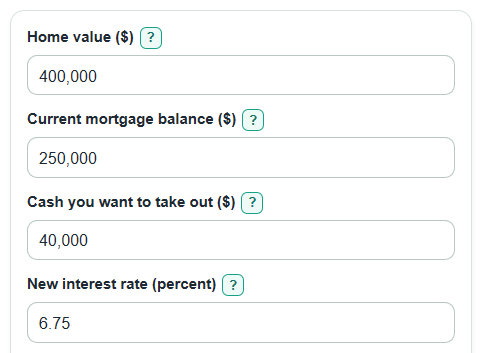
- Enter Home value ($), Current mortgage balance ($), and Cash you want to take out ($) using realistic numbers.
- Enter New interest rate (percent) and New loan length (years) for the refinance loan you are comparing.
- Open Advanced options if you need to change Cash-out limit (percent of home value), closing costs, How closing costs are paid, or add Current principal and interest payment ($ per month).
- Click Calculate and read Does the requested cash-out fit? first, then compare Estimated cash to you with the cash amount you entered.
- Sanity-check the results: New loan-to-value should rise when you take more cash, and Estimated cash to you should drop when costs are taken from your cash.
Definitions
Cash-out refinance: A new mortgage that pays off your current mortgage and adds extra borrowed cash.
Home value ($): The property value used to compare the new loan with the home. A lender may use an appraisal.
Loan-to-value: The new loan amount divided by Home value ($), shown as a percent.
Cash-out limit (percent of home value): The largest loan-to-value percent you want the calculator to allow for the refinance.
Closing costs: Loan costs such as lender and settlement charges. A Loan Estimate is a lender form that lists estimated closing costs [3].
Principal and interest payment: The monthly loan payment before property taxes, homeowners insurance, mortgage insurance, HOA dues, or other housing costs.
Simple break-even time: Estimated closing costs divided by monthly payment savings, shown only when the new principal and interest payment is lower.
Common mistakes and quick fixes
Mistake: Using a guessed Home value ($) that is much higher than a likely appraisal.
Fix: Use a realistic market value because New loan-to-value and Loan room at your limit depend directly on it.
Mistake: Entering Current mortgage balance ($) from an old statement instead of a payoff estimate.
Fix: Use the payoff balance if available, since Estimated new loan amount starts with the balance being paid off.
Mistake: Treating Cash you want to take out ($) as the same thing as Estimated cash to you.
Fix: Check How closing costs are paid; costs taken from your cash reduce Estimated cash to you.
Mistake: Putting taxes, insurance, or HOA dues in Current principal and interest payment ($ per month).
Fix: Enter only principal and interest so Monthly payment change compares loan payments on the same basis.
Mistake: Leaving Cash-out limit (percent of home value) at 80 when your loan program uses a different cap.
Fix: Change the limit to match your lender or loan type before trusting Does the requested cash-out fit?
Limitations & Key Assumptions / Boundary Conditions
- This is an estimate, not a loan approval. Lenders can use different cash-out rules, credit standards, appraised values, and pricing.
- The calculator estimates principal and interest only. It does not include taxes, homeowners insurance, HOA dues, mortgage insurance, escrow changes, or prepaid interest.
- Closing costs are estimated from Closing costs (percent of new loan) plus Extra closing costs ($). Actual lender disclosures can be different.
- If How closing costs are paid is Added to the new loan, the calculator solves for a larger loan because the percent-based closing cost is based on the final new loan amount.
- Loan room at your limit and Home equity left after refinance are signed amounts. Negative values are kept because they show an over-limit request or a loan larger than the entered home value.
- Simple break-even time is a basic payment-savings check. It ignores tax effects, investment returns, future refinancing, selling the home, and how you use the cash out.
Methodology
Core loan amount
The calculator first finds the largest loan allowed by the selected cash-out limit.
max_loan_allowed = home_value * (max_ltv_percent / 100)
It then builds the refinance before closing-cost treatment.
base_loan = current_balance + cash_out_amount
If closing costs are paid upfront or taken from your cash, closing costs do not increase the new loan.
new_loan_amount = base_loan
If closing costs are added to the new loan, the calculator solves for the final loan amount because the percent cost is based on that final loan.
new_loan_amount = (base_loan + closing_cost_fixed) / (1 - closing_cost_percent / 100)
Costs, cash, and limit check
Estimated closing costs use the final new loan amount plus any flat extra costs.
closing_cost_estimate = closing_cost_fixed + new_loan_amount * (closing_cost_percent / 100)
Cash to you depends on How closing costs are paid.
if costs are taken from cash: net_cash_to_you = cash_out_amount - closing_cost_estimate
otherwise: net_cash_to_you = cash_out_amount
The loan-to-value percent and remaining room use the new loan amount.
new_ltv_percent = (new_loan_amount / home_value) * 100
loan_room_at_limit = max_loan_allowed - new_loan_amount
equity_remaining = home_value - new_loan_amount
Monthly payment
The new principal and interest payment uses the fixed-rate amortization formula with 12 monthly payments per year.
monthly_rate = new_rate_percent / 100 / 12
number_of_months = new_term_years * 12
monthly_payment = loan * monthly_rate / (1 - (1 + monthly_rate)^(-number_of_months))
If the new interest rate is 0 percent, the payment is the loan divided by the number of months.
monthly_payment = loan / number_of_months
When Current principal and interest payment ($ per month) is entered, the calculator also compares payments and shows a simple break-even time only if the new payment is lower.
payment_change = new_monthly_pi_payment - current_pi_payment
simple_break_even_months = closing_cost_estimate / (current_pi_payment - new_monthly_pi_payment)
Mini example
With a $400,000 Home value ($), $250,000 Current mortgage balance ($), $40,000 Cash you want to take out ($), an 80 percent Cash-out limit (percent of home value), 3 percent closing costs, and costs taken from your cash, the maximum loan allowed is $320,000. The new loan amount is $290,000, estimated closing costs are $8,700, Estimated cash to you is $31,300, New loan-to-value is 72.5 percent, and Loan room at your limit is $30,000. At 6.75 percent for 30 years, the estimated New principal and interest payment is about $1,880.93 per month.