
Estimate your monthly housing payment with loan payments, property tax, home insurance, and optional PMI, HOA, and income checks.
Advanced options
Table of contents
How to use our PITI Calculator
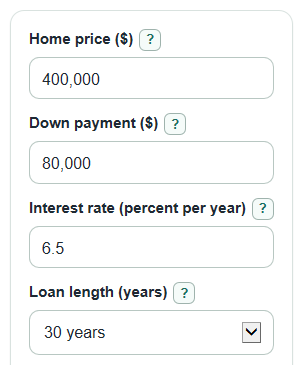
- Enter Home price ($), Down payment ($), Interest rate (percent per year), Loan length (years), Property tax ($ per year), and Home insurance ($ per year).
- Open Advanced options if you need PMI rate (percent per year), HOA dues ($ per month), Gross monthly income ($), or Other monthly debts ($).
- Click Calculate to see Estimated monthly housing payment first, then the loan-only payment and each added monthly cost.
- If you entered Gross monthly income ($), review Housing share of income and Housing plus other debts share of income to see budget pressure.
- Sanity-check the output by comparing Estimated loan amount with home price minus down payment, and make sure Property tax ($ per year) and Home insurance ($ per year) are yearly amounts, not monthly amounts.
Definitions
PITI: Principal, interest, taxes, and insurance. A total monthly mortgage payment often includes these costs, and may also include mortgage insurance [1].
Principal and interest payment: The fixed monthly loan payment before property tax, home insurance, PMI, and HOA dues are added.
Property tax: A local tax on the home. This calculator uses Property tax ($ per year) and converts it to a monthly estimate.
Home insurance: Homeowners insurance for the property. This calculator uses Home insurance ($ per year) and converts it to a monthly estimate.
PMI: Private mortgage insurance. It may apply on some conventional loans when the down payment is less than 20 percent [3].
HOA dues: Homeowner association dues paid for some condos, townhomes, and neighborhoods. They are not part of the loan, but they affect monthly housing cost.
Gross monthly income: Monthly income before taxes, insurance, retirement savings, and other paycheck deductions.
Down payment share: Down payment divided by home price, shown as a percent. It helps explain whether the PMI estimate is included.
Common mistakes and quick fixes
Mistake: Entering Property tax ($ per year) as a monthly tax bill.
Fix: Use the yearly amount for Property tax ($ per year); the calculator divides it by 12.
Mistake: Using APR in Interest rate (percent per year).
Fix: Enter the loan interest rate in Interest rate (percent per year), because APR can include fees.
Mistake: Leaving PMI rate (percent per year) at 0 with a small Down payment ($) and assuming no PMI exists.
Fix: If the down payment is under 20 percent, enter a realistic PMI rate (percent per year) or read the Estimate note before budgeting.
Mistake: Putting closing costs into Down payment ($).
Fix: Use only cash that reduces the loan balance in Down payment ($); closing costs are separate cash needed at purchase.
Mistake: Entering net take-home pay in Gross monthly income ($).
Fix: Use income before taxes and deductions in Gross monthly income ($), or leave it blank to skip the income checks.
Mistake: Forgetting HOA dues ($ per month) for a condo, townhouse, or neighborhood with dues.
Fix: Enter the regular monthly HOA dues ($ per month) so Estimated monthly housing payment includes them.
Limitations & Key Assumptions / Boundary Conditions
- The result is an estimate, not a loan approval, closing disclosure, tax bill, insurance quote, or PMI quote.
- Interest rate (percent per year) is treated as the note rate for a fixed-rate loan. It is not APR and does not include lender fees, points, or closing costs.
- Property tax ($ per year), Home insurance ($ per year), PMI rate (percent per year), and HOA dues ($ per month) can change after purchase.
- PMI is estimated from the starting loan amount and the entered PMI rate when Down payment share is under 20 percent. Actual PMI depends on the loan program, lender rules, credit profile, and cancellation terms [3].
- The calculator does not include utilities, repairs, condo special assessments, flood insurance, mortgage points, prepaid costs, or escrow cushion requirements.
- Income checks use Gross monthly income ($) and Other monthly debts ($) only. They are simple ratios, not full underwriting rules.
- A 0 percent Interest rate (percent per year) is allowed for testing and uses loan amount divided by the number of monthly payments.
Methodology
Calculation steps
The calculator first finds the starting loan balance from the purchase price and down payment.
loan_amount = home_price - down_payment
It then converts the yearly interest rate to a monthly rate and counts monthly payments from the selected loan length.
monthly_rate = annual_interest_rate / 100 / 12
number_of_payments = loan_term_years * 12
For a fixed-rate loan with interest above 0, it uses the standard amortizing loan payment formula.
monthly_principal_interest = loan_amount * monthly_rate * (1 + monthly_rate)^number_of_payments / ((1 + monthly_rate)^number_of_payments - 1)
If the interest rate is 0, the loan-only payment is spread evenly across the number of payments.
monthly_principal_interest = loan_amount / number_of_payments
Yearly property tax and yearly home insurance are converted to monthly amounts.
monthly_tax_insurance = annual_property_tax / 12 + annual_home_insurance / 12
PMI is added only when the down payment share is below 20 percent and the entered PMI rate is greater than 0.
down_payment_percent = down_payment / home_price * 100
monthly_pmi = loan_amount * (pmi_annual_rate / 100) / 12
The main result adds the loan payment, monthly tax and insurance estimate, PMI when used, and HOA dues.
total_monthly_payment = monthly_principal_interest + monthly_tax_insurance + monthly_pmi + monthly_hoa
When gross monthly income is entered, the calculator also shows simple income-pressure ratios.
housing_income_percent = total_monthly_payment / gross_monthly_income * 100
all_debt_income_percent = (total_monthly_payment + other_monthly_debts) / gross_monthly_income * 100
First payment split
The first-month interest estimate uses the starting loan balance. The rest of the first principal-and-interest payment reduces the balance.
first_month_interest = loan_amount * monthly_rate
first_month_principal = monthly_principal_interest - first_month_interest
Mini-example
For a $400,000 home with an $80,000 down payment, the loan amount is $320,000. At 6.5 percent for 30 years, principal and interest is about $2,022.62 per month. If property tax is $4,800 per year and home insurance is $1,800 per year, tax and insurance add $550.00 per month. With 20 percent down and no HOA dues, estimated PMI is $0, so the estimated monthly housing payment is about $2,572.62.
Sources
- On a mortgage, what's the difference between my principal and interest payment and my total monthly payment? | Consumer Financial Protection Bureau - Consumerfinance
- What is private mortgage insurance? | Consumer Financial Protection Bureau - Consumerfinance
- When can I remove private mortgage insurance (PMI) from my loan? | Consumer Financial Protection Bureau - Consumerfinance