
Estimate how much personal loan cash you could receive based on income, current debt, APR, term, budget room, and fees.
Advanced options
Table of contents
How to use our Personal Loan Affordability Calculator
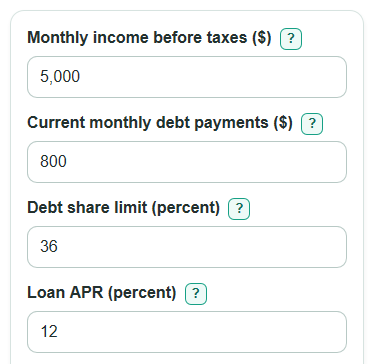
- Enter Monthly income before taxes ($), Current monthly debt payments ($), and your Debt share limit (percent).
- Enter Loan APR (percent) and Loan term (months) for the loan you want to test.
- Open Advanced options if you want to add Monthly take-home pay ($), Monthly must-pay living costs ($), or Origination fee deducted (percent).
- Click Calculate and read Estimated cash you could receive first, then check Limit used to see whether the debt share check or budget check was tighter.
- Sanity-check the answer by comparing Monthly payment used for the estimate with what you can truly pay every month without using savings or skipping bills.
Definitions
Debt share limit: The largest percent of Monthly income before taxes ($) that you want going to debt payments.
APR: Annual percentage rate. In this calculator, Loan APR (percent) is converted to a monthly rate for the payment formula.
Loan term: The number of monthly payments. A longer Loan term (months) can support a larger loan for the same payment, but it can raise Estimated total interest.
Monthly room before any loan floor: The signed payment room from the limiting check. A negative number means your current numbers are already over the selected limit.
Origination fee deducted: A fee taken from the loan before cash is sent to you. It lowers Estimated cash you could receive but does not lower the balance used for payments.
Debt share after this loan: Current monthly debt payments plus the new loan payment, divided by Monthly income before taxes ($), shown as a percent.
Limit used: The check that set Monthly payment used for the estimate. It can be the debt share check or the optional take-home budget check.
Common mistakes and quick fixes
Mistake: Entering take-home pay in Monthly income before taxes ($).
Fix: Use gross monthly pay before taxes there, and put paycheck-after-deductions pay in Monthly take-home pay ($) only if you use Advanced options.
Mistake: Putting rent, groceries, or utilities in Current monthly debt payments ($).
Fix: Enter only debt payments there, and put regular non-debt bills in Monthly must-pay living costs ($).
Mistake: Filling Monthly take-home pay ($) but leaving Monthly must-pay living costs ($) blank.
Fix: Fill both budget fields or clear both so the calculator knows whether to use the optional budget check.
Mistake: Treating Estimated loan amount before fees as the cash you will receive when Origination fee deducted (percent) is above 0.
Fix: Use Estimated cash you could receive for planning the amount available after a deducted fee.
Mistake: Using a low Loan APR (percent) just to make the number bigger.
Fix: Enter a realistic APR offer or prequalification estimate, because APR changes Estimated total interest and the affordable loan amount.
Mistake: Ignoring Monthly room before any loan floor when it is negative.
Fix: Lower Current monthly debt payments ($), choose a higher income-supported Debt share limit (percent), or do not add a new loan under those settings.
Limitations & Key Assumptions / Boundary Conditions
- The result is a planning estimate, not a lender approval, credit limit, or loan offer.
- The calculation assumes a fixed APR, fixed monthly payment, and no skipped payments for the full Loan term (months).
- Loan APR (percent) is treated as the rate used for the payment estimate. Real loan disclosures can include details this calculator does not model.
- Estimated cash you could receive subtracts only Origination fee deducted (percent). It does not include late fees, prepayment penalties, insurance add-ons, or other costs.
- The optional budget check is used only when both Monthly take-home pay ($) and Monthly must-pay living costs ($) are filled with valid numbers.
- The Debt share limit (percent) is user-chosen. Different lenders may use different rules and may also consider credit score, income type, loan purpose, and credit history.
- If Monthly room before any loan floor is negative, the feasible loan amount is floored at $0 because a new affordable loan cannot be negative.
Methodology
Payment room
The calculator first finds the room for a new monthly loan payment using a debt-to-income style check. Debt-to-income compares monthly debt payments with gross monthly income.
dti_room = gross_monthly_income * (max_debt_share_percent / 100) - existing_monthly_debt
If both optional budget fields are filled, it also checks the cash left after must-pay living costs and existing debt.
budget_room = take_home_monthly_pay - monthly_living_costs - existing_monthly_debt
raw_payment_room = lower of dti_room and budget_room, when budget_room is available
monthly_payment_used = max(0, raw_payment_room)
The signed raw payment room is shown as Monthly room before any loan floor. The floor is used only for the loan amount, because the calculator cannot create a negative new loan.
Loan amount from payment room
The calculator converts Loan APR (percent) to a monthly rate and uses the Loan term (months) as the number of payments.
monthly_rate = apr_percent / 100 / 12
n = loan_term_months
For APR above 0, the affordable gross loan amount is the present value of a fixed-payment amortized loan.
gross_loan_amount = monthly_payment_used * (((1 + monthly_rate)^n - 1) / (monthly_rate * (1 + monthly_rate)^n))
For a 0% APR loan, the formula is simpler.
gross_loan_amount = monthly_payment_used * n
Fees, totals, and debt share
If an origination fee is deducted, the estimated cash received is lower than the loan amount used for payments.
affordable_cash_received = gross_loan_amount * (1 - origination_fee_percent / 100)
total_paid = monthly_payment_used * n
total_interest = total_paid - gross_loan_amount
dti_after_loan_percent = ((existing_monthly_debt + monthly_payment_used) / gross_monthly_income) * 100
Mini-example
Suppose Monthly income before taxes ($) is $5,000, Current monthly debt payments ($) is $800, Debt share limit (percent) is 36, Loan APR (percent) is 12, and Loan term (months) is 36. The debt-share room is $5,000 * 36% - $800 = $1,000. With no optional budget check and no fee, the calculator uses a $1,000 monthly payment room. At 12% APR for 36 months, the estimated loan amount before fees is about $30,107.51, total paid is $36,000, and estimated total interest is about $5,892.49.
Calculation choices
The calculator blocks invalid inputs such as income at $0 or below, negative current debt, APR below 0, a non-whole loan term, a debt share limit outside 0 to 100, or an origination fee of 100% or more. Money fields accept commas and a dollar sign, but not ranges or formulas.