
Estimate the home price and loan amount you may prequalify for using income, debts, down payment, rate, and DTI targets.
Table of contents
How to use our Mortgage Prequalification Calculator
- Enter Before-tax income ($ per year), Monthly debt payments ($), Down payment ($), Interest rate (percent), and Loan term (years).
- Open Advanced options only if you want to change property taxes, homeowners insurance, HOA dues, mortgage insurance, Housing limit (percent of income), or Total debt limit (percent of income).
- Click Calculate to see Estimated home price you may prequalify for, Estimated loan amount, and Monthly housing cost at that price.
- Check What capped the estimate. If Total debt limit is the cap, compare it with Monthly debt payment to remove before housing becomes the cap.
- Sanity-check the result by comparing Monthly housing cost at that price with rent, savings goals, local taxes, and quotes from lenders or insurance agents.
Definitions
Before-tax income: Yearly income before taxes, insurance, retirement savings, and other paycheck deductions.
Monthly debt payments: Required monthly payments for debts outside the new mortgage, such as auto loans, student loans, child support, and minimum credit card payments.
Debt-to-income ratio (DTI): The share of monthly before-tax income used for debt payments.
Housing share of income: The estimated monthly housing cost divided by monthly before-tax income.
Housing plus debt share of income: The estimated monthly housing cost plus Monthly debt payments ($), divided by monthly before-tax income.
Housing limit: The target percent of income allowed for the new housing payment only.
Total debt limit: The target percent of income allowed for the new housing payment plus other monthly debt payments.
Mortgage insurance estimate: A yearly percent of the loan amount added to the monthly housing cost estimate.
Common mistakes and quick fixes
Mistake: Using take-home pay in Before-tax income ($ per year).
Fix: Enter gross yearly income before taxes and paycheck deductions.
Mistake: Putting groceries, utilities, or phone bills in Monthly debt payments ($).
Fix: Use required debt payments such as car loans, student loans, child support, and minimum credit card payments.
Mistake: Entering closing-cost cash in Down payment ($).
Fix: Enter only the amount you plan to put toward the home price.
Mistake: Typing 0.065 in Interest rate (percent) for a 6.5% rate.
Fix: Enter the percent number, such as 6.5.
Mistake: Leaving HOA dues ($ per month) at 0 for a condo or neighborhood that has dues.
Fix: Enter the monthly HOA amount because it counts in Monthly housing cost at that price.
Mistake: Treating What capped the estimate as a lender decision.
Fix: Use it as a planning clue only, then ask a lender how it applies to your credit, documents, and loan type.
Limitations & Key Assumptions / Boundary Conditions
- This is a planning estimate, not a loan approval or a rate quote.
- Real prequalification can change after a lender checks credit, income documents, assets, employment, property type, loan program rules, and current pricing.
- The calculator uses editable Housing limit (percent of income) and Total debt limit (percent of income). Actual lender limits may be higher or lower.
- Property tax estimate (percent of home price per year), Homeowners insurance estimate (percent of home price per year), HOA dues ($ per month), and Mortgage insurance estimate (percent of loan per year) are simplified estimates.
- The payment formula assumes a fixed-rate loan with equal monthly principal-and-interest payments for the selected Loan term (years).
- Closing costs, prepaid taxes, rate points, seller credits, reserves, and repair costs are not included in Down payment ($).
- If Monthly debt payments ($) already use the selected Total debt limit (percent of income), the calculator cannot solve a feasible mortgage estimate until inputs change.
Methodology
How the estimate is built
The calculator first turns Before-tax income ($ per year) into monthly income.
monthly_income = annual_income / 12
It then finds the monthly principal-and-interest payment per $1 borrowed. For a 0% Interest rate (percent), it uses a straight payoff over the loan term. Otherwise, it uses the fixed-rate amortized loan payment factor.
monthly_rate = interest_rate_percent / 100 / 12
term_months = loan_term_years * 12
if monthly_rate = 0, payment_factor = 1 / term_months
otherwise payment_factor = monthly_rate * (1 + monthly_rate)^term_months / ((1 + monthly_rate)^term_months - 1)
Next, the calculator finds the most housing cost allowed by the two DTI targets.
front_allowed = monthly_income * front_end_limit_percent / 100
back_allowed = monthly_income * back_end_limit_percent / 100 - monthly_debts
allowed_housing = min(front_allowed, back_allowed)
Property tax and homeowners insurance are treated as yearly percents of the home price. Mortgage insurance is treated as a yearly percent of the loan amount.
loan_cost_rate = payment_factor + mortgage_insurance_rate_percent / 100 / 12
home_cost_rate = property_tax_rate_percent / 100 / 12 + homeowners_insurance_rate_percent / 100 / 12
max_home_price = (allowed_housing - hoa_monthly + down_payment * loan_cost_rate) / (loan_cost_rate + home_cost_rate)
The loan amount is the estimated home price minus the down payment, with a floor at $0 because a mortgage loan cannot be negative.
max_loan_amount = max(0, max_home_price - down_payment)
The monthly housing cost is then rebuilt from the solved home price and loan amount.
principal_interest = max_loan_amount * payment_factor
taxes_insurance = max_home_price * home_cost_rate
mortgage_insurance = max_loan_amount * mortgage_insurance_rate_percent / 100 / 12
max_monthly_housing_payment = principal_interest + taxes_insurance + mortgage_insurance + hoa_monthly
Finally, the calculator reports the DTI results and the binding limit.
front_end_dti = max_monthly_housing_payment / monthly_income * 100
back_end_dti = (max_monthly_housing_payment + monthly_debts) / monthly_income * 100
debt_payoff_to_unlock_more = max(0, front_allowed - back_allowed)
down_payment_share = down_payment / max_home_price * 100
Mini-example
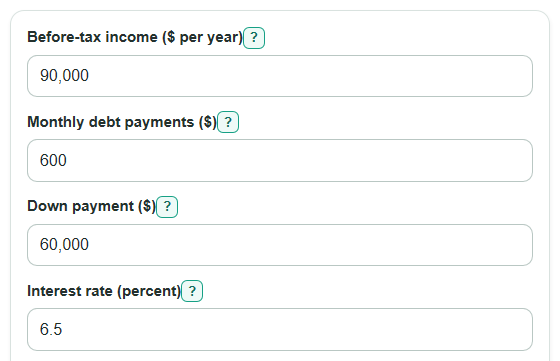
With $90,000 Before-tax income ($ per year), $600 Monthly debt payments ($), $60,000 Down payment ($), a 6.5% Interest rate (percent), a 30-year Loan term (years), 1.1% property tax, 0.35% homeowners insurance, $0 HOA dues, 0.5% mortgage insurance, a 28% Housing limit (percent of income), and a 36% Total debt limit (percent of income), monthly income is $7,500. The housing limit allows $2,100 per month, and the total debt limit also leaves $2,100 for housing after the $600 debt payment. The estimated home price is about $315,170, the estimated loan amount is about $255,170, and the monthly housing cost at that price is $2,100. Both DTI limits cap the estimate in this example.