
Estimate your monthly loan payment, fee-adjusted APR, and starting cash after choosing how one-time loan fees are charged.
Table of contents
How to use our Loan Payment with Fees Calculator
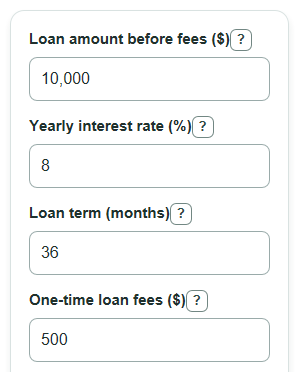
- Enter the Loan amount before fees from the loan offer, not the cash you hope to keep after fees.
- Enter the Yearly interest rate and Loan term in months. A 3-year loan is 36 months.
- Enter One-time loan fees, then choose How the fee is charged: added to the loan, paid upfront, or taken out of the loan money.
- Click Calculate and compare Monthly payment after fees with Fee-adjusted APR. A higher fee-adjusted APR means the fees make the loan more expensive than the stated rate alone suggests.
- Sanity-check Net cash after starting fees and Cash needed at the start against the lender offer. If those do not match the paperwork, change How the fee is charged before comparing loans.
Definitions
Loan amount before fees: The stated loan amount before any one-time fee is added, paid separately, or taken out.
Yearly interest rate: The stated annual rate used to calculate the scheduled monthly payment before the calculator adds the fee effect.
One-time loan fees: Fees charged once at the start of the loan, such as origination or processing fees.
How the fee is charged: The fee treatment. The fee can be added to the balance, paid upfront, or deducted from the loan money.
Monthly payment after fees: The fixed monthly payment based on the balance that must be repaid.
Fee-adjusted APR: A yearly cost rate that uses the payment schedule and counts the selected starting fee effect.
Net cash after starting fees: The effective cash available at the start after the selected fee treatment is counted.
Total borrowing cost above cash received: Total monthly payments minus Net cash after starting fees.
Common mistakes and quick fixes
Mistake: Entering the cash you want to receive as Loan amount before fees when the lender deducts fees.
Fix: Enter the stated Loan amount before fees, then use How the fee is charged to choose the deducted-fee option.
Mistake: Leaving Yearly interest rate blank because the loan is advertised as 0% or because fees are the main cost.
Fix: Enter 0 for Yearly interest rate only when the stated interest rate is truly 0%.
Mistake: Typing years into Loan term instead of months.
Fix: Convert years to months first, such as 5 years = 60 for Loan term.
Mistake: Putting monthly charges into One-time loan fees.
Fix: Use One-time loan fees only for fees charged once at the start, such as origination, processing, or closing fees.
Mistake: Comparing only Monthly payment after fees and ignoring Fee-adjusted APR.
Fix: Use Fee-adjusted APR to compare offers with different fee setups, especially when one loan has a lower stated rate but higher fees.
Mistake: Ignoring Net cash after starting fees when the fee is paid upfront or deducted.
Fix: Check Net cash after starting fees to make sure the loan provides enough cash for your actual need.
Limitations & Key Assumptions / Boundary Conditions
- The calculator assumes fixed monthly payments and a fixed Yearly interest rate for the full Loan term.
- Fee-adjusted APR is an estimate based on the selected one-time fee treatment and monthly payment schedule. A lender's official APR may use rules, rounding, or included charges that differ from this simplified model.
- Only one-time starting fees are included. Ongoing fees, late fees, insurance, taxes, prepayment penalties, and skipped payments are not included.
- The calculator does not model extra payments, changing payment dates, interest that compounds on a different schedule, or variable-rate loans.
- For paid upfront and deducted fees, One-time loan fees must be less than Loan amount before fees so Net cash after starting fees stays positive.
- Total interest paid is interest on the balance used for payments. It does not add the fee again.
Methodology
How the payment balance is chosen
The calculator first decides which balance interest is charged on. Financed fees increase the balance. Upfront and deducted fees do not increase the scheduled loan balance.
If How the fee is charged = Add fee to loan: payment balance = Loan amount before fees + One-time loan fees.
If How the fee is charged = Pay fee upfront or Take fee out of loan money: payment balance = Loan amount before fees.
How starting cash is counted
Fees can change how much cash the borrower effectively has at the start. This is important because fees can factor into the overall cost of a loan along with interest [2].
If How the fee is charged = Add fee to loan: net cash = Loan amount before fees.
If How the fee is charged = Pay fee upfront or Take fee out of loan money: net cash = Loan amount before fees - One-time loan fees.
Monthly payment formula
The calculator converts the yearly rate to a monthly rate by dividing by 12 months per year.
monthly rate = Yearly interest rate / 100 / 12.
If monthly rate = 0: monthly payment = payment balance / Loan term.
If monthly rate is above 0: monthly payment = payment balance * monthly rate / (1 - (1 + monthly rate)^(-Loan term)).
Total cost formulas
The total fields use the fixed payment and the number of months. Total borrowing cost compares payments with the cash effectively received, so it counts the fee effect without adding the fee twice.
Total paid in monthly payments = Monthly payment after fees * Loan term.
Total interest paid = Total paid in monthly payments - payment balance.
Total borrowing cost above cash received = Total paid in monthly payments - Net cash after starting fees.
Cash needed at the start = One-time loan fees if the fee is paid upfront; otherwise 0.
Fee-adjusted APR solve
The calculator finds the monthly rate that makes the net cash equal to the present value of the monthly payments, then converts that monthly rate to a yearly percent. This is similar to an internal-rate-style cash flow calculation, where fees are part of the effective borrowing cost [3].
Net cash after starting fees = Monthly payment after fees * (1 - (1 + fee monthly rate)^(-Loan term)) / fee monthly rate.
Fee-adjusted APR = fee monthly rate * 12 * 100.
When the implied rate is not directly available from the formula, the calculator uses a numeric search. If the starting cash is not positive, the APR is not calculated because the rate solve would not describe a normal loan cash flow.
Mini-example
For a $10,000 loan, 8% Yearly interest rate, 36-month Loan term, and $500 fee added to the loan, the payment balance is $10,500 and net cash is $10,000. The Monthly payment after fees is about $329.03. Total paid in monthly payments is about $11,845.16, Total interest paid is about $1,345.16, Total borrowing cost above cash received is about $1,845.16, and the Fee-adjusted APR is about 11.35%.