
Estimate a land contract payment, balloon balance, and monthly cash needed after optional taxes, insurance, and other recurring costs.
Advanced options
Table of contents
How to use our Land Contract Calculator
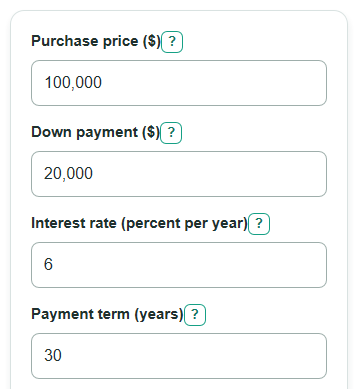
- Enter the Purchase price and Down payment using dollar amounts, not a down payment percent.
- Enter the Interest rate as the yearly percent from the contract, then enter the Payment term in whole years.
- Enter Contract payoff due after in whole years; use the same number as Payment term if the balance is paid off by the final scheduled payment.
- Open Advanced options if you want Monthly cash needed with extra costs to include Property tax, Insurance, or Other monthly costs.
- Check that Monthly principal-and-interest payment is lower than Monthly cash needed with extra costs when extra costs are entered, and that Estimated balloon balance due is $0.00 only when the payoff date reaches the full payment term.
Definitions
Land contract: A seller-financed purchase where the buyer usually pays the seller over time instead of getting a normal mortgage from a bank.
Amount financed after down payment: The Purchase price minus the Down payment. This is the starting balance used for the payment math.
Monthly principal-and-interest payment: The scheduled loan payment before Property tax, Insurance, and Other monthly costs.
Payment term: The number of years used to spread out the payments. A longer term usually lowers the monthly principal-and-interest payment but can leave a larger balance at an earlier payoff date.
Estimated balloon balance due: The remaining principal that must be paid at the contract payoff date. The CFPB describes a balloon payment as a larger payment due at the end of a loan [1].
Monthly extra costs included: Property tax plus Insurance plus Other monthly costs. These costs help with budgeting, but they do not pay down the contract balance.
Common mistakes and quick fixes
Mistake: Entering a down payment percent in Down payment.
Fix: Enter the actual dollar amount in Down payment, such as 20000 for a $20,000 down payment.
Mistake: Treating Monthly principal-and-interest payment as the full monthly budget.
Fix: Use Monthly cash needed with extra costs if Property tax, Insurance, or Other monthly costs apply.
Mistake: Setting Contract payoff due after greater than Payment term.
Fix: Make Contract payoff due after the same as or less than Payment term.
Mistake: Entering yearly taxes in Property tax.
Fix: Divide the yearly tax by 12 before entering Property tax because the label is $ per month.
Mistake: Using a blank Interest rate because the contract has no interest.
Fix: Enter 0 in Interest rate for a zero-interest contract.
Limitations & Key Assumptions / Boundary Conditions
- The calculator assumes fixed monthly payments, a fixed yearly interest rate, and monthly compounding based on the entered Payment term.
- Payment term and Contract payoff due after must be positive whole years. It does not handle partial-year payoff dates.
- Property tax, Insurance, and Other monthly costs are budget add-ons only. They do not reduce principal or interest.
- Estimated balloon balance due is a math estimate, not a legal payoff quote. Real payoff amounts can include late fees, recording fees, attorney fees, escrow adjustments, or seller-specific terms.
- The calculator does not test whether a land contract is allowed, enforceable, or financeable in a specific state or situation.
- If the contract has irregular payments, interest-only periods, skipped payments, changing rates, or extra principal payments, the outputs can differ from the real schedule.
Methodology
Calculation steps
The calculator first subtracts Down payment from Purchase price to get the starting principal.
principal = purchase_price - down_payment_amount
It converts the yearly Interest rate to a monthly decimal rate.
monthly_rate = (annual_interest_rate / 100) / 12
It converts the whole-year Payment term and Contract payoff due after values to month counts.
term_months = payment_term_years * 12
balloon_months = balloon_due_years * 12
For a 0 percent interest rate, the principal-and-interest payment is principal divided by the number of term months.
payment = principal / term_months
For an interest rate above 0, it uses the standard fixed-payment loan formula.
payment = principal * monthly_rate / (1 - (1 + monthly_rate)^(-term_months))
The balloon balance is the unpaid principal at the payoff month. For a 0 percent rate, it subtracts the scheduled principal payments already made.
balance = principal - payment * balloon_months
For an interest rate above 0, it calculates the present value of the remaining scheduled payments after the payoff month.
balance = payment * (1 - (1 + monthly_rate)^(-(term_months - balloon_months))) / monthly_rate
Interest paid before payoff is the scheduled payments made through the payoff date minus the principal that was paid down.
interest_paid = payment * balloon_months - (principal - balance)
Monthly extra costs are added for budgeting only.
monthly_extra_costs = property_tax_monthly + insurance_monthly + other_monthly_costs
monthly_cash_needed = payment + monthly_extra_costs
cash_paid_before_balloon = monthly_cash_needed * balloon_months
Mini-example
For a $100,000 Purchase price, $20,000 Down payment, 6 percent Interest rate, 30-year Payment term, and payoff due after 5 years, the amount financed is $80,000. The monthly principal-and-interest payment is about $479.64, and the estimated balloon balance due after 60 payments is about $74,443.49. If Property tax is $150 per month and Insurance is $50 per month, Monthly extra costs included is $200.00, so Monthly cash needed with extra costs is about $679.64.