
Compare staying on your current card with a balance transfer using your payment, fee, intro time, and APR.
Table of contents
How to use our Credit Card Interest Savings Calculator
- Enter the Balance to move and the Monthly payment you can make. Use the same payment you expect to make every month.
- Enter the Current card APR, the 0% intro time, the Balance transfer fee, and the After-intro APR from the new card offer.
- Select Calculate, then read Total cost saved after transfer fee first. A positive amount means the transfer saves money; a negative amount means it costs more.
- Check Break-even month and both payoff times. If the payoff happens before the break-even month, the fee may not be worth it.
- Sanity-check the result by asking if the payment is realistic for your budget and if the 0% intro time matches the exact offer terms.
Definitions
APR: Annual percentage rate, the yearly interest rate on a credit card. The calculator turns APR into a monthly rate by dividing by 12.
0% intro time: The number of months the transfer card charges no interest before the After-intro APR starts.
Balance transfer fee: The fee charged to move the balance, entered as a percent of the Balance to move.
Total cost saved after transfer fee: Interest avoided on the current card minus interest on the transfer card minus the transfer fee.
Break-even month: The first month when the interest saved is at least as large as the transfer fee.
Payoff time: The number of monthly payments needed to bring the balance to zero, with the final payment allowed to be smaller.
Common mistakes and quick fixes
Mistake: Using your credit limit instead of the actual Balance to move.
Fix: Enter only the dollar amount you plan to transfer.
Mistake: Entering a best-case payment in Monthly payment you can make that you cannot repeat every month.
Fix: Use the steady payment you can afford, because both payoff paths use that same amount.
Mistake: Swapping Current card APR and After-intro APR.
Fix: Put your old card rate in Current card APR and the new card's later rate in After-intro APR.
Mistake: Typing 12 in 0% intro time when the offer is 12 billing cycles but one cycle has already passed.
Fix: Enter the remaining number of 0% months you will actually have after the transfer posts.
Mistake: Leaving Balance transfer fee at 0 because the promo APR is 0%.
Fix: Enter the fee percent from the offer so Total cost saved after transfer fee includes that cost.
Mistake: Ignoring Payment warning and trusting the savings number anyway.
Fix: Raise Monthly payment you can make or lower Balance to move until the calculator can find a real payoff path.
Limitations & Key Assumptions / Boundary Conditions
- The calculator uses a monthly interest model. Many credit cards use daily balance methods, so real statements can differ by a small amount.
- It assumes you make the same Monthly payment you can make in both plans until the balance is paid off.
- The Balance transfer fee is added to the transfer starting balance for payoff timing and is also counted as a cost in Total cost saved after transfer fee.
- It does not include new purchases, late fees, annual fees, penalty APRs, rewards, minimum payment rules, or lost grace periods.
- If the monthly payment cannot lower a balance in an interest-charging phase, the calculator shows Payment warning instead of an impossible payoff comparison.
- The payoff search stops at 600 months. Results that need longer than that should be treated as not workable for planning.
Methodology
How the comparison is calculated
The calculator runs two month-by-month payoff paths. One path keeps the debt on the current card. The other path moves the balance, adds the transfer fee to the starting transfer balance, uses 0% interest during the intro period, and then uses the After-intro APR.
monthly_rate = apr_percent / 100 / 12
transfer_fee = balance_to_transfer * transfer_fee_percent / 100
current_month_interest = current_balance * current_monthly_rate
if balance + interest <= monthly_payment, payoff stops in that month
else next_balance = balance + interest - monthly_payment
transfer_start_balance = balance_to_transfer + transfer_fee
transfer_rate = 0 during intro months; after that, post_intro_apr / 100 / 12
net_cost_saved_after_fee = current_card_interest - transfer_plan_interest - transfer_fee
break_even_month = first month where cumulative_current_interest - cumulative_transfer_interest >= transfer_fee
Worked mini-example
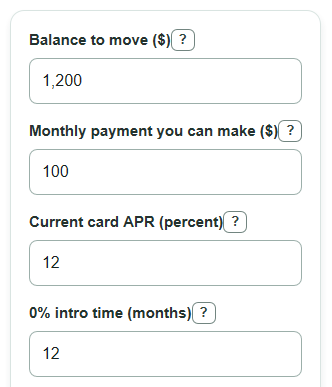
Suppose the Balance to move is $1,200, the Monthly payment you can make is $100, the Current card APR is 12%, the 0% intro time is 12 months, the Balance transfer fee is 3%, and the After-intro APR is 12%. The fee is $36, so the transfer payoff path starts at $1,236. The current card payoff path pays about $84.78 in interest. The transfer path pays about $0.36 in interest because only $36 remains after the 12 intro months. Total cost saved after transfer fee is $84.78 - $0.36 - $36 = $48.42. The break-even month is 4 because cumulative interest avoided has caught up with the $36 fee by then.
How to read negative savings
The savings result is signed. If Total cost saved after transfer fee is positive, the transfer plan costs less than staying. If it is negative, the transfer plan costs more after counting the fee and transfer-card interest.