
Compare buying a house now with waiting by entering today's price, expected rent, future rate, and future price change.
Table of contents
How to use our Buy a House Now or Wait Calculator
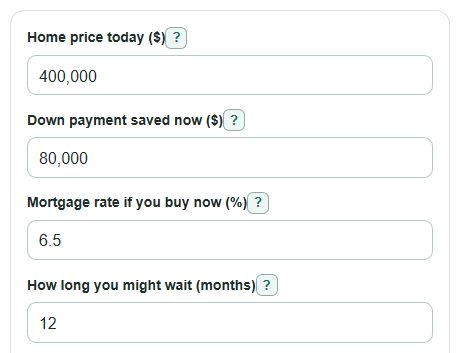
- Enter Home price today ($), Down payment saved now ($), Mortgage rate if you buy now (%), and Loan term (years).
- Enter How long you might wait (months), Home price change by then (%), Mortgage rate if you wait (%), and Rent while waiting ($ per month).
- Open Advanced options if you want to change property tax, insurance, maintenance, HOA, closing costs, selling costs, cash return, or Extra saving while waiting ($ per month).
- Click Calculate, then read Money ahead by buying now first. A positive amount means buying now is ahead; a negative amount means waiting is ahead.
- Sanity-check the result by comparing Payment if you buy now, Payment if you wait, and Future rate needed to match today's payment. If one assumption feels guessed, rerun the calculator with a higher and lower value.
Definitions
Principal and interest: The loan payment part that pays down the mortgage balance and pays the lender interest. It does not include taxes, insurance, maintenance, or HOA fees.
Loan term: The scheduled length of the mortgage in years, such as 30, 20, or 15 years.
Future home value: The estimated home price after the wait period, based on Home price today ($) and Home price change by then (%).
Owner carrying costs: Ongoing costs of owning during the wait period, including property tax, home insurance, maintenance, and HOA fees.
Buyer closing costs: One-time costs paid to complete the home purchase, separate from the down payment.
Selling cost: An optional estimated cost if you had to sell the home at the comparison date.
Saved cash available: Down payment saved now, estimated cash growth, and extra monthly saving after the wait period.
Break-even future rate: The future mortgage rate that would make the later principal-and-interest payment match today's principal-and-interest payment.
Common mistakes and quick fixes
Mistake: Entering Mortgage rate if you buy now (%) as a monthly rate instead of an annual rate.
Fix: Use the yearly fixed mortgage rate, such as 6.5 for 6.5% per year.
Mistake: Putting a yearly rent total in Rent while waiting ($ per month).
Fix: Enter one month's rent, such as 2,200, because the calculator multiplies it by How long you might wait (months).
Mistake: Treating Home price change by then (%) as an annual growth rate.
Fix: Enter the total expected change over the whole wait period, such as 3 for a 3% higher price after the wait.
Mistake: Setting Down payment saved now ($) higher than Home price today ($).
Fix: Lower the down payment or raise the home price so the buy-now loan amount is not negative.
Mistake: Leaving Property tax (% of home price per year), Maintenance (% of home price per year), or Buyer closing costs (% of home price) at defaults when you know local numbers.
Fix: Replace defaults with your own estimate, quote, or local tax rate before trusting Money ahead by buying now.
Mistake: Reading Change in loan payment if you wait as total housing cost.
Fix: Use it only for principal and interest. Taxes, insurance, maintenance, and HOA are counted separately in Cost of buying now during the wait period.
Limitations & Key Assumptions / Boundary Conditions
- The calculator compares a numeric buy-now path with a numeric wait path. It does not decide if you are personally ready to buy.
- Mortgage rates, home prices, rent, taxes, insurance, and maintenance can all differ from your estimate. Small rate or price changes can move the answer by thousands of dollars.
- Home price change by then (%) is treated as one total change over the wait period, not an annual growth rate.
- Principal is treated as equity, not a cost. Interest, rent, owner carrying costs, closing costs, and optional selling costs are treated as unrecoverable costs.
- Future loan amount is floored at $0 if saved cash exceeds the future home value. That prevents an impossible negative mortgage.
- The break-even future rate is searched only from 0% to 25%. If no rate in that range matches today's payment, the calculator shows N/A.
- The model does not include income taxes, mortgage points, PMI, rent deposits, moving costs, appraisal gaps, refinance costs, investment risk, or changes in your income.
- Default property tax, maintenance, and closing cost values are starter assumptions only. Replace them with local estimates when possible.
Methodology
Core mortgage math
The calculator uses a fixed-rate amortized mortgage model. On a typical fixed-rate loan, the combined principal and interest payment stays the same, but the split between principal and interest changes over time [3].
loan_amount_now = home_price_now - down_payment_now
monthly_rate = annual_rate_percent / 100 / 12
term_months = loan_term_years * 12
payment = loan_amount * monthly_rate / (1 - (1 + monthly_rate)^(-term_months))
If the mortgage rate is 0%, the payment is calculated as the loan amount divided by term months.
payment = loan_amount / term_months
Buy-now path
The buy-now path estimates what happens between today and the end of the wait period if you buy now. The future home value uses the entered total price change.
future_home_value = home_price_now * (1 + future_price_change_percent / 100)
The remaining balance after the wait period is based on the scheduled mortgage payment. If the wait period is longer than the mortgage term, the remaining balance is capped at $0.
balance = loan_amount * (1 + monthly_rate)^wait_months - payment * (((1 + monthly_rate)^wait_months - 1) / monthly_rate)
If the mortgage rate is 0%, the balance is calculated by subtracting scheduled principal payments.
balance = loan_amount - payment * wait_months
Interest paid is total payments made minus principal paid. Owner carrying costs include property tax, home insurance, maintenance, and HOA fees. Buyer closing costs are a one-time purchase cost, and mortgage cost categories are commonly shown on a loan estimate [1].
interest_paid = payment * months_paid - (loan_amount_now - remaining_balance)
owner_carrying_costs = property_tax + home_insurance + maintenance + HOA
buy_now_net_cost = interest_paid + owner_carrying_costs + buyer_closing_costs + selling_costs - (future_home_value - home_price_now)
Wait path
The wait path counts rent during the wait and subtracts estimated growth on saved cash. Extra saving is not treated as a cost because it remains your money.
monthly_cash_return = cash_return_percent / 100 / 12
cash_available_after_wait = down_payment_now * (1 + monthly_cash_return)^wait_months + extra_saving_monthly * (((1 + monthly_cash_return)^wait_months - 1) / monthly_cash_return)
If the cash return is 0%, saved cash is calculated without compounding.
cash_available_after_wait = down_payment_now + extra_saving_monthly * wait_months
investment_gain_on_saved_cash = cash_available_after_wait - down_payment_now - extra_saving_monthly * wait_months
wait_net_cost = rent_monthly * wait_months - investment_gain_on_saved_cash
The later loan amount uses saved cash against the future home value and cannot go below $0.
future_loan_amount = max(0, future_home_value - cash_available_after_wait)
Main comparison
Money ahead by buying now is a signed result. Positive means buying now has the lower modeled cost. Negative means waiting has the lower modeled cost.
now_vs_wait_advantage = wait_net_cost - buy_now_net_cost
Change in loan payment if you wait compares principal and interest only.
monthly_pi_change = future_monthly_pi - current_monthly_pi
Future rate needed to match today's payment is found by bisection from 0% to 25%. Mortgage rates can change over time, so this is a sensitivity check, not a forecast [2].
monthly_payment(future_loan_amount, break_even_rate, term_months) = current_monthly_pi
Worked mini-example
Using the default example, Home price today ($) is $400,000, Down payment saved now ($) is $80,000, Mortgage rate if you buy now (%) is 6.5%, How long you might wait (months) is 12, Home price change by then (%) is 3%, Mortgage rate if you wait (%) is 6.0%, and Rent while waiting ($ per month) is $2,200. With the default advanced assumptions, Payment if you buy now is about $2,022.62 per month and Payment if you wait is about $1,975.92 per month. Cost of buying now during the wait period is about $30,894.69, Cost of waiting is about $23,966.72, and Money ahead by buying now is about -$6,927.97. The negative sign means the wait path is ahead in that scenario.