
Estimate first-year rental property depreciation, building basis, land excluded, and a year-by-year schedule from your purchase and service date.
Table of contents
How to use our Rental Property Depreciation Calculator
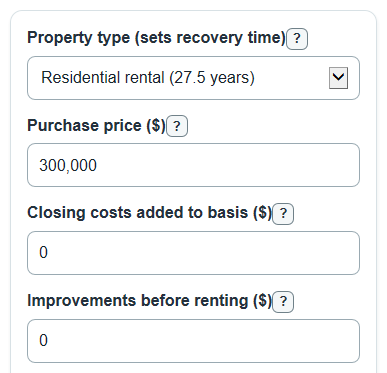
- Choose Property type (sets recovery time) so the calculator uses either 27.5 years for residential rental or 39 years for commercial real property.
- Enter Purchase price ($), plus only the Closing costs added to basis ($) and Improvements before renting ($) that should be part of tax basis.
- Choose How do you want to enter land?, then fill in either Land share (percent) or Land value ($). Land is separated because it is not depreciated.
- Enter the Placed in service month and Placed in service year for the date the property was ready and available to rent, then click Calculate.
- Sanity-check the output: Depreciable building basis should equal total basis minus Land amount not depreciated, and the first-year amount should usually be lower than the regular full-year amount unless service began in January.
Definitions
Basis before land: Purchase price plus the entered closing costs added to basis and improvements before renting.
Land amount not depreciated: The part of the property basis assigned to land. Land is excluded from this depreciation estimate.
Depreciable building basis: The building portion of basis after land is removed. This is the amount spread over the recovery time.
Placed in service: The point when the property is ready and available to rent, even if it is not yet occupied [1].
Recovery time: The period used to spread real property depreciation, shown as 27.5 years for residential rental or 39 years for commercial real property.
Mid-month rule: A timing rule that treats real property as placed in service in the middle of the month, so the first and final tax years are partial.
Accumulated depreciation: The total depreciation shown in the schedule through the end of that tax year.
Common mistakes and quick fixes
Mistake: Putting the whole Purchase price ($) into the building amount and ignoring land.
Fix: Use How do you want to enter land? and fill in Land share (percent) or Land value ($) so Land amount not depreciated is excluded.
Mistake: Using the purchase month for Placed in service month when the property was not ready to rent yet.
Fix: Enter the month the property was ready and available for rent, because that month controls the First tax-year depreciation deduction .
Mistake: Adding loan points, prepaid insurance, or escrow deposits to Closing costs added to basis ($) .
Fix: Enter only costs that increase the property's tax basis, and use 0 if none apply.
Mistake: Including normal repairs in Improvements before renting ($) .
Fix: Use this field for major work added before the property was ready to rent, such as a remodel, not ordinary repair expenses.
Mistake: Choosing the wrong Property type (sets recovery time) and then trusting the full schedule.
Fix: Pick residential rental for dwelling units and commercial real property for nonresidential real estate before reading the Year-by-year depreciation schedule .
Limitations & Key Assumptions / Boundary Conditions
- This is an estimate for straight-line real property depreciation using the selected recovery time and mid-month timing. It does not prepare a tax return.
- The calculator treats Closing costs added to basis ($) and Improvements before renting ($) as valid basis additions. If an entered cost should be deducted, amortized, or excluded, the result will differ.
- The land split is only as accurate as the Land share (percent) or Land value ($) you enter. Assessment records, appraisals, or closing documents may use different allocations.
- The schedule assumes a calendar tax year and does not handle short tax years, partial dispositions, conversions between personal and rental use, bonus depreciation, Section 179, listed property rules, or recapture on sale.
- Displayed dollar amounts are rounded. The final schedule row may be adjusted by a small rounding amount so the displayed accumulated depreciation equals the displayed depreciable basis.
- State tax rules, local rules, and tax software settings can differ from this simple federal-style estimate.
Methodology
Calculation steps
The calculator first builds total property basis before land from the purchase price and the basis additions you enter.
basis_before_land = purchase_price + closing_costs_added + capital_improvements
Next, it separates land. If you choose the percent method, the percent is applied to basis before land. If you choose the dollar method, the entered land value is used.
land_amount = basis_before_land * land_percent / 100
or land_amount = land_value
The depreciable building basis is the amount left after land is removed.
depreciable_basis = basis_before_land - land_amount
The selected property type sets the recovery period. Residential rental uses 27.5 years. Commercial real property uses 39 years. The calculator converts that recovery time to months and uses straight-line monthly depreciation.
recovery_months = recovery_years * 12
monthly_depreciation = depreciable_basis / recovery_months
For the first calendar tax year, the calculator applies mid-month timing. A property placed in service in month 1 gets 11.5 months for that first year, month 7 gets 5.5 months, and month 12 gets 0.5 month. Federal regulations treat depreciation as beginning when property is placed in service and allow proportionate depreciation for partial years [1].
first_year_months = 12 - placed_in_service_month + 0.5
first_year_depreciation = monthly_depreciation * first_year_months
Schedule method
The first schedule row uses the first-year months. Later rows use up to 12 months at a time until the recovery months are used up. The final row may be a partial year.
row_depreciation = monthly_depreciation * min(12, remaining_months)
schedule_years = number of calendar tax years with depreciation
The table shows each tax year, depreciation for that year, accumulated depreciation, and remaining building book value. Calculations use unrounded monthly amounts; displayed dollars are rounded for readability.
Mini-example
Suppose a residential rental property has a $300,000 purchase price, $6,000 of closing costs added to basis, $14,000 of improvements before renting, a 20 percent land share, and a July 2024 placed-in-service month. Basis before land is $320,000. Land is $64,000. Depreciable building basis is $256,000. Monthly depreciation is $256,000 / 330 months = about $775.76. July service gives 5.5 first-year months, so the first tax-year depreciation deduction is about $4,266.67. A regular full tax year is about $9,309.09, before the final partial year and rounding adjustment.