
Estimate 1031 exchange tax deferral, taxable boot, adjusted basis, and reinvestment targets from your sale details and tax-rate assumptions.
Advanced options
Table of contents
How to use our 1031 Exchange Calculator
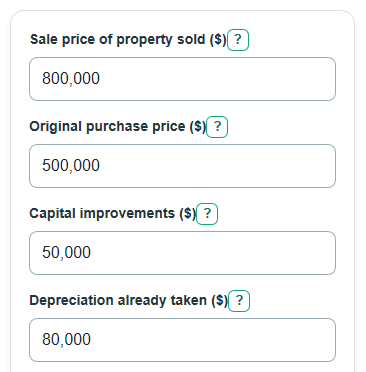
- Enter Sale price of property sold, Original purchase price, Capital improvements, Depreciation already taken, and Federal long-term gain tax rate.
- Open Advanced options if you want to add Selling costs, Loan payoff at sale, Cash or other taxable boot received, or a different Depreciation recapture tax rate.
- Use Include a state tax estimate? only if you want the calculator to apply your State tax rate to apply to the gain estimate.
- Click Calculate and read Estimated taxes deferred by the exchange first, then review Estimated tax due from taxable boot and Estimated tax if sold without an exchange.
- Sanity-check the output by comparing Adjusted tax basis before sale with your tax records and making sure any taxable boot or state tax setting matches your planning scenario.
Definitions
Adjusted tax basis before sale: Original purchase price plus Capital improvements minus Depreciation already taken.
Estimated taxable gain from the sale: Net sale price minus adjusted tax basis. The calculator uses zero for tax math when this gain is negative.
Depreciation already taken: The depreciation deductions claimed for the property in past tax years. Depreciation lowers basis.
Gain treated as depreciation recapture: The part of gain matched to prior depreciation, limited by the total positive gain.
Cash or other taxable boot received: Cash, debt relief, or other non-like-kind value received in an exchange that may create current taxable gain.
Estimated taxes deferred by the exchange: Estimated tax from a taxable sale minus estimated tax due from taxable boot.
Replacement property price target for full deferral: Net sale price after Selling costs. It is a planning target for replacement property value.
Common mistakes and quick fixes
Mistake: Entering Sale price of property sold after subtracting commissions or loan payoff.
Fix: Use the contract sale price, then put commissions and closing costs in Selling costs and the mortgage balance in Loan payoff at sale.
Mistake: Putting repairs in Capital improvements or leaving out real capital additions.
Fix: Use Capital improvements only for costs that were added to basis, such as major additions or upgrades, not normal repairs.
Mistake: Guessing Depreciation already taken instead of using tax records.
Fix: Enter the total depreciation deductions already claimed for the property, because this changes Adjusted tax basis before sale and Gain treated as depreciation recapture.
Mistake: Leaving Federal long-term gain tax rate or Depreciation recapture tax rate blank.
Fix: Enter a rate from 0 to 100 for each percent field you use; the calculator does not choose your tax bracket.
Mistake: Turning on Include a state tax estimate? but forgetting to check State tax rate to apply.
Fix: Choose Yes only when you want a state estimate, then enter the state rate you want applied to taxable gain.
Mistake: Entering Cash or other taxable boot received as the full sale proceeds.
Fix: Enter only cash, debt relief, or other non-like-kind value that may be taxable in the exchange.
Limitations & Key Assumptions / Boundary Conditions
- This is a planning estimate for a 1031 exchange. It does not decide whether your property, timing, exchange structure, or taxpayer qualifies under Section 1031.
- The calculator uses the tax rates you enter. It does not choose federal brackets, apply income limits, calculate the net investment income tax, or look up state rules.
- The state tax estimate is optional and simplified. If Include a state tax estimate? is No, State tax rate to apply is ignored.
- Depreciation recapture is simplified by applying the Depreciation recapture tax rate to gain matched with Depreciation already taken.
- Taxable boot is simplified by applying recognized gain first to depreciation recapture, then to other gain.
- Replacement property and cash reinvestment targets are based on net sale value and debt payoff. Real exchange planning can also depend on debt replacement, exchange expenses, and closing details.
- If Selling costs exceed Sale price of property sold, or Loan payoff at sale exceeds net sale price, the calculator keeps the signed result so you can spot the issue instead of hiding it.
Methodology
Core sale math
The calculator starts with adjusted basis, then subtracts basis from the net sale price to estimate gain. Section 1031 applies to qualifying like-kind exchanges of real property, but this calculator only estimates the dollar effect of the exchange from the entries you provide [1].
adjusted_basis = purchase_price + improvements - depreciation_taken
net_sale_price = sale_price - selling_costs
realized_gain = net_sale_price - adjusted_basis
positive_gain = max(realized_gain, 0)
Recapture and other gain
Positive gain is split into a depreciation recapture part and an other gain part. The depreciation recapture part is limited to both prior depreciation and total positive gain.
recapture_gain_full = min(max(depreciation_taken, 0), positive_gain)
other_gain_full = max(positive_gain - recapture_gain_full, 0)
Tax if there were no exchange
The taxable-sale comparison applies the Depreciation recapture tax rate to recapture gain, the Federal long-term gain tax rate to other gain, and the optional state rate to total positive gain.
state_rate_effective = state_tax_rate when include_state_tax is yes, otherwise 0
full_state_tax = positive_gain * state_rate_effective / 100
full_sale_tax_if_no_exchange = recapture_gain_full * recapture_rate / 100 + other_gain_full * federal_ltcg_rate / 100 + full_state_tax
Boot and deferred tax
Boot is limited to the positive gain for the current-tax estimate. Recognized gain is applied first to depreciation recapture, then to other gain.
recognized_gain_exchange = min(positive_gain, max(boot_received, 0))
recognized_recapture = min(recapture_gain_full, recognized_gain_exchange)
recognized_other = max(recognized_gain_exchange - recognized_recapture, 0)
exchange_state_tax = recognized_gain_exchange * state_rate_effective / 100
estimated_tax_due_from_boot = recognized_recapture * recapture_rate / 100 + recognized_other * federal_ltcg_rate / 100 + exchange_state_tax
total_tax_deferred_by_exchange = full_sale_tax_if_no_exchange - estimated_tax_due_from_boot
state_tax_deferred = full_state_tax - exchange_state_tax
Reinvestment targets
The replacement price target uses net sale price. The cash target subtracts Loan payoff at sale and can be negative when debt payoff is larger than net sale price.
replacement_price_target_for_full_deferral = net_sale_price
cash_to_reinvest_for_full_deferral = net_sale_price - debt_payoff
Worked mini-example
Suppose Sale price of property sold is $800,000, Original purchase price is $500,000, Capital improvements are $50,000, Depreciation already taken is $80,000, Selling costs are $40,000, Federal long-term gain tax rate is 15%, Depreciation recapture tax rate is 25%, no state tax is included, and Cash or other taxable boot received is $0. Adjusted tax basis before sale is $470,000. Net sale price is $760,000. Estimated taxable gain from the sale is $290,000. Gain treated as depreciation recapture is $80,000, and Other gain after depreciation recapture is $210,000. Estimated tax if sold without an exchange is $20,000 plus $31,500, or $51,500. With no boot, Estimated tax due from taxable boot is $0, so Estimated taxes deferred by the exchange is $51,500. If the same example includes a 5% state tax estimate, Estimated state tax deferred adds $14,500, making total estimated deferral $66,000.