
Estimate the gross yearly income needed to qualify for a target home price using mortgage costs, debts, PMI, HOA, and DTI limits.
Table of contents
How to use our Mortgage Income Needed Calculator
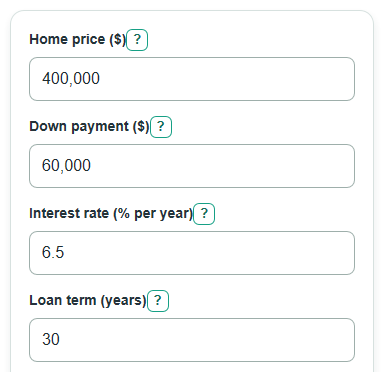
- Enter the Home price, Down payment, Interest rate, Loan term, and Other monthly debt payments.
- Open Advanced options if you want to change Property tax rate, Homeowners insurance, HOA or condo fee, PMI rate, Housing debt limit, or Total debt limit.
- Click Calculate and read Estimated gross income needed first; it is the higher of the housing-only and total-debt tests.
- Check Extra yearly income caused by PMI and HOA to see how much those two costs raise the income target.
- Sanity-check the output by comparing Estimated monthly housing payment with real quotes for taxes, insurance, HOA fees, and the mortgage rate you expect to get.
Definitions
Gross income: Income before taxes, retirement contributions, health insurance, and other paycheck deductions.
Debt-to-income ratio (DTI): The share of monthly gross income used for debt payments. Mortgage underwriting often compares monthly obligations with income [2].
Housing debt limit: The front-end DTI cap. It compares the new housing payment with gross monthly income.
Total debt limit: The back-end DTI cap. It compares the new housing payment plus Other monthly debt payments with gross monthly income.
PMI rate: Private mortgage insurance cost as a yearly percent of the loan. PMI is often tied to making a down payment below 20% [1].
HOA or condo fee: A monthly association fee paid for some homes, condos, co-ops, or planned communities.
Principal and interest: The fixed loan payment part that pays down the loan balance and pays the lender interest.
Common mistakes and quick fixes
Mistake: Entering closing costs in Down payment.
Fix: Use Down payment only for cash paid toward the Home price; closing costs are not included in Estimated loan amount.
Mistake: Putting the new mortgage payment in Other monthly debt payments.
Fix: Use Other monthly debt payments only for debts like car loans, student loans, and credit card minimums.
Mistake: Leaving Interest rate blank or typing a monthly rate.
Fix: Enter Interest rate as a yearly percent, such as 6.5 for 6.5% per year.
Mistake: Setting Property tax rate to a dollar amount.
Fix: Enter Property tax rate as a percent of Home price per year, not as an annual tax bill.
Mistake: Counting HOA or condo fee inside Other monthly debt payments.
Fix: Put it in HOA or condo fee so Estimated monthly housing payment and Extra yearly income caused by PMI and HOA stay clear.
Mistake: Using very high or zero values for Housing debt limit or Total debt limit.
Fix: Enter each DTI limit as a percent from above 0 to 100, such as 28 and 36.
Limitations & Key Assumptions / Boundary Conditions
- This is a planning estimate, not a mortgage approval. Lenders can use different DTI caps, credit rules, loan programs, reserves, and documentation standards.
- PMI is modeled as monthly borrower-paid PMI when Down payment is less than 20% of Home price. Some loans use different mortgage insurance rules or cancellation rules.
- Property tax rate uses a simple percent of Home price per year. Real tax bills can change because of local assessments, exemptions, reassessments, and special taxes.
- Homeowners insurance, HOA or condo fee, and PMI rate are user-entered estimates. Quotes for a specific property may be higher or lower.
- Estimated monthly housing payment does not include utilities, maintenance, repairs, closing costs, prepaid taxes, lender fees, points, or moving costs.
- The loan payment assumes a fixed-rate mortgage with level monthly principal and interest payments for the full Loan term.
- If Down payment equals Home price, the loan amount and principal-and-interest payment are zero, but taxes, insurance, HOA fees, and Other monthly debt payments can still require income.
Methodology
Calculation steps
The calculator first finds the Estimated loan amount from the Home price and Down payment.
loan_amount = home_price - down_payment
It then computes Monthly principal and interest using the standard fixed-rate mortgage payment formula. The monthly rate is the yearly Interest rate divided by 100 and then by 12. The number of payments is Loan term in years times 12.
if monthly_rate = 0, principal_and_interest = loan_amount / number_of_payments
if monthly_rate > 0, principal_and_interest = loan_amount * monthly_rate * (1 + monthly_rate)^number_of_payments / ((1 + monthly_rate)^number_of_payments - 1)
Next, it adds the housing-cost line items. Property tax and homeowners insurance are converted from yearly amounts to monthly amounts. PMI is added only when Down payment divided by Home price is less than 0.20.
monthly_tax = home_price * property_tax_rate / 100 / 12
monthly_insurance = annual_home_insurance / 12
monthly_pmi = loan_amount * annual_pmi_rate / 100 / 12 when down_payment / home_price < 0.20, otherwise 0
monthly_housing_payment = principal_and_interest + monthly_tax + monthly_insurance + monthly_hoa + monthly_pmi
The calculator runs two DTI tests. The housing debt test uses only the new housing payment. The total debt test adds Other monthly debt payments. The higher monthly income becomes the main answer.
front_income_monthly = monthly_housing_payment / (housing_debt_limit / 100)
back_income_monthly = (monthly_housing_payment + other_monthly_debt_payments) / (total_debt_limit / 100)
monthly_income_needed = max(front_income_monthly, back_income_monthly)
annual_income_needed = monthly_income_needed * 12
Extra yearly income caused by PMI and HOA is calculated by repeating the same income test with PMI and HOA set to zero, then subtracting that comparison income from the entered-scenario income.
effect = income_needed_with_entered_PMI_and_HOA - income_needed_with_PMI_0_and_HOA_0
The DTI shares at needed income show how close the final income is to each cap.
housing_debt_share = monthly_housing_payment / monthly_income_needed * 100
total_debt_share = (monthly_housing_payment + other_monthly_debt_payments) / monthly_income_needed * 100
Mini-example
For a $400,000 home, $60,000 down payment, 6.5% interest rate, 30-year loan, $500 in Other monthly debt payments, 1.1% Property tax rate, $1,600 yearly Homeowners insurance, $150 HOA or condo fee, 0.5% PMI rate, 28% Housing debt limit, and 36% Total debt limit, the Estimated monthly housing payment is about $2,940.70. The housing debt test needs about $126,029.98 per year, while the total debt test needs about $114,689.99 per year, so Estimated gross income needed is about $126,029.98 per year. In this example, PMI and HOA raise the yearly income target by about $12,500.