
Estimate your HELOC draw-period payment, end balance, repayment payment, payment jump, and remaining interest from your current balance.
Advanced options
Table of contents
How to use our HELOC Draw Period Calculator
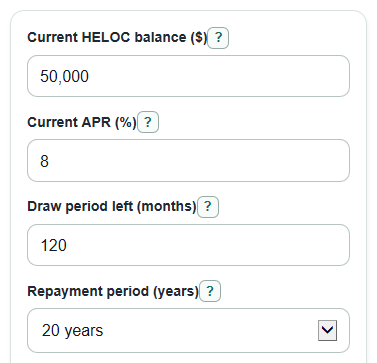
- Enter your Current HELOC balance ($), which is the amount already borrowed, not the full credit line.
- Enter the Current APR (%), the Draw period left (months), and the Repayment period (years).
- Open Advanced options if you want to test Extra principal during draw ($ per month), a different APR when repayment starts (%), or a Credit line limit ($).
- Select Calculate and compare the First draw-period payment with the First repayment-period payment and Payment change at repayment.
- Sanity-check the output: if extra principal is $0, the Balance when draw period ends should stay close to the current balance because no principal is being paid down.
Definitions
HELOC: A home equity line of credit, which lets a homeowner borrow against home equity up to a credit limit.
Draw period: The part of a HELOC when borrowing is allowed. Payments are often interest-only during this period.
Repayment period: The part after the draw period when the remaining balance is paid back over a set number of years.
APR: Annual percentage rate. In this calculator, APR is used as the yearly interest rate for monthly payment estimates.
Extra principal: Money paid above the interest due. It lowers the HELOC balance.
Principal-and-interest payment: A payment that covers monthly interest and also pays down the balance.
Payment change at repayment: The first repayment-period payment minus the first draw-period payment. Positive means higher; negative means lower.
Common mistakes and quick fixes
Mistake: Entering the full credit line in Current HELOC balance ($) instead of the amount borrowed.
Fix: Use only the outstanding balance you owe right now.
Mistake: Typing a monthly rate in Current APR (%) instead of the yearly APR.
Fix: Enter the annual percentage rate, such as 8 for 8% APR.
Mistake: Using the original draw period in Draw period left (months) after several years have already passed.
Fix: Enter the number of months remaining before repayment starts.
Mistake: Putting the required interest payment into Extra principal during draw ($ per month).
Fix: Enter only the amount paid above the interest due, because this is the part that lowers principal.
Mistake: Leaving APR when repayment starts (%) blank when you want to test a higher future rate.
Fix: Enter the possible repayment APR, or leave it blank only if you want to reuse the current APR.
Mistake: Reading a negative Payment change at repayment as an error.
Fix: A negative value means the estimated repayment payment is lower than the first draw-period payment shown.
Limitations & Key Assumptions / Boundary Conditions
- The calculator assumes no new draws are added after the current balance entered.
- The draw-period estimate uses the current APR for every remaining draw month, even though many HELOC rates can change.
- The repayment-period estimate uses APR when repayment starts (%) if entered; otherwise it uses Current APR (%).
- Extra principal is treated as the same amount each month during the draw period and is applied before the repayment period starts.
- The calculator does not include fees, rate caps, minimum-payment rules, late payments, escrow, taxes, insurance, or lender-specific rounding.
- If extra principal pays off the balance during the draw period, the repayment balance and repayment interest are shown as $0.
- The result is an estimate for planning. Your lender's billing statement controls the actual payment due.
Methodology
How the draw period is modeled
After a HELOC draw period ends, interest-only payments commonly stop and the loan moves to principal-and-interest repayment [1]. This calculator starts with the current balance and runs the remaining draw months one month at a time.
draw_monthly_rate = current_apr_percent / 100 / 12
interest_m = balance_start_m x draw_monthly_rate
principal_paid_m = min(extra_principal_monthly, balance_start_m)
payment_m = interest_m + principal_paid_m
balance_end_m = balance_start_m - principal_paid_m
The First draw-period payment is the first month's interest plus the extra principal entered. Draw-period interest is the total of all monthly interest amounts during the remaining draw months.
first_draw_payment = balance_drawn x draw_monthly_rate + min(extra_principal_monthly, balance_drawn)
How the repayment payment is found
When the draw period ends, the remaining balance is spread across the selected repayment period. The repayment APR uses APR when repayment starts (%) if that field is filled in; otherwise it uses Current APR (%).
repayment_months = repayment_years x 12
repayment_monthly_rate = repayment_apr_percent / 100 / 12
if repayment_monthly_rate = 0, first_repayment_payment = balance_at_draw_end / repayment_months
otherwise, first_repayment_payment = balance_at_draw_end x repayment_monthly_rate / (1 - (1 + repayment_monthly_rate)^(-repayment_months))
Repayment interest is the total of those repayment payments minus the balance that entered repayment.
payment_change_at_repayment = first_repayment_payment - first_draw_payment
repayment_interest_total = first_repayment_payment x repayment_months - balance_at_draw_end
total_interest_remaining = draw_interest_total + repayment_interest_total
Mini example
For a $50,000 balance, 8% current APR, 120 draw months left, 20 repayment years, and $0 extra principal, the monthly draw rate is 0.08 / 12, or about 0.006667. The first draw-period payment is $333.33, the balance when the draw period ends stays $50,000, the first repayment-period payment is about $418.22, and the payment change is about $84.89 higher per month.