
Estimate FHA upfront MIP, year-1 monthly MIP, and how financing the upfront fee changes your payment.
Table of contents
How to use our FHA Mortgage Insurance Calculator
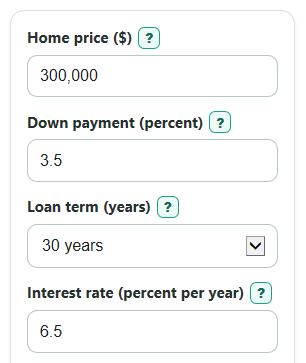
- Enter the Home price ($) before subtracting your down payment.
- Enter the Down payment (percent), choose the Loan term (years), and enter the Interest rate (percent per year).
- Choose Yes or No for Roll upfront MIP into the loan? to show whether the upfront fee is borrowed or paid in cash.
- Select Calculate and read Estimated monthly MIP in year 1 first, then compare Upfront MIP fee with Extra monthly payment from financing upfront MIP.
- Sanity-check the result: a smaller down payment usually raises the loan-to-value ratio, which can increase How long MIP is included and Estimated total FHA MIP if kept for required time.
Definitions
FHA MIP: FHA mortgage insurance premium. FHA loans can have an upfront premium and annual premiums that are usually paid monthly.
Upfront MIP fee: The one-time FHA mortgage insurance fee based on Base loan amount before upfront MIP. This calculator uses 1.75 percent for the covered standard forward purchase estimate [1].
Estimated monthly MIP in year 1: The first-year annual FHA insurance charge divided into monthly amounts, estimated from the scheduled base-loan balance.
Base loan amount before upfront MIP: Home price ($) minus the down payment. FHA MIP tiers use this amount before any financed upfront MIP is added.
Loan-to-value ratio: The Base loan amount before upfront MIP divided by Home price ($), shown as a percent. A higher value means a smaller down payment.
Basis points: A way to write small percent rates. One basis point is 0.01 percent, so 55 basis points is 0.55 percent.
How long MIP is included: The number of months the annual MIP is estimated to run, either 132 months or the selected loan term.
Common mistakes and quick fixes
Mistake: Entering the loan amount in Home price ($).
Fix: Use the purchase price in Home price ($); the calculator creates Base loan amount before upfront MIP from the down payment.
Mistake: Leaving Down payment (percent) blank or entering less than 3.5.
Fix: Enter a real percent of at least 3.5 and less than 100 for Down payment (percent).
Mistake: Reading Upfront MIP fee as the same thing as Estimated monthly MIP in year 1.
Fix: Treat Upfront MIP fee as the one-time insurance fee and Estimated monthly MIP in year 1 as the first-year monthly insurance estimate.
Mistake: Choosing Yes for Roll upfront MIP into the loan? and thinking the Extra monthly payment from financing upfront MIP is another MIP charge.
Fix: Read it as added principal and interest from borrowing the upfront fee, not as a second insurance bill.
Mistake: Using an old or guessed Interest rate (percent per year).
Fix: Enter the rate you want to test because it changes Principal, interest, and year-1 MIP and the scheduled balance used for MIP estimates.
Limitations & Key Assumptions / Boundary Conditions
- This is an estimate for a standard FHA forward purchase loan. It does not handle streamline refinances, special program exceptions, or case-number-specific rules.
- The calculator does not check county FHA loan limits, credit score, debt-to-income ratio, property eligibility, seller credits, or lender overlays.
- The annual MIP tier is picked from loan term, Base loan amount before upfront MIP, and original loan-to-value ratio. If FHA changes its MIP table, results can differ from a lender quote.
- Estimated total FHA MIP if kept for required time assumes no refinance, sale, payoff, recast, or extra principal payments before the MIP period ends.
- Principal, interest, and year-1 MIP leaves out property taxes, homeowners insurance, HOA dues, escrow changes, late charges, and other closing costs.
- The scheduled balance estimate uses the entered Interest rate (percent per year). A real loan can differ because of exact closing date, payment timing, rounding, and servicer rules.
Methodology
Inputs and starting loan amount
The calculator first turns Down payment (percent) into a dollar amount, then subtracts it from Home price ($) to get the base FHA loan amount. The financed upfront MIP is not included when the loan-to-value ratio is picked.
down_payment_amount = home_price * down_payment_percent / 100
base_loan_amount = home_price - down_payment_amount
ltv_percent = base_loan_amount / home_price * 100
Upfront MIP and loan balance
The upfront MIP is calculated as 1.75 percent of the Base loan amount before upfront MIP [4]. If Roll upfront MIP into the loan? is Yes, the fee is added to the loan balance. If it is No, the fee is shown as Upfront MIP paid in cash.
upfront_mip = base_loan_amount * 0.0175
total_loan_amount = base_loan_amount + upfront_mip if financed, otherwise base_loan_amount
Payment and scheduled balance
Monthly principal and interest uses the standard fixed-rate mortgage payment formula. If the entered interest rate is 0 percent, the payment is the loan amount divided by the number of months.
monthly_rate = annual_interest_rate / 100 / 12
monthly_payment = loan_amount * monthly_rate / (1 - (1 + monthly_rate)^(-term_months))
The calculator also computes a base-loan payment without financed upfront MIP. That base-loan schedule is used to estimate the balance before each MIP month.
balance_before_month_m = base_loan_amount * (1 + monthly_rate)^m - base_monthly_payment * ((1 + monthly_rate)^m - 1) / monthly_rate
Annual MIP rate and duration
The Annual MIP rate used is selected from the FHA tier using Loan term (years), Base loan amount before upfront MIP, and the original loan-to-value ratio. For terms over 15 years, loans at or below $726,200 use 50 basis points when loan-to-value is 95 percent or less and 55 basis points when it is above 95 percent; loans above $726,200 use 70 or 75 basis points. For terms of 15 years or less, the calculator uses the lower short-term FHA tiers. The MIP period is 132 months when the tier says 11 years, otherwise it is the full selected term.
annual_mip_rate = annual_mip_rate_bps / 10000
mip_duration_months = 132 if the tier says 11 years, otherwise term_months
Monthly and total MIP
Estimated monthly MIP in year 1 uses the average scheduled base-loan balance for months 0 through 11. Estimated total FHA MIP if kept for required time adds the upfront fee to the monthly MIP amounts over the required MIP period.
monthly_mip_year1 = annual_mip_rate * average(balance_before_month_m for m = 0 to 11) / 12
total_fha_mip_estimated = upfront_mip + annual_mip_rate / 12 * sum(balance_before_month_m for m = 0 to mip_duration_months - 1)
The extra monthly payment from financing upfront MIP is the difference between the principal and interest payment on the base loan plus upfront MIP and the payment on the base loan alone.
financed_ufmip_payment_effect = payment_on_base_plus_upfront_mip - payment_on_base_loan if financed, otherwise 0
Mini-example
For a $300,000 home with 3.5 percent down, the down payment is $10,500 and the Base loan amount before upfront MIP is $289,500. The Upfront MIP fee is $5,066.25. With a 30-year term at 6.5 percent and financed upfront MIP, the total loan amount is $294,566.25, the Annual MIP rate used is 55 basis points, Estimated monthly MIP in year 1 is about $132.02, and the Extra monthly payment from financing upfront MIP is about $32.02.
Sources
- Single Family Upfront Premium, Late, and Interest Charges | HUD.gov / U.S. Department of Housing and Urban Development (HUD) - HUD
- Single Family Mortgage Insurance Premiums | HUD.gov / U.S. Department of Housing and Urban Development (HUD) - HUD
- Why did my monthly mortgage payment go up or change? | Consumer Financial Protection Bureau - Consumerfinance
- FHA Mortgage Insurance: What You Need to Know - Nerdwallet