
Estimate monthly rental cash flow before and after reserve savings, then see break-even rent and investor metrics.
Table of contents
How to use our Rental Property Cash Flow Calculator
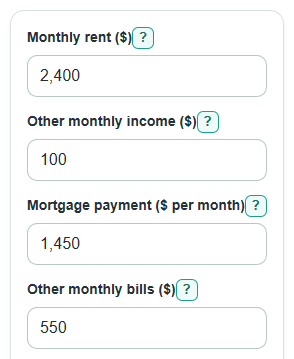
- Enter Monthly rent ($), Other monthly income ($), Mortgage payment ($ per month), Other monthly bills ($), and Property price or value ($).
- Open Advanced options if you want to change Vacancy set-aside (%), Repair set-aside (%), Management fee (%), or Cash put into the deal ($).
- Click Calculate to see Safer monthly cash flow first, then compare it with Cash before reserve savings.
- Check Rent needed to break even. If it is far above realistic market rent, the property may need a lower price, lower debt payment, or lower costs.
- Sanity-check the output by making sure Mortgage payment ($ per month) is not also included in Other monthly bills ($), and that reserve percentages are based on rent only.
Definitions
Safer monthly cash flow: Money left each month after income, mortgage, monthly bills, management fee, and planned vacancy and repair reserve savings.
Cash before reserve savings: Money left before setting aside vacancy and repair reserves. This can be higher than safer cash flow.
Monthly NOI: Net operating income. It is rental income minus operating costs and reserve assumptions before the mortgage payment.
Debt coverage: A ratio that compares Monthly NOI with Mortgage payment ($ per month). Above 1 means NOI is larger than the debt payment.
Cap rate: Yearly NOI divided by Property price or value ($), shown as a percent. It ignores loan payments.
Cash-on-cash return: Safer annual cash flow divided by Cash put into the deal ($), shown as a percent.
Rent needed to break even: The Monthly rent ($) needed for Safer monthly cash flow to equal $0 with the same costs and percent assumptions.
Monthly reserve savings: The planned vacancy and repair set-asides. It is not always cash paid out during the current month.
Common mistakes and quick fixes
Mistake: Putting the same loan cost in Mortgage payment ($ per month) and Other monthly bills ($).
Fix: Put the mortgage in Mortgage payment ($ per month), and use Other monthly bills ($) for taxes, insurance, HOA, utilities, and similar non-mortgage costs.
Mistake: Treating Vacancy set-aside (%) and Repair set-aside (%) as bills that must be paid every month.
Fix: Use those fields as planned reserve savings for future empty months and repairs; compare them with Cash before reserve savings.
Mistake: Entering Vacancy set-aside (%) as a dollar amount, such as 120, when you mean $120.
Fix: Enter the percent of Monthly rent ($), such as 5 for 5%.
Mistake: Leaving Cash put into the deal ($) at 0 and expecting Cash-on-cash return to calculate.
Fix: Enter down payment, closing costs, and initial repair cash in Cash put into the deal ($), or read Cash-on-cash return as N/A.
Mistake: Using Property price or value ($) as the loan amount instead of the property value.
Fix: Enter the purchase price for a new deal or current value for an owned property so Cap rate is based on the property, not just the debt.
Limitations & Key Assumptions / Boundary Conditions
- The calculator is a planning estimate, not tax, legal, lending, or appraisal advice.
- All income and cost inputs are monthly except Property price or value ($), Cash put into the deal ($), and percent fields.
- Vacancy set-aside (%), Repair set-aside (%), and Management fee (%) are applied to Monthly rent ($) only, not to Other monthly income ($).
- Safer monthly cash flow includes reserve savings, but real bank balance can differ because repairs, vacancies, taxes, and insurance bills may happen unevenly.
- Cap rate uses Property price or value ($) and Monthly NOI before debt. It does not include appreciation, sale costs, depreciation, income taxes, or financing terms.
- Cash-on-cash return uses Safer annual cash flow and Cash put into the deal ($). It is N/A when cash invested is $0 or less.
- Debt coverage is N/A when Mortgage payment ($ per month) is $0 because there is no debt payment to compare with NOI.
- Break-even rent is N/A if Vacancy set-aside (%), Repair set-aside (%), and Management fee (%) add to 100% or more.
Methodology
How the calculator works
The calculator first adds rent and other regular property income. It then subtracts operating bills, management, vacancy reserve, repair reserve, and the mortgage payment. Negative cash flow is kept as a negative number because it means the property needs outside money at the entered assumptions.
gross_monthly_income = monthly_rent + other_monthly_income
vacancy_amount = monthly_rent * vacancy_rate / 100
repair_amount = monthly_rent * repair_rate / 100
management_amount = monthly_rent * management_rate / 100
monthly_noi = gross_monthly_income - vacancy_amount - repair_amount - management_amount - monthly_operating_bills
monthly_safe_cash_flow = monthly_noi - monthly_mortgage_payment
Reserve comparison
Cash before reserve savings leaves out vacancy and repair set-asides. This shows the difference between cash that may be left in the bank this month and the safer amount after planning for future problems.
monthly_bank_cash_flow = gross_monthly_income - management_amount - monthly_operating_bills - monthly_mortgage_payment
monthly_reserve_total = vacancy_amount + repair_amount
annual_safe_cash_flow = monthly_safe_cash_flow * 12
Break-even rent and investor metrics
Break-even rent solves for the Monthly rent ($) that makes safer monthly cash flow equal $0. The formula works only when the combined vacancy, repair, and management percentages are below 100%.
break_even_rent = (monthly_operating_bills + monthly_mortgage_payment - other_monthly_income) / (1 - (vacancy_rate + repair_rate + management_rate) / 100)
cap_rate = (monthly_noi * 12) / purchase_price * 100
cash_on_cash_return = annual_safe_cash_flow / cash_invested * 100
dscr = monthly_noi / monthly_mortgage_payment
Mini-example
With Monthly rent ($) of 2400, Other monthly income ($) of 100, Mortgage payment ($ per month) of 1450, Other monthly bills ($) of 550, Vacancy set-aside (%) of 5, Repair set-aside (%) of 8, and Management fee (%) of 0, gross monthly income is $2500. Vacancy reserve is $120 and repair reserve is $192. Monthly NOI is $1638, safer monthly cash flow is $188, cash before reserve savings is $500, and safer annual cash flow is $2256.
Calculation choices
Money inputs may include commas, spaces, or a leading dollar sign. Percent inputs must be valid non-negative numbers. Cap rate is shown as N/A if Property price or value ($) is $0 or less. Cash-on-cash return is shown as N/A if Cash put into the deal ($) is $0 or less. Debt coverage is shown as N/A when there is no Mortgage payment ($ per month).
Sources
- How To Run a Rental Cash Flow Analysis | Apartments.com - Apartments
- Washington State Dept. of Revenue - Disclosure Glossary (includes a definition for Debt Service Coverage Ratio (DSCR)) - WA
- What are government recording charges for a mortgage? | Consumer Financial Protection Bureau - Consumerfinance