
Estimate purchase closing costs and cash to close, or refinance closing costs. Choose a simple purchase estimate or itemize fees, prepaid costs and escrow.
Itemized costs replace the simple planning estimate. Base fees exclude the separately entered points, program fee, prepaids and escrow.
Advanced options
Table of contents
For a purchase, choose "Home purchase" and either "Simple purchase estimate" or "Itemized costs". The simple rate uses the purchase price. Itemized percentage fees use purchase price minus down payment.
For a refinance, choose "Refinance" and enter "Refinance loan amount ($)". The calculator uses itemized costs and subtracts the lender credit. This is a closing-cost budget, not full refinance cash to close: existing loan payoffs, cash-out proceeds and financed costs are not included.
In "Itemized costs", enter base fees, discount points, any program fee, prepaid interest days and other prepaid costs. Initial escrow equals annual property tax × tax escrow months ÷ 12 plus annual homeowners insurance × insurance escrow months ÷ 12. Use amounts from your lender; an upfront premium and an escrow deposit are separate expenses.
For example, a $200,000 refinance with 2% base fees, 1% points, a $500 program fee and a $1,000 lender credit costs $5,500 after credit if other items are zero. Adding $1,200 annual tax for 3 escrow months and $1,200 annual insurance for 2 escrow months adds $500.
How to use the simple purchase estimate
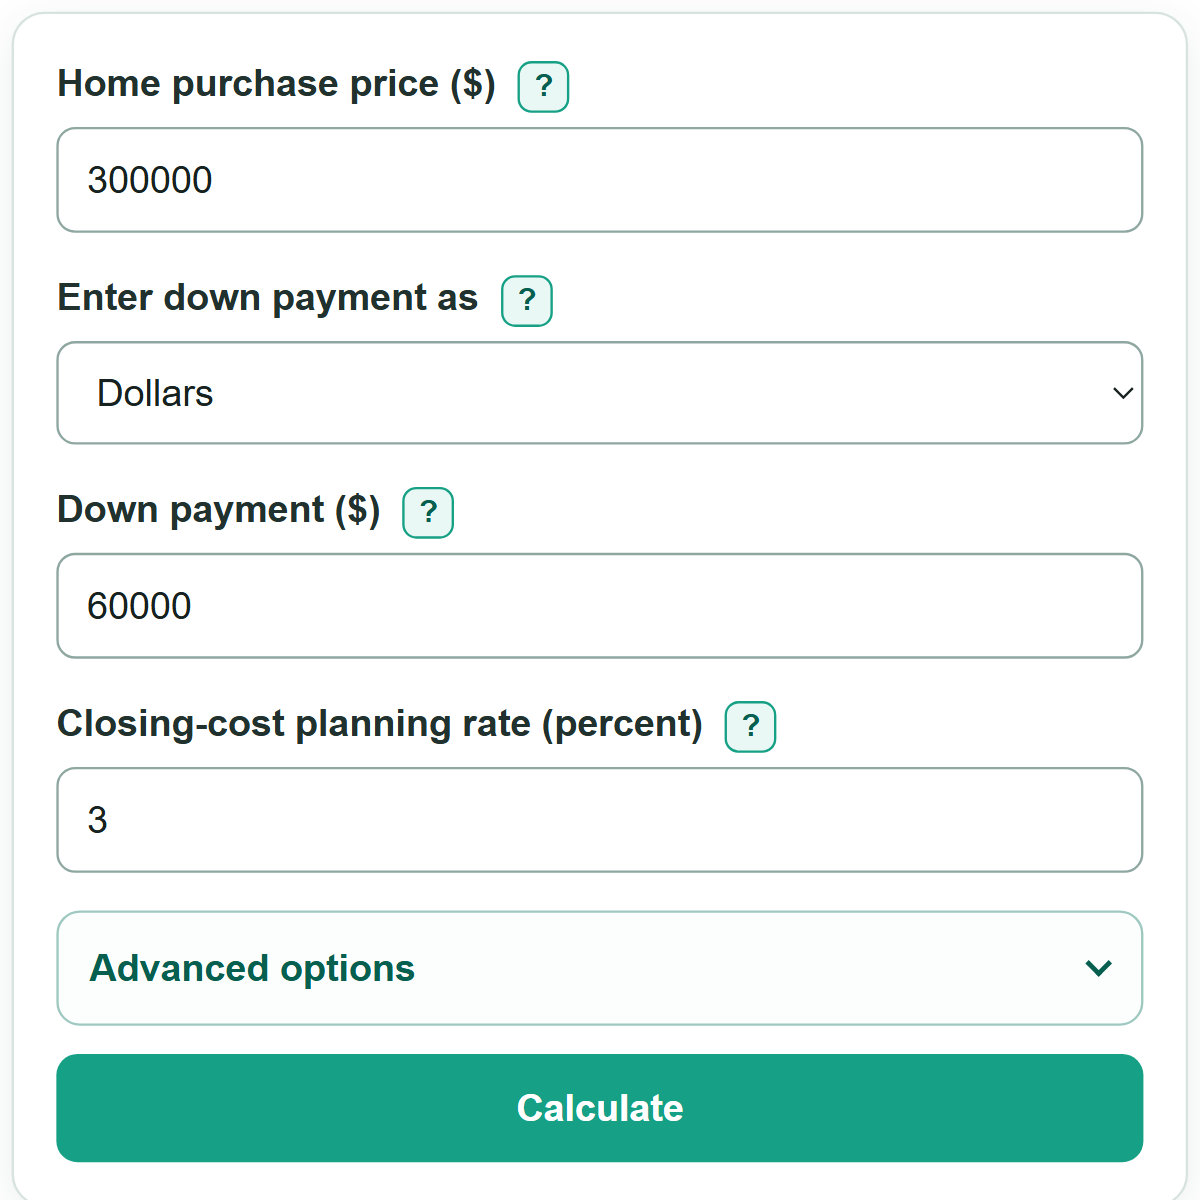
- Enter the planned or agreed amount in "Home purchase price ($)".
- Choose dollars or percent in "Enter down payment as", then enter the down payment in that same form.
- Enter a local estimate in "Closing-cost planning rate (percent)" from a lender, agent, or earlier Loan Estimate.
- Open "Advanced options" to add a seller credit, lender credit, or deposit already paid if you know those amounts.
- Select "Calculate", then check that the down payment and estimated loan amount fit your financing plan before budgeting from estimated cash to close.
Definitions
Closing costs: Charges related to getting a mortgage for a purchase or refinance. The simple purchase estimate uses one percentage-based amount; itemized costs add the separate fees, prepaids and escrow you enter.
Cash to close: The estimated money still needed at closing after adding the down payment and estimated closing costs, then subtracting entered credits and a deposit already paid.
Seller credit: Money the seller agrees to contribute toward eligible buyer closing expenses.
Lender credit: Money the lender applies toward eligible closing expenses. It may be connected to the loan's pricing.
Closing Disclosure: A form used to review final loan terms, projected payments, and closing costs before closing. [1]
Common mistakes and quick fixes
Mistake: Treating estimated closing costs as the same as cash to close.
Fix: Closing costs are the gross fee estimate. Cash to close also includes the down payment and subtracts entered credits and a deposit already paid.
Mistake: Entering a percentage while "Enter down payment as" is set to dollars.
Fix: Select "Percent of purchase price" before entering a percentage. Otherwise, enter the down payment as a dollar amount.
Mistake: Using a general rate as though it were a final quote.
Fix: Replace the planning rate with an estimate from your lender, agent, or Loan Estimate when available.
Mistake: Counting earnest money twice.
Fix: Enter it in "Deposit already paid ($)" only if it is expected to count toward closing, then do not add it again to your remaining cash plan.
Mistake: Typing comma groups such as 30,0,000.
Fix: Enter 300000 or use standard grouping such as 300,000.
Limitations & Key Assumptions / Boundary Conditions
- This is a preliminary estimate using your supplied rates and amounts. It does not look up state, county, city, or property-specific charges.
- The simple purchase planning rate is an all-in percentage of purchase price. In "Itemized costs", base fees and discount points use the loan amount; prepaids and escrow are added separately. Do not count the same cost twice.
- For a purchase, the estimated loan amount is purchase price minus down payment; for a refinance, it is the loan amount you enter. The calculator does not add financed fees or assess loan limits or underwriting rules.
- Credits and deposits reduce the simplified cash-to-close estimate, but actual credit limits and deposit treatment must be confirmed with the lender or settlement provider.
- A negative cash-to-close estimate means the entered credits and deposit exceed this simplified calculation. It does not guarantee money will be returned to the buyer.
- Use the lender's Loan Estimate and final Closing Disclosure to confirm the actual amount due at closing.
Methodology
Calculation method
For "Simple purchase estimate", the calculator changes the down payment into dollars and applies the planning rate to the purchase price. "Itemized costs" instead adds loan-based fees and points, the program fee, prepaid interest, other prepaids and initial escrow. Purchase cash to close adds the down payment and subtracts credits and the deposit. Refinance costs after credit subtract only the lender credit; they exclude loan payoff and financing adjustments.
Down payment in dollars = purchase price x down payment percent / 100
Purchase loan amount = purchase price - down payment in dollars
Simple purchase closing costs = purchase price x closing-cost planning rate / 100
Total credits applied = seller credit + lender credit
Purchase cash to close = down payment + estimated closing costs - deposit already paid - total credits applied
Worked example
For a $300,000 purchase price, $60,000 down payment, and 3% planning rate, estimated closing costs are $9,000. With no credits and no deposit already paid, estimated cash to close is $69,000 and the estimated loan amount is $240,000.
Limits of the estimate
The rate is a planning input, not a quote. Actual charges can differ because of the property, location, loan terms, selected providers, prepaids, escrow funding, and credit limits. The calculation keeps a negative cash-to-close result when entered credits and deposits exceed the simplified estimate; confirm that situation with the lender or settlement provider. Review the Closing Disclosure for final loan terms and closing costs before closing. [1]