
Estimate your jumbo mortgage payment and see how your loan compares with a selected 2026 conforming loan limit.
Table of contents
How to use our Jumbo Mortgage Calculator
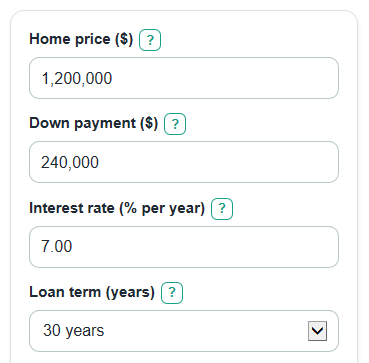
- Enter the Home price ($), Down payment ($), Interest rate (% per year), and Loan term (years).
- Choose the Conforming loan limit to check. If you choose Use my own limit, enter Your conforming limit ($).
- Open Advanced options only if you want Property tax ($ per year), Homeowners insurance ($ per year), HOA dues ($ per month), Household income ($ per year), or Other monthly debt payments ($) included.
- Click Calculate and read Monthly principal and interest first, then Jumbo status and Extra down payment needed to avoid jumbo.
- Sanity-check the result by confirming the Estimated loan amount equals Home price ($) minus Down payment ($), and make sure optional costs are not left at $0 by mistake.
Definitions
Jumbo status: The calculator's label for whether the Estimated loan amount is above the selected conforming loan limit.
Conforming loan limit: The dollar line used to decide whether a one-unit mortgage is within the selected 2026 conforming limit or above it.
Monthly principal and interest: The scheduled loan payment that pays down the borrowed amount and pays interest. It does not include taxes, insurance, HOA dues, or other costs.
Estimated total monthly payment: Monthly principal and interest plus any Property tax ($ per year), Homeowners insurance ($ per year), and HOA dues ($ per month) entered in Advanced options.
Loan share of home price: The Estimated loan amount divided by Home price ($), shown as a percent. Lenders often call this loan-to-value, or LTV.
Housing payment share of income: The Estimated total monthly payment divided by gross monthly income.
Housing plus other debt share of income: The Estimated total monthly payment plus Other monthly debt payments ($), divided by gross monthly income.
Common mistakes and quick fixes
Mistake: Entering the Home price ($) after subtracting the down payment.
Fix: Put the full purchase price in Home price ($) and put your cash down payment in Down payment ($).
Mistake: Typing the Interest rate (% per year) as APR when you meant the note rate.
Fix: Use the quoted mortgage interest rate in Interest rate (% per year); APR can include some loan costs.
Mistake: Choosing the wrong Conforming loan limit to check for the county.
Fix: Use the standard 2026 limit for most areas, the high-cost option only when it applies, or enter Your conforming limit ($) if you know the exact county limit.
Mistake: Leaving Property tax ($ per year), Homeowners insurance ($ per year), and HOA dues ($ per month) at 0, then treating Estimated total monthly payment as a full housing budget.
Fix: Add realistic yearly tax, yearly insurance, and monthly HOA amounts if you want a fuller monthly estimate.
Mistake: Putting the new mortgage payment into Other monthly debt payments ($).
Fix: Use Other monthly debt payments ($) only for debts such as car loans, student loans, credit cards, and other recurring payments.
Mistake: Entering take-home pay in Household income ($ per year).
Fix: Use gross yearly household income before taxes if you want Housing payment share of income and Housing plus other debt share of income.
Limitations & Key Assumptions / Boundary Conditions
- The conforming limit check is for one-unit 2026 limits only. Multi-unit properties, special programs, and exact county rules may use different limits.
- The standard and high-cost limit choices use the 2026 values named in the calculator. If your county has a different one-unit limit, choose Use my own limit.
- The payment assumes a fixed-rate fully amortizing mortgage with equal monthly payments for the selected Loan term (years).
- Estimated total monthly payment is a planning number. It can differ from a lender's payment because escrow setup, mortgage insurance, flood insurance, special assessments, and closing costs are not included unless you add them yourself.
- Debt-to-income outputs appear only when Household income ($ per year) is entered and greater than $0. They are estimates, not an approval decision.
- Taxes, insurance, HOA dues, income, and debt values are assumed to stay constant for the calculation.
Methodology
Core loan math
The calculator first estimates the loan amount from the purchase price and down payment.
loan_amount = home_price - down_payment
It then calculates the number of monthly payments.
n = loan_term_years * 12
For a nonzero yearly interest rate, the calculator uses the standard fixed-rate mortgage payment formula. The monthly rate is the yearly percent rate divided by 100 and then by 12.
r = annual_rate / 100 / 12
monthly_pi = loan_amount * r * (1 + r)^n / ((1 + r)^n - 1)
If the yearly interest rate is 0%, the calculator avoids division by zero and uses an even principal payment.
monthly_pi = loan_amount / n
Total interest is the total scheduled principal and interest payments minus the amount borrowed.
total_interest = monthly_pi * n - loan_amount
Jumbo line check
The selected conforming limit is $832,750 for the 2026 standard one-unit option and $1,249,125 for the 2026 high-cost one-unit option [1]. If Use my own limit is selected, the calculator uses Your conforming limit ($).
amount_over_limit = loan_amount - selected_limit
A positive Amount over or under the limit means the loan is above the selected limit. A negative value means the loan is below the selected limit.
extra_down_to_conform = max(0, amount_over_limit)
down_payment_to_conform = down_payment + extra_down_to_conform
Optional monthly costs and income shares
Principal and interest are separate from the broader monthly payment that may include taxes, insurance, and other housing costs [3]. The calculator adds the optional yearly costs after converting them to monthly amounts.
total_monthly_payment = monthly_pi + annual_property_tax / 12 + annual_homeowners_insurance / 12 + monthly_hoa
ltv_percent = loan_amount / home_price * 100
If Household income ($ per year) is entered, gross monthly income is annual income divided by 12.
front_dti = total_monthly_payment / (annual_income / 12) * 100
back_dti = (total_monthly_payment + monthly_debts) / (annual_income / 12) * 100
Mini example
For a $1,200,000 home with a $240,000 down payment, the estimated loan amount is $960,000. At 7.00% for 30 years, monthly principal and interest is about $6,386.90. Against the 2026 standard limit of $832,750, the loan is $127,250 over the line, so the extra down payment needed to avoid jumbo status is $127,250.