
Estimate a bridge loan payment, the feasible loan amount, total cost, and cash left after your current home sells.
Table of contents
How to use our Bridge Loan Calculator
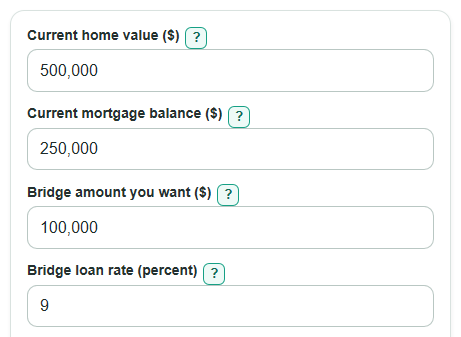
- Enter Current home value ($), Current mortgage balance ($), and Bridge amount you want ($) for the home you plan to sell.
- Enter Bridge loan rate (percent) and How long you will carry it (months) to estimate the interest-only payment and interest cost.
- Open Advanced options if you want to change Max debt allowed on current home (percent of value), Bridge loan fee (percent of bridge amount), Other bridge fees ($), Expected sale price of current home ($), or Selling costs (percent of sale price).
- Click Calculate and read Estimated monthly bridge payment first, then check Bridge amount used for this estimate and How much room is left or missing to see if the requested amount fits the LTV cap.
- Sanity-check Estimated cash left after sale and bridge costs: if it is negative or much lower than expected, recheck the sale price, selling costs, payoff balance, and bridge fee inputs before using the result for a buying plan.
Definitions
Bridge loan: A short-term loan used to cover a cash gap while you buy a new home before selling your current home.
Current mortgage balance ($): The payoff amount still owed on the current home, not the regular monthly payment.
Combined LTV: Loan-to-value after adding the current mortgage and the bridge loan, shown as a percent of the current home's value.
Max debt allowed on current home (percent of value): The lender's cap for total debt secured by the current home compared with that home's value.
Interest-only payment: A payment that covers interest for the month but does not reduce the bridge loan principal.
Origination fee: A lender charge for making the loan, often entered as a percent of the loan amount.
Selling costs (percent of sale price): Estimated costs paid from the sale, such as agent commission and seller closing costs.
Signed gap: In How much room is left or missing, a positive value means room remains under the cap, and a negative value means the requested bridge amount is over the cap.
Common mistakes and quick fixes
Mistake: Entering the monthly payment in Current mortgage balance ($).
Fix: Enter the payoff balance you expect to owe when the old home sells.
Mistake: Using Bridge amount you want ($) as if it is always approved.
Fix: Check Bridge amount used for this estimate and How much room is left or missing; payment math uses the LTV-capped amount when the request is too high.
Mistake: Typing a monthly rate into Bridge loan rate (percent).
Fix: Enter the yearly rate, such as 9 for 9% per year.
Mistake: Leaving Max debt allowed on current home (percent of value) at 80 when your lender quoted a different cap.
Fix: Replace it with the lender's combined LTV limit so Estimated max bridge amount is closer to the real quote.
Mistake: Forgetting Selling costs (percent of sale price) when checking Estimated cash left after sale and bridge costs.
Fix: Include agent commission, seller closing costs, and other sale costs as a percent of the expected sale price.
Mistake: Putting all lender costs into Bridge loan fee (percent of bridge amount) when some are flat charges.
Fix: Put percent-based points in Bridge loan fee (percent of bridge amount) and flat charges in Other bridge fees ($).
Limitations & Key Assumptions / Boundary Conditions
- The calculator assumes interest-only bridge payments with simple monthly interest. It does not model daily interest, compounding, late fees, escrow, or principal paydown.
- Payment, interest, and fee estimates use Bridge amount used for this estimate, which is capped by Estimated max bridge amount. They do not use an impossible requested amount.
- Estimated max bridge amount is based only on Current home value ($), Current mortgage balance ($), and Max debt allowed on current home (percent of value). A lender may approve less based on credit, income, property type, reserves, appraisal, or program rules.
- Estimated cash left after sale and bridge costs depends heavily on Expected sale price of current home ($) and Selling costs (percent of sale price). A lower sale price or higher seller costs can quickly reduce this number.
- Upfront bridge fees may be paid at closing, financed, or paid another way. This calculator counts them as a cost when estimating cash left after sale.
- A negative Estimated cash left after sale and bridge costs is not blocked. It means the expected sale may not cover the listed selling costs, old mortgage payoff, bridge principal, interest, and bridge fees.
- This is a planning estimate, not a loan approval or closing statement. Use lender disclosures and a settlement estimate before making a purchase decision.
Methodology
How the bridge amount is capped
The calculator first estimates how much bridge borrowing fits under the combined debt cap on the current home. If the requested bridge amount is higher than that cap, the payment and cost math uses the capped amount instead of the requested amount.
max_bridge_amount = max(0, current_home_value * max_combined_ltv_percent / 100 - current_mortgage_balance)
bridge_amount_used = min(requested_bridge_amount, max_bridge_amount)
requested_amount_gap = max_bridge_amount - requested_bridge_amount
A positive requested_amount_gap means there is still room under the cap. A negative value means the requested bridge amount is too high for the entered cap.
Payment, interest, and bridge costs
The monthly payment is interest-only. The yearly rate is divided by 100 to turn the percent into a decimal and divided by 12 months to get a monthly rate.
monthly_interest_payment = bridge_amount_used * (annual_rate_percent / 100) / 12
total_interest = monthly_interest_payment * bridge_term_months
upfront_bridge_fees = bridge_amount_used * origination_fee_percent / 100 + fixed_bridge_fees
total_bridge_cost = total_interest + upfront_bridge_fees
Total bridge cost includes interest and upfront bridge fees. It does not include repaying principal, because principal is borrowed money being returned.
Debt level and sale cash
The calculator also estimates the debt level after the bridge loan and the cash left after selling the current home.
combined_ltv_percent = (current_mortgage_balance + bridge_amount_used) / current_home_value * 100
old_home_payoff_needed = current_mortgage_balance + bridge_amount_used
cash_left_after_sale_and_costs = expected_sale_price - (expected_sale_price * selling_cost_percent / 100) - current_mortgage_balance - bridge_amount_used - total_interest - upfront_bridge_fees
Cash left after sale is signed. A negative value means the expected sale price does not cover the listed sale costs, mortgage payoff, bridge principal, interest, and bridge fees.
Mini example
Suppose Current home value ($) is $500,000, Current mortgage balance ($) is $250,000, Bridge amount you want ($) is $100,000, Max debt allowed on current home (percent of value) is 80, Bridge loan rate (percent) is 9, and How long you will carry it (months) is 6. The estimated max bridge amount is $150,000, so the $100,000 request fits. The monthly interest-only payment is $750, total interest is $4,500, and a 1% Bridge loan fee (percent of bridge amount) adds $1,000. If Expected sale price of current home ($) is $500,000 and Selling costs (percent of sale price) is 6, the estimated cash left after sale and bridge costs is $114,500.