
Estimate the full cost of settling debt, including creditor payments, help fees, possible tax, and the monthly amount to save.
Advanced options
Table of contents
How to use our Debt Settlement Calculator
- Enter Total debt to settle ($) for the unsecured debt you want to compare.
- Enter Settlement offer (percent of debt), then choose how the Help fee is based on.
- Fill in Help fee rate (percent) or Flat help fee ($), and enter Time to save for settlement (months).
- Open Advanced options if you want to add Tax rate for forgiven debt (percent), Forgiven debt that may be excluded ($), or Other program costs ($).
- Check whether Estimated total cost is less than the original debt and whether Monthly amount to set aside fits your budget before comparing quotes.
Definitions
Total debt to settle ($): The starting balance of the debts you want to settle.
Settlement offer (percent of debt): The percent of the starting debt paid to the creditor. A 50 percent offer on $10,000 means a $5,000 creditor payment.
Forgiven debt: The part of the original debt not paid to the creditor through the settlement.
Help fee: A fee paid for debt settlement help. The same percent can produce different dollar fees depending on whether it is based on enrolled debt, settlement payment, or forgiven debt.
Taxable forgiven debt: The forgiven debt used for the tax estimate after subtracting the excluded amount entered. This calculator floors this tax-only number at $0.
Net savings: Original debt minus the estimated total cost. A negative number means the estimate costs more than paying the original debt balance.
Monthly amount to set aside: The estimated total cost divided by the number of months you plan to save.
Common mistakes and quick fixes
Mistake: Putting secured debt into Total debt to settle ($) , such as a mortgage or car loan.
Fix: Use only the unsecured debt you are actually considering for settlement unless you know the debt is unsecured.
Mistake: Entering the discount in Settlement offer (percent of debt) instead of the percent paid to the creditor.
Fix: If you expect to pay half of the debt, enter 50, not 50 saved or 0.50.
Mistake: Leaving Help fee is based on set to the wrong fee basis.
Fix: Match the quote: enrolled debt, settlement payment, forgiven debt, flat fee, or no help fee.
Mistake: Typing a dollar fee into Help fee rate (percent) when the quote uses a fixed fee.
Fix: Choose Flat fee under Help fee is based on , then enter the dollar amount in Flat help fee ($) .
Mistake: Using Tax rate for forgiven debt (percent) without adjusting Forgiven debt that may be excluded ($) when an exclusion may apply.
Fix: Enter the forgiven amount you believe may be excluded, or use 0 if you are not estimating that adjustment.
Mistake: Ignoring Other program costs ($) when a quote includes account, setup, or monthly charges.
Fix: Add those extra costs so Estimated total cost is closer to the real plan cost.
Limitations & Key Assumptions / Boundary Conditions
- This is a planning estimate, not legal, tax, credit, or debt settlement advice.
- Actual settlement offers are not guaranteed. Creditors may refuse an offer, require different timing, or continue collection activity.
- The calculator does not add future interest, late fees, collection fees, or credit score effects while money is being saved.
- The tax estimate is simplified. Canceled-debt tax treatment can depend on insolvency, bankruptcy, exclusions, filing details, and tax law.
- Forgiven debt that may be excluded ($) only changes the tax estimate. It does not reduce Debt forgiven by settlement.
- Net savings compared with paying the full debt keeps negative values. A negative result means the entered plan is more expensive than the original debt balance.
- Monthly amount to set aside assumes the full estimated cost is saved evenly across the entered months. Real plans may need lump-sum payments or changing deposits.
Methodology
Calculation method
The calculator first turns percent inputs into decimals by dividing by 100. It then estimates the creditor payment, forgiven debt, help fee, possible tax, total cost, net savings, net savings rate, and monthly savings target.
settlement_payment = debt_amount * (settlement_percent / 100)
forgiven_debt = debt_amount - settlement_payment
help_fee = 0 when fee_method is none
help_fee = debt_amount * fee_rate / 100 when fee_method is percent_enrolled
help_fee = settlement_payment * fee_rate / 100 when fee_method is percent_settlement
help_fee = forgiven_debt * fee_rate / 100 when fee_method is percent_forgiven
help_fee = flat_fee when fee_method is fixed
taxable_forgiven_debt = max(0, forgiven_debt - insolvency_amount)
estimated_tax = taxable_forgiven_debt * tax_rate / 100
total_estimated_cost = settlement_payment + help_fee + other_program_fees + estimated_tax
net_savings = debt_amount - total_estimated_cost
net_savings_percent = (net_savings / debt_amount) * 100
monthly_savings_needed = total_estimated_cost / months_to_save
Worked example
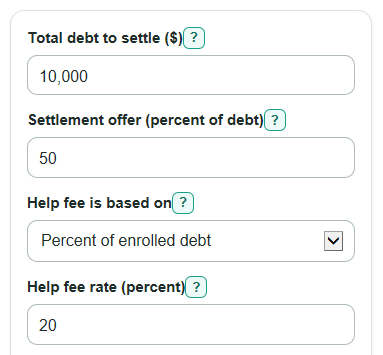
For $10,000 of debt, a 50 percent settlement offer gives a $5,000 amount paid to the creditor and $5,000 of forgiven debt. If the help fee is 20 percent of enrolled debt, the fee is $2,000. With no other program costs and no tax estimate, total estimated cost is $7,000. Net savings is $3,000, the net savings rate is 30 percent, and saving over 24 months requires about $291.67 per month.
Input checks
The calculator requires debt greater than $0, a settlement offer from 0 to 100 percent, a saving time greater than 0 months, nonnegative dollar costs, and valid percent entries where used. It reads only the fee input that matches the selected fee method, so a hidden flat fee or percent fee does not affect the result.